


Georgia Public Adjusters
Hurricane, hail, tornado & fire claims from Atlanta to Savannah — no recovery, no fee.
We help Georgia property owners fight underpaid and delayed hurricane, hail, tornado, wind, fire and water insurance claims. Licensed in Georgia, including the $5,000 surety bond every Georgia public adjuster must carry — no recovery, no fee.
We specialize in hurricane, hail, tornado and wind claims — the losses Georgia carriers most often underpay.
Underpaid, disputed, or stuck?
Georgia carriers reach for the same three moves after every hurricane, hail storm, and tornado. We fight all three.
Was your hurricane or hail claim underpaid?
Patch-priced roofs, contents depreciated to zero. We rebuild your estimate from the actual loss — and once your proof of loss is in, the carrier gets 60 days to accept or deny, not forever. (r. 120-2-52-.03(3))
Did they call your damage “wear and tear”?
Hail bruising and wind-lifted shingles blamed on age — the oldest move in the book. We prove the storm date, the damage pattern, and what your policy actually covers.
Is your Helene claim still open?
Months later, Georgia claims are still pending. Open or underpaid, we pick up the file and force the deadlines: 15 days to acknowledge, 10 days to pay. (r. 120-2-52-.03)
Types of claims we handle in Georgia.
Hurricanes along the coast, hail and tornadoes across the Atlanta metro and north Georgia, straight-line wind, and house fires — plus the commercial claims carriers underpay most.

Single-Family Homes
Hail bruising and tornado tracks across north Georgia; roof and siding scopes cut to patch repairs, contents depreciated to nothing.

Historic & Older Homes
Savannah and Macon’s older housing stock — storm-driven water blamed on excluded flood, fire and smoke damage past the burn area ignored.

Townhomes & Condos
Wind-driven rain and upstairs-neighbor leaks; tear-out, drying, and mold remediation undercounted, HOA master-policy gaps exploited.

Farms & Rural Property
Poultry houses, barns, and equipment losses depreciated hard — Helene hit Georgia agriculture for billions, and scopes still come in short.

Multi-Family & HOA Communities
Association claims minimized building by building; shared roofs, siding, and common areas underpaid after every coastal storm.

Warehouses & Industrial Buildings
Large-loss scopes cut; depreciation, overhead-and-profit, and business-interruption games on metro Atlanta’s industrial corridors.
Not sure your offer covers the real damage?
Get a Free Claim ReviewJustClaims vs. the insurance company’s adjuster.
Georgia law lets you hire your own licensed public adjuster to level the playing field. Here is how the three options stack up.
Georgia makes every public adjuster carry a $5,000 bond — and requires their contract to be pre-approved by the Commissioner before they work with you (O.C.G.A. § 33-23-43.2).
Run the math on your Georgia policy.
Georgia law puts these numbers in writing. We hold carriers to every one.
Your insurer must acknowledge your claim — in writing, in the claim file — within 15 days of your notice. (r. 120-2-52-.03(1))
Once your completed proof of loss is in, the carrier must affirm or deny within 60 days. No endless “still under review.” (r. 120-2-52-.03(3))
Coverage confirmed, amount set? Payment must be tendered within 10 days. Not “processing” — paid. (r. 120-2-52-.03(4))
Georgia requires public adjusters to be bonded. We carry a $5,000 surety bond in favor of the Commissioner — ask to see it.
A name Georgia owners trust.
From Atlanta to Savannah, Augusta to Columbus, JustClaims represents Georgia policyholders only — never insurance companies.

Licensed in Georgia.
Taylor Bezek, Georgia public adjuster license #3395391 (individual) — verified active with the Georgia Office of Commissioner of Insurance.
Verify us with the state.
Check our licenses free at the Georgia OCI license lookup before you sign anything.
Bonded, with a state-approved contract.
Georgia requires a $5,000 bond and a Commissioner-approved contract (O.C.G.A. § 33-23-43.2). We carry both.
No recovery, no fee.
Your claim review is free, and there is no retainer or hourly billing. We are paid only when you recover.
Want a licensed Georgia team that works only for you?
Get a Free Claim ReviewWhy Georgia properties need a public adjuster.
Georgia sees billion-dollar hurricane seasons and destructive hail and tornado outbreaks, and insurers lean on preferred-contractor scopes that come in below full replacement cost. A public adjuster is licensed by the Georgia Office of Commissioner of Insurance to represent only the policyholder, never the carrier.
Your Public Adjuster
Works only for you. We step in when the carrier underpays, delays, or denies. We review the policy, document the full loss independently, file or reopen the claim, and negotiate for the maximum recovery your policy supports.
The Insurer’s Adjuster
Works for the insurance company. They assess your loss in the carrier’s interest, often using preferred-contractor scopes. On hurricane, hail, and tornado losses in particular, that first number is rarely the full number.
We serve all of Georgia.
Choose your market for details. Our Georgia team serves homeowners, farms, and businesses from Atlanta to Savannah, Augusta to Columbus — the coast to the north Georgia hills.
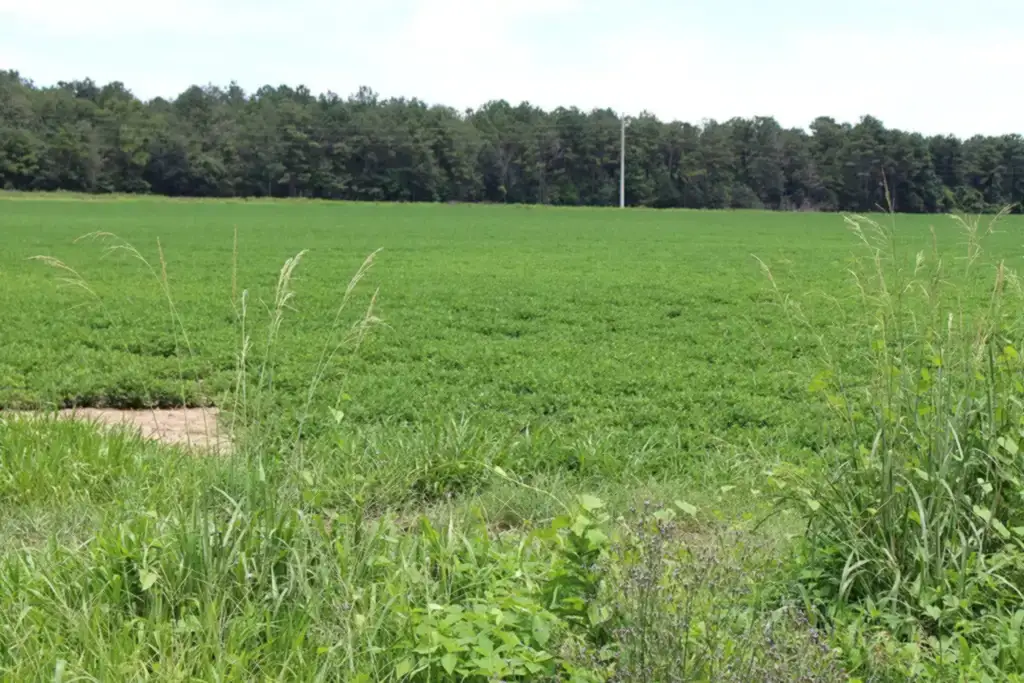
A Georgia public adjuster for farm and rural property claims.
Hurricanes, tornadoes, and straight-line winds hit poultry houses, barns, equipment, and crops across rural Georgia — Hurricane Helene alone cost Georgia agriculture billions. Carriers still scope farm losses like small house claims. We document them the way they are actually priced.
-
Poultry houses & barns.
Full replacement scope on farm structures — not a patch-and-depreciate estimate.
-
Peanut, pecan & cotton operations.
Storm losses to crops, irrigation, and storage counted and valued from real market prices.
-
Equipment & lost income.
Machinery, feed, and business-interruption losses documented, not rounded away.
How Georgia property owners work with JustClaims.

Free claim review
We review your policy and storm damage at no cost, and tell you straight whether a public adjuster is worth it for your claim.

Inspection & estimate
Your adjuster documents the full loss — roof, interior, contents — and prices it with our own independent estimate.

Carrier negotiation
We file or reopen your claim and negotiate directly — holding the insurer to Georgia's 15-, 60-, and 10-day deadlines.
Settlement & payment
When the claim settles, the carrier pays, and our fee comes out of the recovery. We are paid only when you are.
Talk to us before the carrier’s adjuster writes the first estimate.
Get a Free Claim ReviewWhat Georgia policyholders need to know.
→ 15 days to acknowledge
Your insurer must acknowledge your claim — and note it in the claim file — within 15 days of your notice (Ga. Comp. R. & Regs. r. 120-2-52-.03(1)).
→ 60 days to accept or deny
Once your completed proof of loss is in, the carrier must affirm or deny fire and extended-coverage claims within 60 days (r. 120-2-52-.03(3)).
→ 10 days to pay what’s undisputed
After coverage is confirmed and the amount determined, payment must be tendered within 10 days (r. 120-2-52-.03(4)).
→ Bonded & state-approved
Every Georgia public adjuster must carry a $5,000 surety bond — and their contract must be pre-approved by the Insurance Commissioner before they work with you (O.C.G.A. § 33-23-43.2).
Georgia rules set the deadlines. We make sure the carrier keeps them.
Get a Free Claim ReviewThis is general information, not legal advice. Rules and deadlines change — confirm the specifics for your situation.
Why Georgia owners call JustClaims.
We lead with credentials, not made-up dollar figures: a Georgia-licensed, bonded public adjusting team serving hurricane, hail, tornado, wind, and fire claims statewide.
From our public adjusters across Georgia
Four Georgia markets. One team.
Our Georgia team serves property owners statewide — Atlanta is live now, with Savannah, Augusta, and Columbus coming soon under one licensed Georgia team.
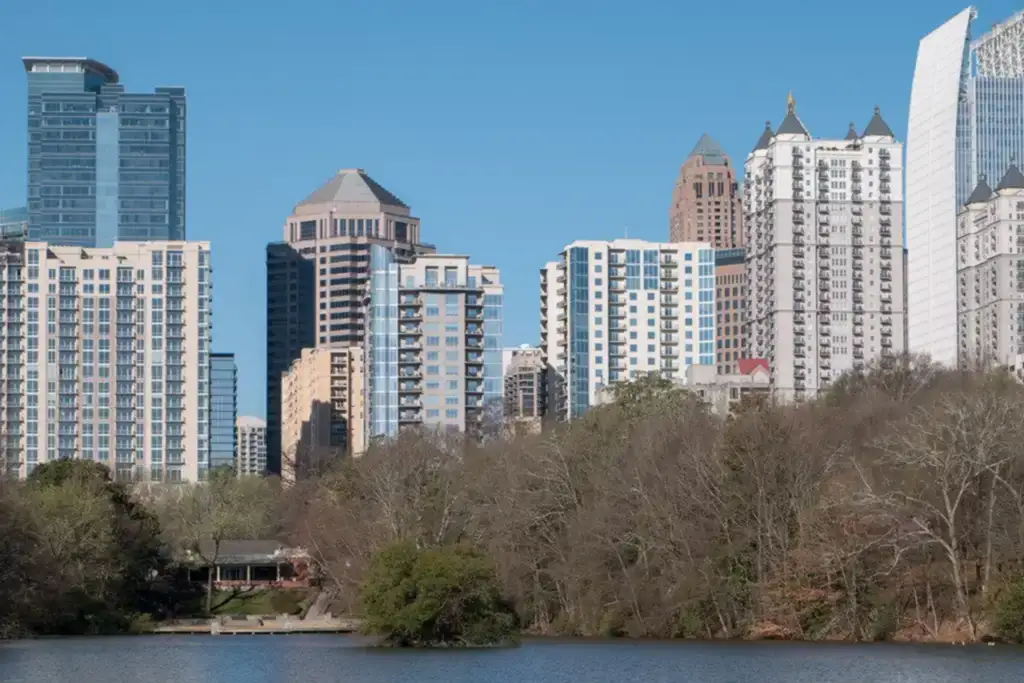
Atlanta
Georgia’s metro core — hail, tornado, wind and water claims from Buckhead to the Perimeter.
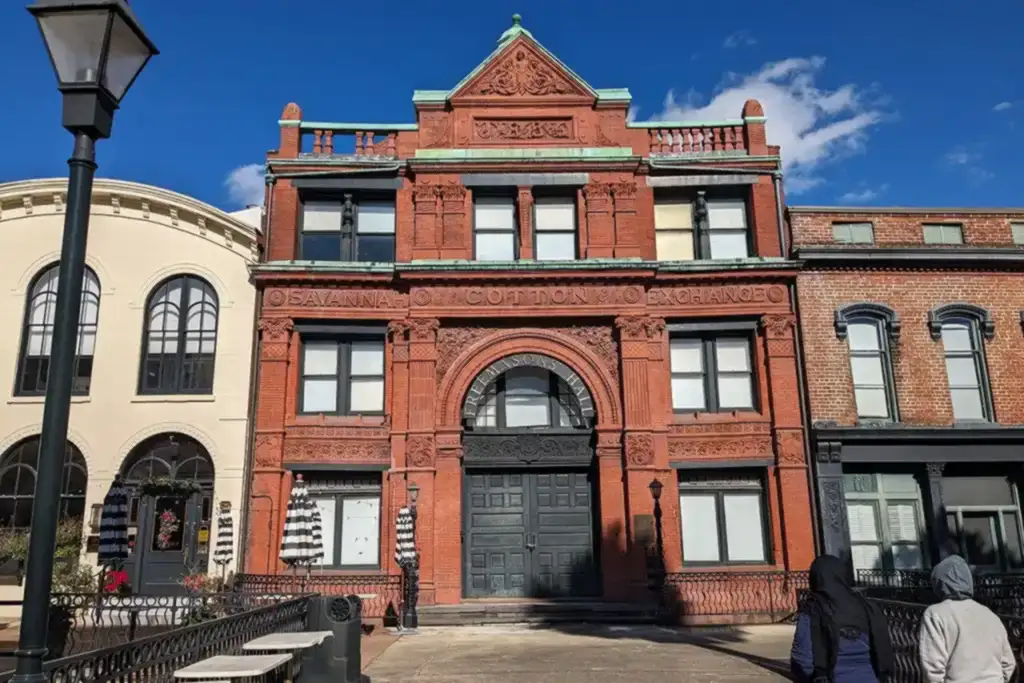
Savannah
Coastal Georgia’s historic port — hurricane, wind and water claims from the islands to downtown.
Coming Soon
Augusta
The Garden City on the Savannah River — storm, hail and fire claims across the CSRA.
Coming Soon
Columbus
Chattahoochee Valley hub — tornado, wind and storm claims for homes and businesses.
Coming Soon
Meet our Georgia lead public adjuster

Taylor Bezek
As General Manager at JustClaims, Taylor Bezek leads our Georgia claims practice, serving policyholders statewide from Atlanta to Savannah. A licensed Georgia public adjuster (#3395391), he has handled complex hurricane, hail, tornado, wind, and fire losses, with deep experience in commercial and large-loss property. Taylor founded his own firm before joining JustClaims to scale a tech-forward approach for Georgia policyholders, pairing claims expertise with AI to drive faster, clearer, and fuller settlements. He works only for policyholders — never the insurance company — and also holds public adjuster licenses in Minnesota, Missouri, Texas, Florida, Colorado, Montana and Washington.
Georgia claim questions,
answered straight.
Georgia's Unfair Claims Settlement Practices Rule (Ga. Comp. R. & Regs. r. 120-2-52-.03) sets hard deadlines. Your insurer must acknowledge your claim within 15 days. For fire and extended-coverage losses — which include most wind, hail, and hurricane claims — it must affirm or deny coverage within 60 days of receiving your completed proof of loss, and pay within 10 days of accepting the claim. If your carrier is drifting past those windows, that pattern matters. We track every deadline from day one and use missed dates as leverage in the negotiation.
Yes. Since July 1, 2021, Georgia law caps a public adjuster's total commission at 33.3% of the insurance settlement — and the fee must be reasonable on top of that (O.C.G.A. § 33-23-43.3). One exception worth knowing: if your insurer pays, or commits in writing to pay, your policy limit within 72 hours of the loss being reported, a public adjuster can't take a percentage of that claim at all — only reasonable compensation for time and expenses. We work on contingency: no recovery, no fee. Every term is spelled out in our state-approved contract before you sign.
Use the Georgia Office of Commissioner of Insurance's free license lookup at oci.georgia.gov. Search the adjuster's name and confirm the license shows active — every legitimate Georgia public adjuster appears in that database. Taylor Bezek, our Georgia-licensed public adjuster, holds license #3395391. If someone adjusting your claim can't give you a license number that checks out, walk away.
Your policy controls the deadline, and Georgia courts enforce it. Most property policies include a suit-against-us clause that shortens the window to file — two years from the date of loss is common, and some policies run shorter. Once that window closes, even a strong claim is dead. If your claim has been dragging and the anniversary is approaching, that's the moment to get help — before the deadline, not after.
Most Georgia property policies do — but you have to read yours to be sure. Appraisal is a built-in process for disputes over the amount of a loss: each side hires an appraiser, and the two appraisers select an umpire. It's usually faster and cheaper than litigation. The catch: appraisal decides price, not coverage. If the carrier says your damage isn't covered at all, appraisal won't settle that. We look at your policy and tell you which fight you're actually in — and whether appraisal or negotiation gets you further.
It depends on your policy. Coastal Georgia policies often carry a separate wind or named-storm deductible — frequently a percentage of your dwelling coverage (typically 1–5%) instead of a flat dollar amount. Whether it was triggered for a given storm, and how it was applied, comes straight from your declarations page and the policy's windstorm language. We review your policy first, confirm which deductible actually applies, and make sure the carrier isn't stacking deductibles it can't justify.
Patch-only estimates are one of the most common underpayment patterns after Georgia hail events. If hail bruised shingles across the roof — or if your shingle is discontinued and no reasonable match exists — a patch may not restore the roof to pre-loss condition, which is what your policy owes. We document the full extent of the damage slope by slope, bring an independent scope, and push the carrier from a patch price to the replacement the damage actually requires.
Usually not under a single policy. Your farmhouse typically sits on a homeowners or dwelling policy, while poultry houses, barns, equipment, and livestock sit on separate farm or commercial policies — sometimes with different carriers entirely. After a tornado, that means running several claims at once, each with its own deadlines, deductibles, and adjusters. We manage the whole loss as one project so nothing falls between policies and every structure gets scoped and claimed.
A standard homeowners policy generally covers sudden water damage from a burst pipe — tear-out, drying, and repair of damaged floors, walls, cabinets, and your belongings. What it usually does not cover is the pipe repair itself, or long-term seepage the carrier argues you should have caught earlier. The real fight is usually scope: carriers price the visible damage and skip the moisture trapped in walls and subfloors. We document the full water path with moisture mapping and hold the estimate to it.
In most cases, no. Many Helene claims across Georgia are still being supplemented as hidden damage surfaces — roof systems, water intrusion, mold, code-required upgrades. If your claim is still open, we can step in and take over the negotiation now. If it was paid but came up short, you can almost always file a supplemental claim for the difference. The hard limit is your policy's suit-against-us deadline, so the sooner we review the file, the more room we have to work.
Often, yes. If you signed a full release, reopening is hard — but most claim payments aren't releases. A check marked "final payment" in an adjuster's letter usually doesn't close anything, and new damage that traces back to the original loss can support a supplemental claim. What matters is the exact paperwork you signed and your policy's limitation period. We review the claim file and tell you straight whether there's room to reopen.
More than it may think. Master-policy claims are commercial claims: the association can demand a detailed estimate breakdown, invoke appraisal if the policy allows it, and hire its own public adjuster to re-scope the loss. Underpaid clubhouse, roof, and amenity claims are common after Georgia storms because carriers scope them like simple repairs. We represent associations directly — document the full damage, price it correctly, and negotiate with the carrier so the board isn't funding storm repairs out of reserves.
Get a Georgia adjuster on your side.
It only takes a few minutes to request a free review of your Georgia claim. No recovery, no fee.
Licensed Georgia public adjuster · No recovery, no fee