Underpaid or denied claims
We reopen and re-document claims the carrier low-balled or denied, then fight for the full policy value.
Seattle's rain, windstorms, and aging housing stock are hard on roofs, pipes, and interiors. When the carrier underpays, delays, or denies your water, fire, or wind claim, our public adjusters step in. We document the full loss independently — before any contractor estimate goes to the insurer.
 No upfront cost. We only get paid when you recover.
Residential, commercial & condo claims across the Seattle metro.
Licensed public adjusters serving Washington State.
We only get paid when you do.
Tell us about your property and damage. We'll review at no cost.
No upfront cost. We only get paid if you recover. Licensed Washington public adjusters.
Results vary by claim. Figures reflect JustClaims claim experience.
From craftsman homes and Capitol Hill condos to commercial buildings and HOA communities, we represent policyholders — never the insurance company.
Master-policy gaps, unit-vs-association disputes, and upstairs-neighbor leaks — scoped so nothing falls between policies.
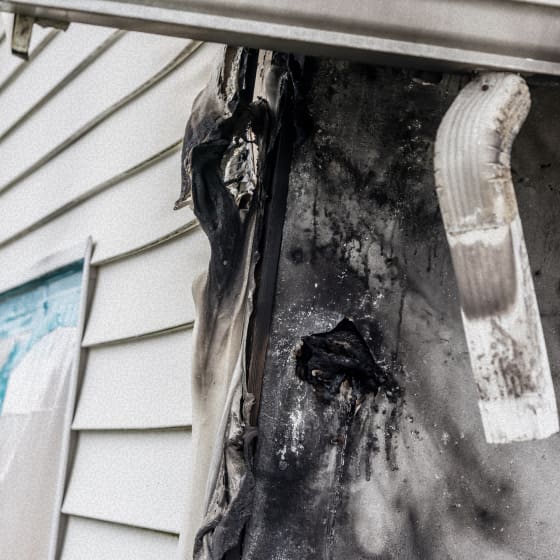
Structure fires, smoke, and soot damage — scoped for full repair and cleaning, not carrier minimums.
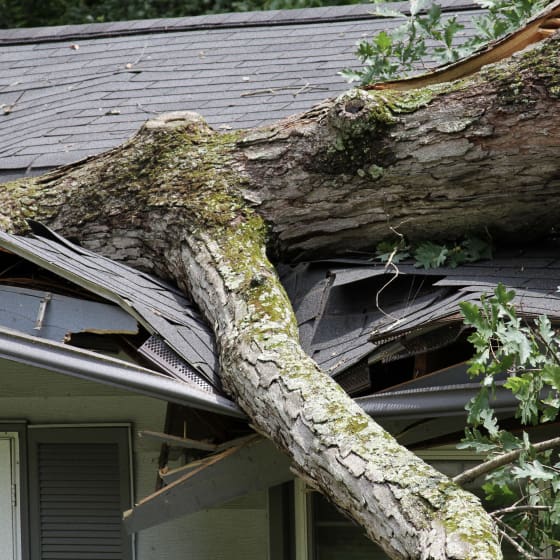
Roof lift, siding damage, and tree impact from Puget Sound windstorms — the full envelope, not a spot patch.
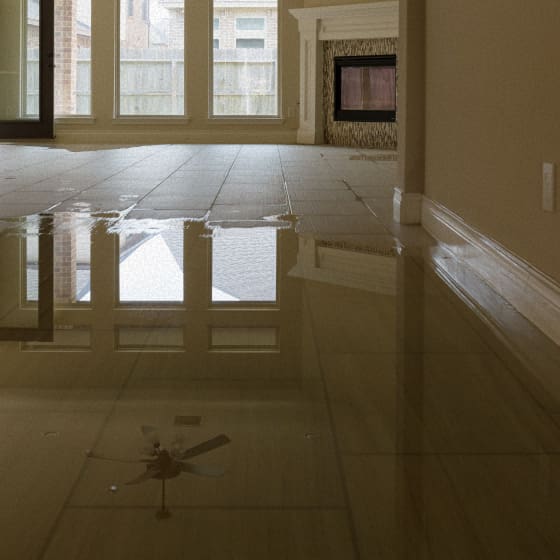
Wind-driven rain, roof leaks, and hidden moisture — documented before the carrier calls it maintenance.
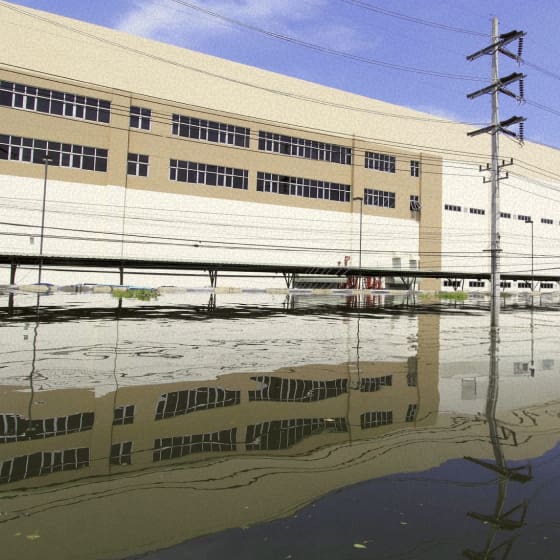
Backed-up drains and sump overflows — messy losses carriers love to exclude, documented line by line.
Rental dwellings, tenant-caused damage, and lost rents — claims handled for Seattle's investor owners.
Carrier estimate far below the contractor's bid
Storm damage written off as a 'long-term leak' or 'cleaning-only'
Weeks of silence or repeated requests for the same documents
An offer that won't cover current Seattle labor and material costs
The carrier's first number is rarely its best. Here's how we level it.
Tell us what happened to your property. We review the policy and the damage at no cost — and tell you straight whether hiring a public adjuster is worth it.
Start your free claim review →
We inspect, photograph, and scope every line item — moisture readings, code upgrades, contents — then present a complete, evidence-backed claim to your insurer.
Start your free claim review →
We handle the back-and-forth with the carrier and push for the full amount your policy owes. You pay nothing unless we recover.
Start your free claim review →We represent policyholders only. From first inspection to final settlement, we handle the claim so you can focus on your home or business.
We reopen and re-document claims the carrier low-balled or denied, then fight for the full policy value.
We find the damage the carrier's adjuster missed — hidden moisture, smoke in HVAC, code upgrades — and put it in writing.
We handle all insurer communication and negotiation, and we don't get paid unless you recover.
Single-family homes
Condos & townhomes
HOA communities
Apartment & multi-family buildings
Retail & office
Restaurants & hospitality
Warehouses & industrial
Craftsman & older homes
Washington regulates how insurers handle your claim — how fast they must respond, how they must decide, and who may represent you. Here is what matters for a Seattle claim.
Under WAC 284-30-360, your insurer must acknowledge your claim — and answer your later communications — within 10 working days.
Under WAC 284-30-380, the carrier must accept or deny your claim within 15 working days of your completed proof of loss, and a denial must cite the exact policy provision it relies on.
Washington licenses public adjusters through the Office of the Insurance Commissioner under RCW 48.17. Verify the license before you sign — ours is WA Public Adjuster #1375243.
You can file a complaint with the Washington OIC, which can require the insurer to respond. Most policies also carry an appraisal clause for amount-of-loss disputes — a contractual option we use when it helps.
This page is general information, not legal advice. Your policy terms and current statutes control.
We represent policyholders across the Seattle metro and the surrounding Puget Sound communities, from the Eastside to the South Sound.
Roofers, restoration crews, and general contractors across the Puget Sound trust us to get their customers' claims paid fully and fairly.

We handle the insurance paperwork and negotiation so your scope of work gets approved and funded.
Water, fire, and smoke mitigation claims documented correctly from day one — fewer disputes, faster payment.
Wind, rain, and tree-impact roofing claims scoped to full replacement where the policy allows.

Taylor Bezek has spent more than a decade representing policyholders on residential, commercial, and large-loss property claims. He personally worked close to 1,500 claims in Colorado, where he built his adjusting career, and now leads multi-state claims operations for JustClaims — including Washington, which he serves from our Spokane office. He holds a Master's in International Security with a Certificate in Homeland Security from the University of Denver. On Seattle files, that means knowing how carriers frame water and wind losses in older housing stock — and having the documentation that answers it ready before the denial letter arrives.
We work on contingency: our fee is a percentage of the settlement we recover for you, with no upfront cost. You get a free claim review first, and the exact fee terms are in the written agreement before you sign anything.
Usually more than one policy is involved. The association's master policy typically covers the building structure, your HO-6 unit policy covers interior finishes and belongings, and the upstairs owner's liability coverage can apply if they were negligent. Carriers routinely point at each other — we determine which policy responds first and document the claim accordingly.
No. Standard homeowners policies exclude earth movement, including earthquake. You need a separate earthquake policy or an endorsement. One important exception: fire caused by an earthquake is covered under a standard policy, and those claims still require careful documentation.
Usually not under a standard policy. Water that enters from outside at ground level is treated as flood, which requires separate flood insurance. But wind-driven rain through a storm-damaged opening, or a sewer backup with the right endorsement, can be covered — the cause of entry decides it, which is exactly what we document.
Carriers classify slow leaks and seepage as excluded maintenance, while sudden and accidental discharge is covered — the fight is over cause and timeline. A denial must cite the specific policy provision it relies on (WAC 284-30-380), and moisture readings, plumber reports, and expert review can rebut a 'gradual' label. Many of these denials are worth challenging.
Yes, in most cases. An underpaid claim can be supplemented with new documentation, and we can reopen negotiations or invoke your policy's appraisal clause. Your policy's suit-against-us clause sets the final deadline, so the earlier you act, the more options you keep.
Free claim review. No upfront cost. We only get paid when you do.
Licensed public adjusters serving Seattle and western Washington.