Wildfire & Smoke
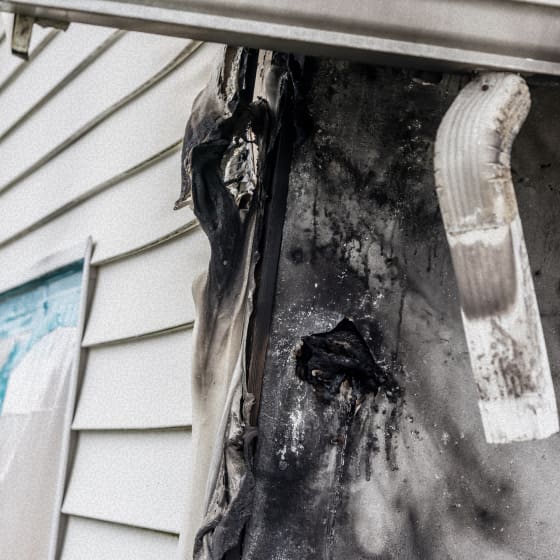
Eastern WA wildfires don't have to burn your home to cost you. Smoke, ash, and soot damage to roofing, siding, and HVAC is real, documentable damage — and it's routinely under-scoped.
Eastern Washington's wildfire seasons and hard freeze-thaw winters hit Spokane roofs, pipes, and HVAC systems every year. When the carrier underpays, delays, or denies your wildfire, water, or wind claim, our public adjusters step in. We document the full loss independently — before any contractor estimate goes to the insurer.
 No upfront cost. We only get paid when you recover.
Residential, commercial & HOA claims across the Spokane metro.
Licensed public adjusters serving Washington State.
We only get paid when you do.
Tell us about your property and damage. We'll review at no cost.
No upfront cost. We only get paid if you recover. Licensed Washington public adjusters.
Spokane's claim calendar runs on wildfire season and hard winter freezes. These are the losses we see most — and the ones carriers most often underpay.
Eastern WA wildfires don't have to burn your home to cost you. Smoke, ash, and soot damage to roofing, siding, and HVAC is real, documentable damage — and it's routinely under-scoped.
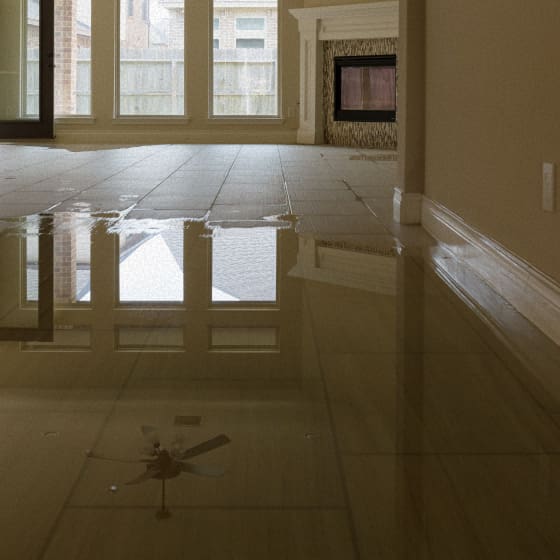
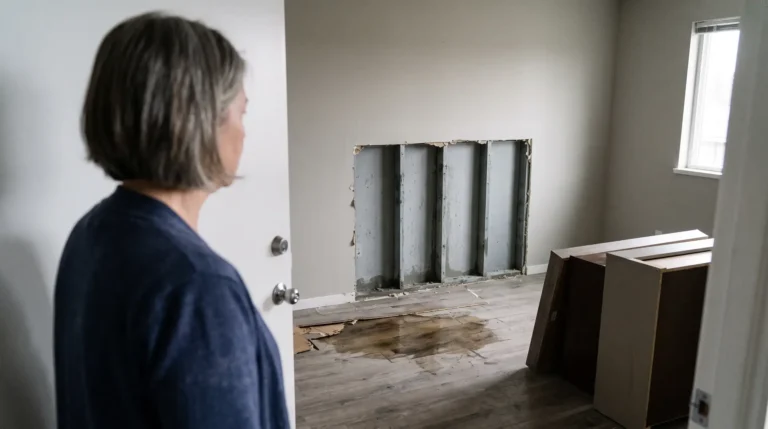
Spokane's freeze-thaw winters drive ice dams and burst pipes. Carriers often reframe sudden water damage as a maintenance or seepage problem to limit the payout. We push back with documentation.
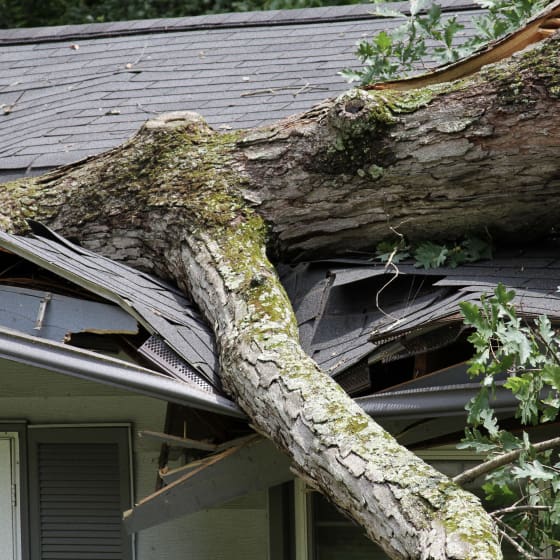
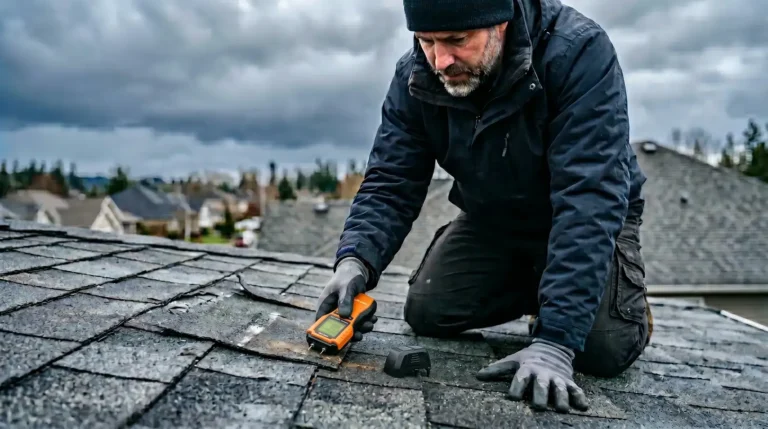
High winds off the Palouse strip shingles, topple trees, and drive rain under roofing and siding. We scope the full wind and water-intrusion loss, not just the obvious shingle count.
From single-family homes to commercial buildings and HOA communities, we represent policyholders — never the insurance company.
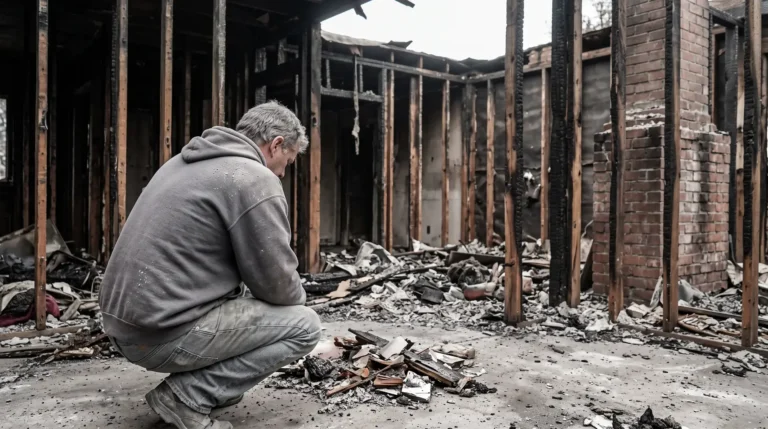
Structure fires, wildfire smoke, and ash damage — scoped for full repair and cleaning, not carrier minimums.
Learn more →
Burst pipes, ice dams, and sudden water discharge — documented before the carrier calls it neglect.
Learn more →
Roof lift, siding, and wind-driven rain intrusion — the full envelope, not a spot patch.
Learn more →
Business property and lost income claims for Spokane's commercial and mixed-use buildings.
Learn more →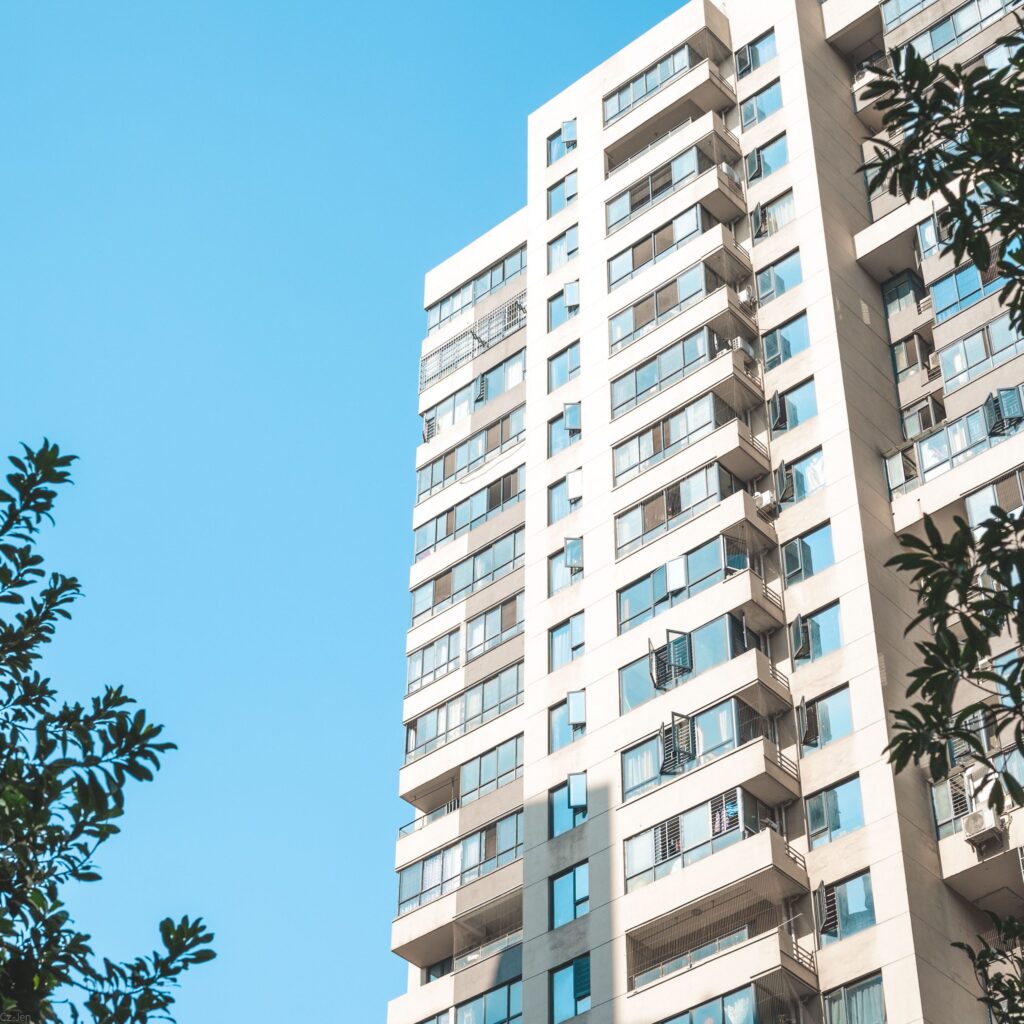
Association and unit-owner claims — master-policy gaps, loss assessment, and shared-structure damage.
Learn more →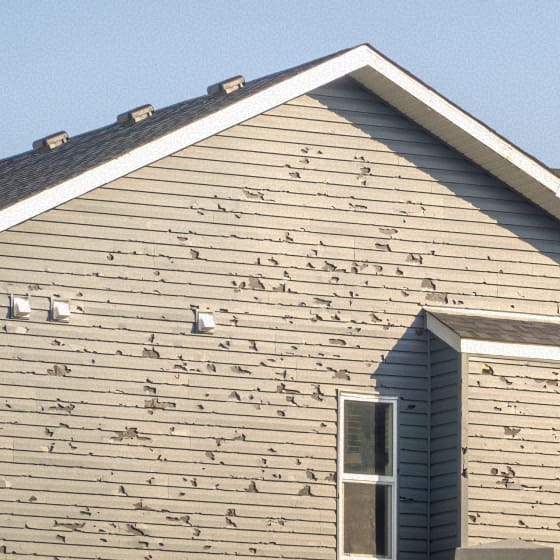
Hail, snow-load, and storm damage — scoped to full replacement where the policy allows.
Learn more →You don't have to take the carrier's first number. Here's how we level it.
Tell us what happened. We review your policy and damage at no cost and tell you honestly whether a public adjuster adds value.
Start your free claim review →
We inspect, photograph, and scope every line item — then present a complete, evidence-backed claim to your insurer.
Start your free claim review →
We handle the back-and-forth and push for the full amount your policy owes. You only pay when you recover.
Start your free claim review →
Carrier estimate came in far below the contractor's bid
Claim blamed on "wear and tear," "maintenance," or "seepage"
Smoke or water damage scoped as cleaning-only instead of repair
Weeks of silence or repeated requests for the same documents
Settlement that won't cover code-required repairs
We represent policyholders only. From first inspection to final settlement, we handle the claim so you can focus on the property.
We reopen and re-document claims the carrier low-balled or denied, and we fight for the full policy value.
See how we reopen claims →We find the damage the carrier's adjuster missed — hidden water, smoke in HVAC, code upgrades — and put it in writing.
See what we document →We handle all insurer communication and negotiation, and we don't get paid unless you recover.
See how negotiation works →
Single-family homes
Condominiums & townhomes
HOA communities
Apartment buildings
Retail & office
Restaurants & hospitality
Warehouses & industrial
Historic & older homes
Washington regulates how insurers handle your claim. Here's what the rules require — and where a public adjuster in Washington State changes the outcome.
Under WAC 284-30-360, your insurer must acknowledge your claim within 10 working days and answer your follow-up communications within 10 working days.
Under WAC 284-30-380, the insurer must accept or deny your claim within 15 working days of your completed proof of loss, and any denial must cite the specific policy provision it relies on.
Washington requires public adjusters to be licensed by the Office of the Insurance Commissioner under RCW 48.17 before representing you for compensation. Always verify a license before you sign.
You can file a complaint with the Washington OIC, which can require the insurer to respond. Many policies also include an appraisal clause for amount-of-loss disputes — a policy provision, not an automatic right.
This page is for general information only and is not legal advice. Policy terms and current statutes control.
We represent policyholders across the Spokane metro and the surrounding Eastern Washington communities.
Roofers, restoration, and general contractors trust us to get their customers' claims paid fully and fairly.

We handle the insurance paperwork and negotiation so your scope of work gets approved and funded.
Water, fire, and smoke mitigation claims documented correctly from day one — fewer disputes, faster payment.
Hail, wind, and ice-dam roofing claims scoped to full replacement where the policy allows.

Taylor Bezek has spent over a decade representing policyholders on residential, commercial, and large-loss property claims. He built his public adjusting career in Colorado, where he personally worked close to 1,500 claims, and now leads claims operations for JustClaims across multiple states, including Washington. He holds a Master's in International Security with a Certificate in Homeland Security from the University of Denver. On Washington files, that experience shows up as knowing which argument a carrier will reach for first — wear and tear, maintenance, seepage — and having the documentation that answers it ready before the letter arrives.
Most homeowners policies include Additional Living Expense (ALE or "loss of use") coverage, which pays for temporary housing, meals, and related costs while your home is being repaired after a covered loss. The fight is usually over how much and for how long. We document the full displacement cost and push the carrier to honor the policy limit.
Sudden collapse from the weight of snow or ice is typically a covered peril. Carriers sometimes argue the roof was already deteriorated to avoid paying. The distinction between a sudden collapse and gradual deterioration is exactly what we document — age of the roof, prior condition, and the triggering weather event.
Not automatically. A "maintenance" or "neglect" label is a conclusion the carrier has to support, not a free pass. Ice dam water damage is often sudden and accidental even when the dam itself formed over time. We gather the evidence — weather data, moisture mapping, photos — to challenge an unsupported maintenance denial.
Wind-driven rain that enters through a wind-created opening is generally covered, and the resulting interior water damage is part of that loss. Disputes arise when carriers claim the opening pre-existed or the water entered through normal wear. We scope both the wind damage and the interior water intrusion as one documented claim.
Only if your policy includes ordinance-or-law coverage, which pays the extra cost to bring damaged work up to current building code. Many older Spokane homes trigger code requirements during repair. We review your policy for this coverage and document which upgrades are code-required versus elective.
Generally yes — when a tree falls because of a covered peril like wind or the weight of snow, most policies cover both removal of the tree from the structure and repair of the damage it caused, though removal coverage often has a sub-limit. We document the cause of the fall and the full repair scope so nothing is left out.
Free claim review. No upfront cost. We only get paid when you do.
Licensed public adjusters serving Spokane and Eastern Washington.