Hurricane & wind damage
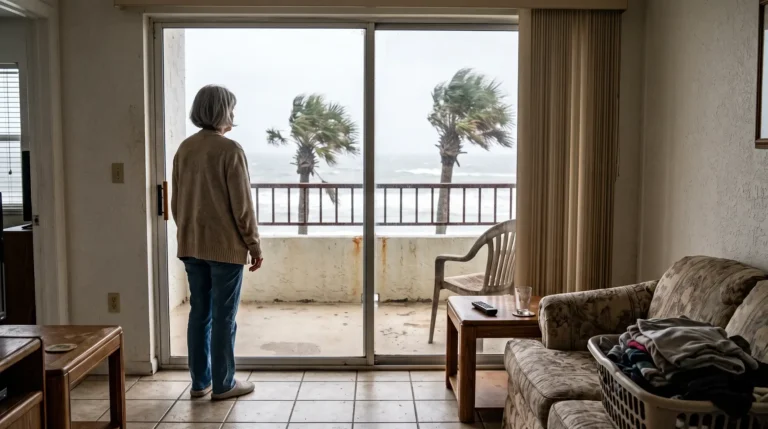
Roof, building envelope, windows, and structural damage from named storms. We scope the full loss before the carrier's adjuster writes a partial one.
When the carrier underpays, delays, or denies your hurricane, wind, or water claim, our licensed Miami public adjusters step in — documenting the full loss independently, before the carrier's scope sets the number.
 No upfront cost. We only get paid when you recover.
Commercial, condo, HOA & homeowner claims across Miami-Dade.
Licensed by the Florida Department of Financial Services.
We only get paid when you do.
Tell us about your property and damage. We'll review at no cost.
No upfront cost. We only get paid if you recover. Licensed Florida public adjusters.
Three steps, no upfront cost, and a licensed Florida public adjuster handling the carrier from start to finish.
First you tell us about your property and the damage. We review your policy and the loss at no cost, and identify what the carrier's scope missed.
Start your free claim review →
Next we assign a Florida-licensed public adjuster who knows Miami hurricane, water, and condo claims. We document the full scope, price the real cost of repair, and negotiate directly with the carrier. You never have to fight the insurer alone.
Start your free claim review →
Last, we drive your claim to resolution. There is no upfront cost. We only get paid if we recover money for you. Simple, fast, win-win.
Start your free claim review →From Brickell office towers to Miami Beach condos and Kendall homes, hurricane and wind to water and fire, we cover the full range of Miami insurance claims.
Brickell and Downtown office towers, retail along Flagler Street and Calle Ocho, and hospitality from Miami Beach to the airport corridor. As a commercial public adjuster in Miami, we manage the entire claim, start to finish.
High-rise associations from Edgewater to Sunny Isles and suburban HOAs across the county. We separate master-policy scope from unit-owner HO-6 coverage, document every building, and coordinate directly with your board.
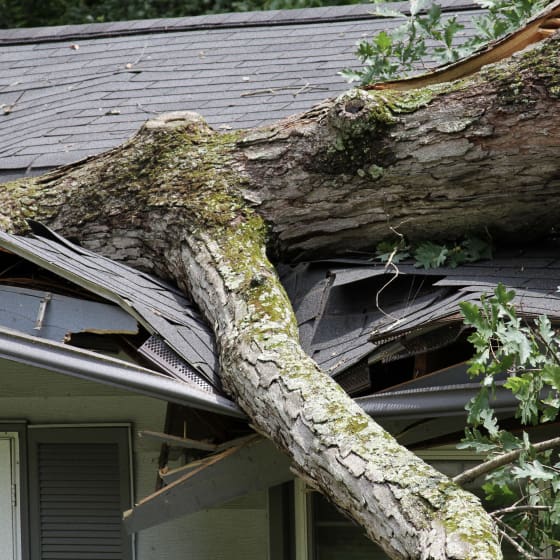
Roof, envelope, and interior damage from hurricanes and tropical storms, plus the wind-driven rain intrusion carriers try to exclude. The claim type Miami knows best, and the one carriers fight hardest.
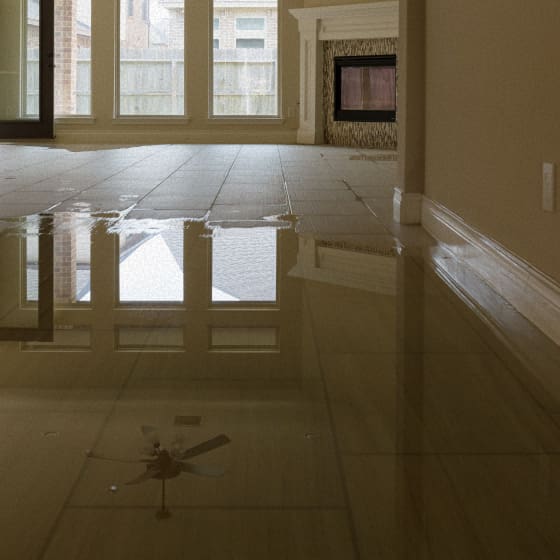
Burst pipes, AC and appliance leaks, and roof leaks the carrier tries to classify as maintenance or long-term seepage rather than a sudden covered loss.
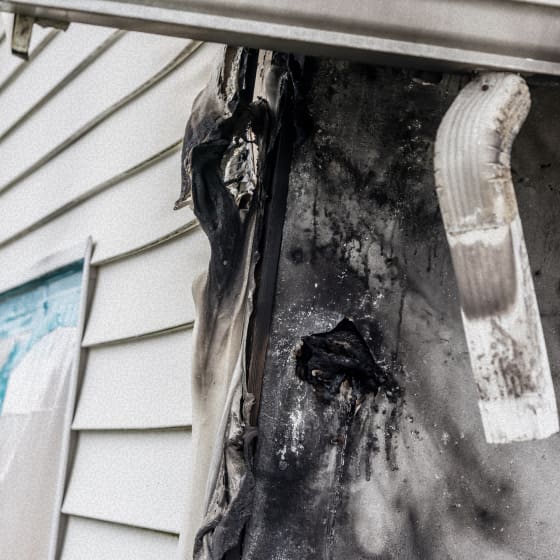
Structure fire, smoke and soot, equipment loss, and business-interruption components across Miami-Dade's dense commercial and residential stock.

Claims the carrier denied or lowballed. We reopen the file, re-document what the inspection missed, and press for the full value your policy owes.
We document the full scope independently, before the contractor estimate goes to the insurer
We specialize in commercial, condo, and HOA property with complex policies
We work exclusively for policyholders, never for insurance companies
From roof and envelope damage to business interruption, hurricane claims are the largest and most disputed losses in Florida. We build the documentation that holds up.
Roof, building envelope, windows, and structural damage from named storms. We scope the full loss before the carrier's adjuster writes a partial one.

Interior damage the carrier tries to exclude as seepage or maintenance. We tie the intrusion path back to the storm event.

Lost revenue for commercial owners and additional living expenses for residents while repairs drag on. We document and price the time-element loss.
The carrier's playbook on Miami claims is to pay less than you're owed, drag out the timeline, or deny the claim outright. We fight all three.
The carrier pays, but far less than the damage actually costs to repair, and the hurricane deductible makes the gap look smaller than it is. We document the full scope independently and push the settlement to where it should be.
Weeks turn into months while the carrier stalls and buries you in requests. We take over the process and hold them to Florida's statutory claim deadlines.
A denial is not the end. We reopen the claim, re-document what was missed, and fight to overturn it, with the DFS complaint process as a backstop.
Office Buildings
Retail & Restaurants
Industrial & Warehouse
Hospitality & Lodging
Healthcare Facilities
Condo & Multi-Family
Self-Storage
REITs & Funds
Free review. Miami experts. No upfront cost.
Florida law gives property owners more leverage than most carriers let on. Here's the background that matters for a Miami claim. This is general information, not legal advice.
Anyone working your Miami claim as a public adjuster must be licensed by the Florida Department of Financial Services. You can verify any adjuster before you sign. JustClaims is a licensed Florida public adjuster representing Miami property owners.
Florida law caps public adjuster fees at 20% of the claim payment, and at 10% for claims arising from a declared state of emergency when the adjuster is engaged within the first year after the declaration. JustClaims works on contingency, with no upfront cost. No recovery, no fee.
You have one year from the date of loss to notify the insurer of a new claim, and 18 months for a supplemental claim. Miss the window and the claim can be barred. We calendar every deadline from day one.
Your insurer must acknowledge your claim within 7 calendar days and pay or deny within 60 days of receiving notice, unless factors beyond its control apply. We hold them to the clock.
JustClaims provides public adjusting services, not legal advice. For legal questions, consult a licensed Florida attorney.
Contractors are some of our best partners. We quarterback the insurance side, keep you in the loop, and never cut you out. Under Florida law, contractors can't negotiate the claim, so a licensed public adjuster is the compliant way to get your scope approved and paid.
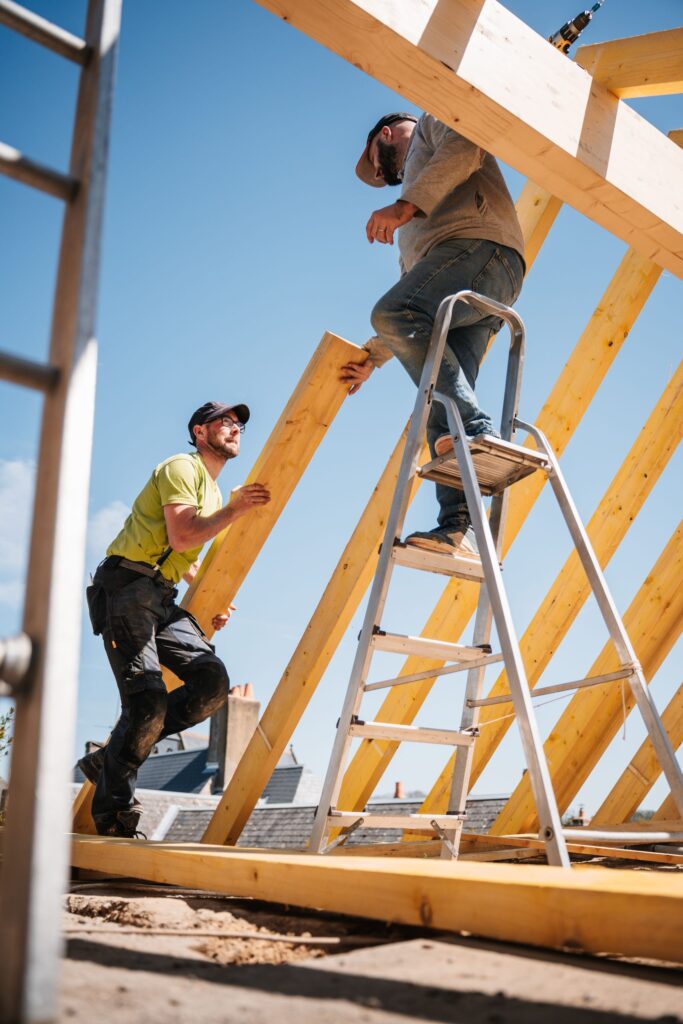
Commercial and residential roofers and storm-restoration crews across Miami-Dade.
Water mitigation, fire and smoke restoration, mold remediation, and disaster recovery firms.

Commercial builders, condo and multi-family renovation firms, and large-loss rebuild specialists.
We handle claims from Miami Beach and Coral Gables to Hialeah, Kendall, Doral, Aventura, and Homestead, spanning all of Miami-Dade County, and we also serve greater South Florida across Broward and Palm Beach counties.
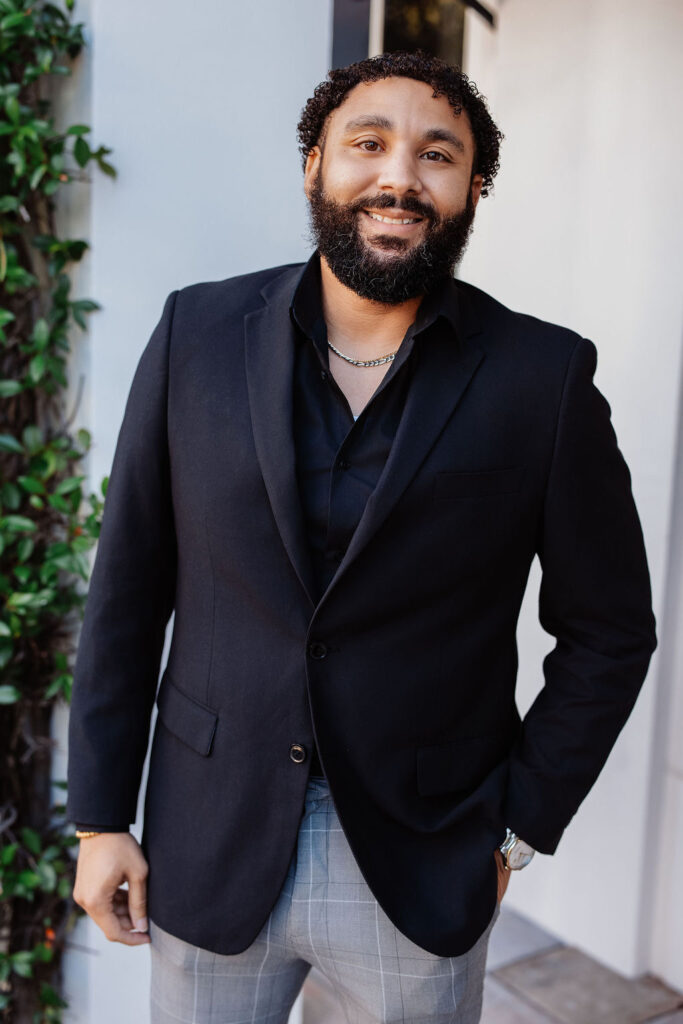
A seasoned insurance professional with nearly a decade of experience, Stephane Elias is currently serving as a Senior Claims Professional and Public Adjuster with JustClaims. Throughout his career, Stephane has represented policyholders through leading public adjusting firms and served as a loss consultant for law firms specializing in insurance litigation, giving him extensive expertise in complex property insurance claims.
A licensed public adjuster in FL (#W564547), TX (#2645032), and six other states, he specializes in commercial and residential property claims, claims management, appraisals, mediation, and strategic partnerships. Stephane is passionate about helping policyholders overcome delayed, denied, and underpaid insurance claims, ensuring they receive the full recovery they're entitled to under their policy.
Florida policies carry a separate hurricane deductible, most often a percentage of the dwelling coverage limit such as 2%, 5%, or 10%, applied once per calendar year to hurricane losses. On top of that, carriers often apply depreciation and leave scope out of the estimate. We document the full loss independently so the deductible and depreciation are applied to the real number, not a reduced one.
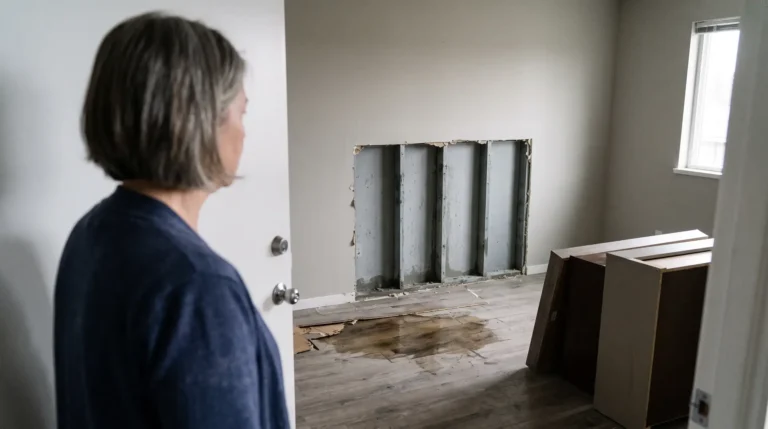
Interior damage that follows from storm-created openings is usually part of the same covered loss, not a separate maintenance issue. Carriers often accept the roof scope and carve out the interior. We trace the intrusion path — moisture mapping, storm-track data, and the physical breach — and tie the interior damage back to the covered event in the documented scope.
We represent the association on the master-policy claim: documenting common elements and building-wide scope, separating master-policy coverage from unit-owner HO-6 coverage, coordinating with the board, and negotiating directly with the carrier. Condo claims are among the most disputed in Miami, and independent documentation is what moves them.
Yes. Citizens Property Insurance is Florida's state-backed insurer of last resort, and Citizens policyholders have the same right to hire a licensed public adjuster as any other Florida policyholder. The same claim deadlines and fee caps apply, and the process works the same way as with any other Florida carrier.
Florida law requires the carrier to acknowledge your claim within 7 calendar days and pay or deny within 60 days of receiving notice, unless factors beyond its control apply. Past that window, the escalation levers are a formal demand, a DFS consumer complaint, and the appraisal process most Florida policies include. We use all three, and we take over the documentation and follow-up so the file stops stalling.
No. Florida law puts the carrier on a statutory clock: acknowledge your claim within 7 calendar days, and pay or deny within 60 days of receiving notice, unless factors beyond its control apply. We manage the file, keep it moving, and hold the carrier to every deadline.
It only takes a few minutes. No upfront cost. We only get paid when you do.
Licensed by the Florida Department of Financial Services · Contingency fee, capped by Florida law · Serving Miami & all of Miami-Dade County