Introducing Justin: Built for property owners - analyze your insurance policy in under 10 minutes. Always free. Analyze your policy now →

Denver Public Adjusters for Hail & Storm Claims

Denver sits in Hail Alley, one of the most storm-battered corridors in the country. When the carrier underpays, delays, or denies your hail, storm, wind, or wildfire smoke claim, a Denver public adjuster steps in. We handle commercial and homeowner claims — and negotiate directly with the carrier to get your policy honored.

  • No upfront cost. We only get paid when you recover.
  • Commercial and homeowner claims — including HOA and multi-family.
  • 100+ combined years of public adjusting experience.

We only get paid when you do.

Get a Free Claim Review

Tell us about your property and damage. We'll review at no cost.

    No upfront cost. We only get paid if you recover. Licensed Colorado public adjuster #769172.

    $50M+
    Recovered for property owners
    100+
    Combined years of experience
    3x
    Average increase over initial offer
    $0
    Zero upfront cost

    Results vary by claim. Figures reflect JustClaims claim experience.

    What Denver property owners say

    Real results. Real recovery.

    Their insurer offered just $71,000 for widespread hail damage across 26 buildings. Taylor took over the claim and recovered $2.3 million for the association, more than 30x the original offer.

    Denver multi-family townhome association (26 buildings)

    $2.3M Denver Hail Claim (26 Buildings)
    This 226-unit, 12-building complex brought Taylor in at the very start after a 2-inch hail storm, the right move on complex commercial claims. The result was a $2.2 million settlement in just five months.

    Fort Collins condo association (226 units, 12 buildings)

    $2.2M Fort Collins Hail Claim (226 Units)
    By engaging Taylor early in the claim process, this 15-building condo community secured a $760,000 recovery for hail storm damage.

    Castle Rock condo community (15 buildings)

    $760K Castle Rock Hail Claim (15 Buildings)

    Results vary. Every claim is different.

    How it works

    Unsure about public adjusting? Here's a real example.

    Using an actual Denver hail claim that went from $28,000 to $320,000 once JustClaims got involved.

    contractors-howitworks-01
    Step 1

    Share your claim details

    First you tell us about your property and the damage. In this example, a spring hailstorm shredded the roof on a commercial building and the carrier offered just $28,000. We reviewed the policy and damage at no cost and found everything they missed. It didn't take long.

    Start your free claim review →
    contractors-howitworks-02
    Step 2

    Your JustClaims expert takes over

    Next we assign a dedicated public adjuster who is an expert in Denver claims. In this case, our lead public adjuster, Taylor, documented the full roof damage, priced the real replacement and negotiated with the carrier. The owner slept easier at night knowing we were quarterbacking.

    Start your free claim review →
    contractors-howitworks-03
    Step 3

    Get paid what you're owed

    Last, we drive your claim to resolution. This owner went from a $28,000 carrier offer to a $320,000 recovery, enough to fully replace the roof. There was no upfront cost. We only get paid if we recover money for you. Simple, fast, win-win.

    Start your free claim review →
    Denver insurance claim types

    We handle every type of Denver property damage claim.

    From commercial buildings to homes, hail and storm to fire and smoke, we cover the full range of Denver insurance claims, including dedicated homeowner insurance claim help.

    Commercial property claims

    Flat-roof systems, HVAC, and large-hail losses on office, retail, industrial, and multi-family buildings across the Denver metro and Tech Center corridor. As a commercial public adjuster in Denver, we manage the entire commercial insurance claim, start to finish.

    Learn more →

    HOA & condo claims

    Master policy vs. unit-owner coverage overlap in communities like Cherry Creek, Highlands Ranch, and Central Park. We sort out who pays for what so nothing falls through the gap.

    Hail damage claims

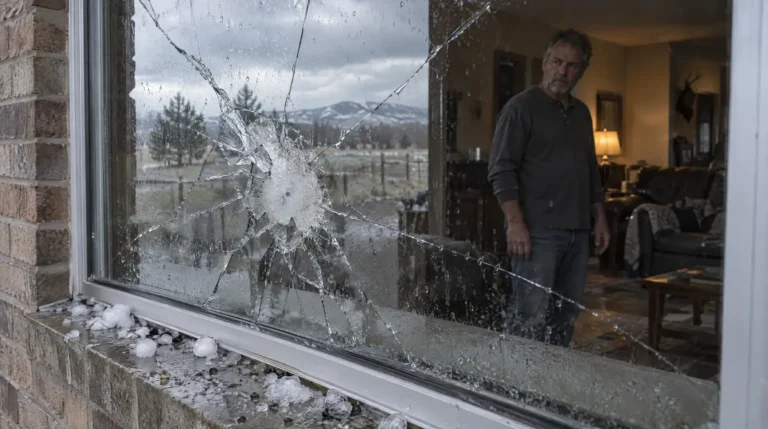
    Roof, siding, window, and exterior damage from Denver's frequent hail cycles. The most common, and most underpaid, claim type on the Front Range.

    Learn more →

    Storm & wind damage

    Wind-driven roof damage, exterior structures, fences, detached garages, and storm-related losses throughout the Denver metro.

    Learn more →

    Fire & wildfire claims

    Fire, smoke, and wildfire losses — structural damage, smoke infiltration, and ash residue that carriers often miss on the first pass.

    Learn more →

    Water & freeze

    Burst pipes, ice dams, and freeze events cause hidden damage that carriers often underpay. We document the full scope before the carrier sets the number.

    Reality of Denver Claims

    Why Denver hail claims get underpaid.

    Denver sits in the heart of Hail Alley. Hail season runs roughly May through September, and the I-25/I-70 corridors take repeated hits — on top of wind, wildfire smoke, and freeze-thaw damage. The #2 ranking comes from RMIIA/NICB data, and it shows in how carriers scope losses: granule loss, denting, and cracked shingles that justify full replacement can get written off as cosmetic.

    Denver is also an HOA-heavy market. In Cherry Creek, Highlands Ranch, and Central Park, master policies and unit-owner HO-6 coverage can leave gaps that get missed. We sort out who pays for what — and document the difference between hail damage and wear.
    • Licensed Colorado public adjuster (#769172)
    • Denver Building Code + IRC/IBC expertise
    • Commercial, HOA, and multi-family claims
    • We work only for policyholders — never carriers
    Denver Storm Risk

    Denver's hail and storm risk,
    and why it matters for your claim.

    Denver faces more hail than almost anywhere in the country, plus wind and wildfire smoke. The more routine these losses get, the more carriers lean on volume to underpay them. Documentation is what changes that.

    Storm Hail

    Hail, every season

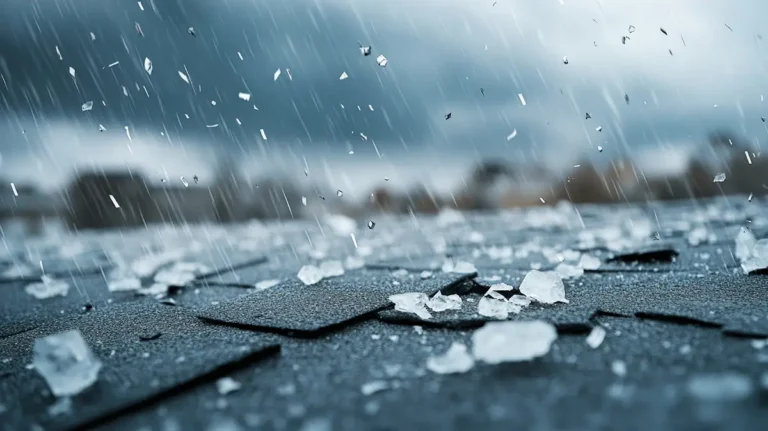
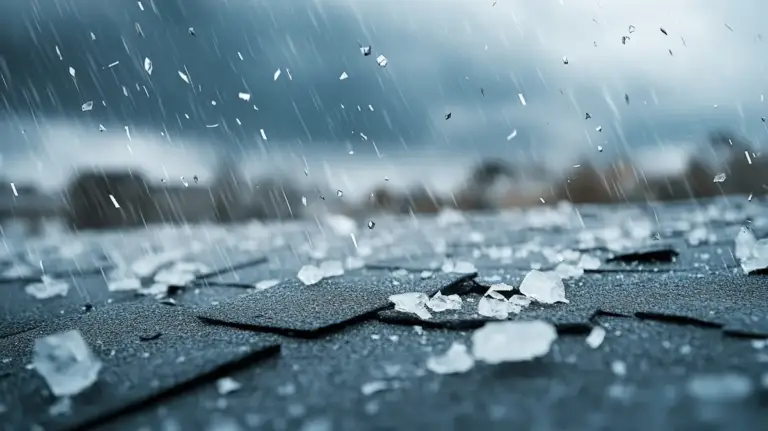
    Denver's hail season runs roughly May through September, and the I-25 and I-70 corridors sit in one of the most hail-active zones in the country. Repeated cycles leave roofs with accumulated damage that carriers often dismiss as old or cosmetic rather than storm related. Documenting which damage is hail, and which is wear, is where claims are won or lost.
    Wildfire smoke and ash

    Wildfire smoke and ash

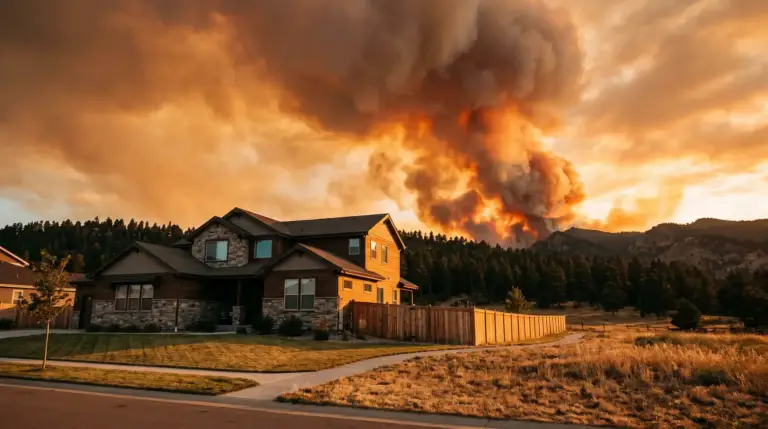
    Properties near the Jefferson County foothills, western Aurora, and the wildland-urban interface face smoke and ash exposure even when flames never reach the building. Smoke infiltration and soot residue are real losses that may be covered — and they are frequently overlooked on the carrier's first pass because the structure looks untouched.

    Wind and Chinook events

    Wind and Chinook events

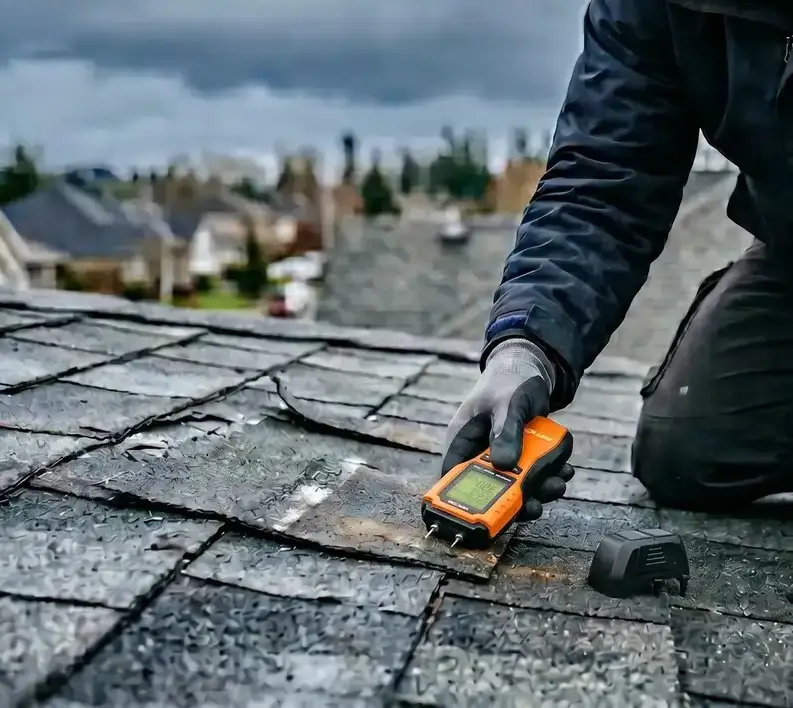
    Strong downslope Chinook winds off the Rockies can lift shingles, tear at exteriors, and drive debris across Denver's western suburbs. Because wind damage is less obvious than a caved roof, it is easy for a carrier to understate without a fully documented scope of the loss.

    Ways We Can Help

    Common carrier tactics on Denver claims: pay less than the policy owes, slow the timeline, or deny outright. Our team has 100+ combined years of adjusting experience, and we fight all three.

    Did they underpay your claim?

    The carrier pays, but far less than the damage actually costs to repair. We document the full scope and push the settlement to where it should be.

    Learn more →

    Is your claim stuck or delayed?

    Weeks turn into months while the carrier stalls and buries you in requests. We take over the process, escalate to the right supervisor, and hold them to claim-handling deadlines.

    Learn more →

    Was your claim denied outright?

    The carrier says no. A denial is not the end. We reopen the claim, re-document what was missed, and fight to overturn it.

    Learn more →

    We have expertise on all building types:

    • Office Buildings
    • Retail & Restaurants
    • Industrial & Warehouse
    • Hospitality & Lodging
    • Healthcare Facilities
    • Multi-Family
    • Religious & Community
    • REITs & Funds

    See what your insurance claim is really worth.

    Get a Free Claim Review

    Free review. Denver experts. No upfront cost.

    Colorado Insurance Law

    What Denver policyholders need to know.

    Colorado law gives property owners more leverage than most carriers let on. Here is the background that matters for a Denver claim. This is general information, not legal advice.

    01

    Public adjusters are licensed and regulated

    Anyone working your Denver claim as a public adjuster must be licensed by the Colorado Division of Insurance. That licensing is a consumer protection: you can verify any adjuster before you sign. Taylor Bezek, our Denver public adjuster, is licensed in Colorado (#769172) and represents policyholders across the Front Range. See how we handle Colorado claims.

    02

    The appraisal clause

    When a Denver hail or storm claim stalls over the amount of a loss, your policy likely has an answer. Most Colorado property policies include an appraisal clause that lets either side invoke an independent appraisal, often faster and cheaper than litigation. See how the Colorado appraisal clause process works.

    03

    Carriers must act in good faith

    If a carrier drags out or lowballs your Denver claim, Colorado law is on your side. Under C.R.S. §§ 10-3-1115 and 10-3-1116, insurers must handle first-party claims in good faith; unreasonable delay or denial can expose them to double the covered benefit plus attorney fees. We hold them to it.

    04

    You have a deadline to dispute

    A low offer on a Denver claim is not something to sit on. Your policy's "suit against us" clause can set a deadline shorter than you expect, and Colorado law adds its own limits. The sooner you act, the more options you keep.

    JustClaims provides public adjusting services, not legal advice. For legal questions, consult a licensed Colorado attorney.

    For Denver Contractors

    We actively partner with Denver roofing and restoration companies.

    Contractors are some of our best partners. We quarterback the claim, keep you in the loop, and never cut you out. Our proprietary technology gives you status updates so we're always in synch.

    Roofers

    Residential and commercial roofers, storm-restoration crews, and flat-roof and metal-roof specialists across the Denver metro.

    Restoration

    Water mitigation, fire and smoke restoration, mold remediation, and disaster recovery firms.

    General Contractors

    Commercial builders, multi-family and property renovation firms, and large-loss rebuild specialists.

    Denver metro areas we serve

    Serving property owners across the entire Denver metro.

    Our Denver team is local. We handle claims across Denver, Aurora, Lakewood, Thornton, Arvada, Westminster, Centennial, Englewood, Highlands Ranch, Parker, Castle Rock, Broomfield, Longmont, Littleton, Greenwood Village, and Cherry Hills Village, spanning Jefferson, Arapahoe, Adams, Douglas, and Boulder counties.

    That includes core Denver ZIP codes such as 80202 (Downtown), 80203 (Capitol Hill), 80206 (Cherry Creek), 80209 (Washington Park), and 80230 (Central Park), along with 80012 and 80014 (Aurora), 80228 (Lakewood), and 80401 (Golden).

    Denver Insurance claim help
    Aurora Insurance claim help
    Lakewood Insurance claim help
    Thornton Insurance claim help
    Arvada Insurance claim help
    Westminster Insurance claim help
    Centennial Insurance claim help
    Englewood Insurance claim help
    Highlands Ranch Insurance claim help
    Parker Insurance claim help
    Castle Rock Insurance claim help
    Broomfield Insurance claim help
    Longmont Insurance claim help
    Littleton Insurance claim help
    Greenwood Village Insurance claim help
    Cherry Hills Village Insurance claim help
    City Lead

    Meet our Denver General Manager

    Taylor Bezek
    Reviewed and Verified by

    Taylor Bezek

    General Manager, JustClaims

    Taylor Bezek has built the vast majority of his public adjusting career in Colorado. He lived in Denver for 11 years, started his public adjusting career there, and has personally worked close to 1,500 Colorado claims across residential, commercial, and large-loss property damage, supported by a strong professional network throughout the region. Taylor holds a Master's in International Security with a Certificate in Homeland Security from the University of Denver. As General Manager at JustClaims, he pairs that deep local experience with a tech-forward approach, using AI to improve speed, clarity, and outcomes for policyholders. He is licensed in Colorado (#769172) and a dozen other states, but Colorado remains his home base and the heart of his work.

    General Manager at JustClaims University of Denver Alum Nearly 1,500 Colorado Claims 11 Years Based in Denver Licensed CO Public Adjuster #769172

    Common Questions About Denver Public Adjusters

    A public adjuster is a state-licensed claims professional who represents you, the policyholder, rather than the insurance company. In Denver, we document the full scope of damage, interpret your policy, prepare and file the claim, and negotiate directly with your insurer so your settlement reflects what you are actually owed.

    We work on a contingency fee, which means there is no upfront cost. Our fee is a percentage of the settlement we recover for you, so we only get paid when you do. Colorado contracts include a written 72-hour right to cancel. You get a free claim review before deciding to move forward.

    If your roof, siding, windows, or property sustained hail damage, a public adjuster can pay for itself. Denver sees frequent, severe hailstorms, and insurers routinely underestimate the full cost of repair or replacement. A free claim review tells you quickly whether professional help is worthwhile. Results vary by claim.

    Timelines vary with the severity of the loss and how responsive the insurer is, but most residential hail claims typically resolve within a few weeks to a few months. Colorado law sets deadlines for insurers to acknowledge, investigate, and pay claims, and we hold them to those timelines.

    Yes. We regularly take over claims that were filed, underpaid, or denied. We re-inspect the property, re-document the damage, and reopen negotiations or pursue an appeal to recover the difference between what you were paid and what you are entitled to.

    Absolutely. We handle commercial and large-loss claims across the Denver metro, including retail, office, multi-family, HOA, and warehouse properties. Commercial policies are complex, and expert representation often makes a significant difference in the final settlement.

    Hail damage is easy to underestimate. Insurer adjusters may miss damage, apply aggressive depreciation, or scope repairs too narrowly. Because we work for you, we document every affected system and price repairs to local Denver labor and material costs so nothing is left on the table.

    A contractor repairs the damage; a public adjuster manages and negotiates the insurance claim on your behalf. Contractors aren't licensed to negotiate insurance claims in Colorado. We work alongside your contractor to make sure the claim fully funds the repairs your property needs.

    We serve the entire Denver metro, including Aurora, Lakewood, Thornton, Arvada, Westminster, Centennial, Englewood, Highlands Ranch, Parker, Castle Rock, Broomfield, Longmont, Littleton, Greenwood Village, and Cherry Hills Village across Jefferson, Arapahoe, Adams, Douglas, and Boulder counties.

    Denver HQ

    Call our Denver office.

    1776 S. Jackson St, Suite 528
    Denver, CO 80210

    Ready to find out what your Denver property claim is really worth?

    It only takes a few minutes. No upfront cost. We only get paid when you do.

    Licensed in Colorado · Contingency fee, no upfront cost · AI-assisted policy analysis · Serving Denver and the Front Range · Individual results vary.