Introducing Justin: Built for property owners - analyze your insurance policy in under 10 minutes. Always free. Analyze your policy now →

Colorado Springs Public Adjusters for Hail & Storm Claims

El Paso County sits in one of the most active hail corridors in North America, and your carrier knows exactly what that costs them.
When the adjuster arrives after a storm, they work for the insurance company. We work only for you - reading the policy, documenting every line of damage, and holding the carrier to what your coverage actually owes.

  • Licensed Colorado public adjusters serving El Paso County and Southern Colorado
  • No upfront cost - we are paid only out of what we recover for you
  • Hail, wind, wildfire and water losses: new, underpaid, denied or reopened

Free claim review. No obligation.

Get a Free Claim Review

Tell us about your Colorado Springs property and the damage. We review it at no cost.

    No upfront cost. We only get paid if you recover. Licensed Colorado public adjusters.

    $50M+
    Recovered for property owners
    100+
    Combined years of experience
    3x
    Higher settlements than initial offer
    $0
    Zero upfront cost
    Colorado Springs Storm Risk

    You live in the middle
    of Hail Alley.

    Colorado Springs sits where the Front Range drops into the plains - the corridor that produces more damaging hail than almost anywhere in the country. Add wildfire season and downslope wind off Pikes Peak, and one year can hand you three different kinds of claim.

    Storm Hail

    Hail Alley's bullseye

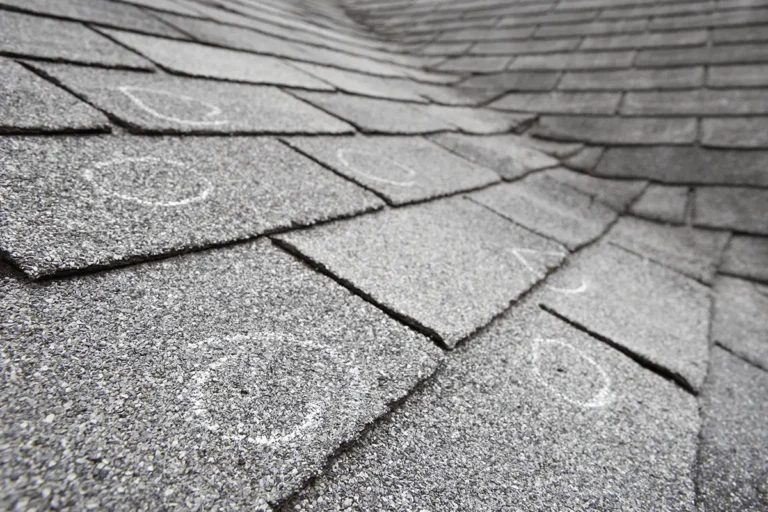
    El Paso County takes hail every May through September, and carriers meet it with cosmetic-damage language, split wind-and-hail deductibles and inspections built to find as little as possible. We document what the storm actually did - mat bruising, granule loss, spatter on soft metals - and hold the file to it.
    Wildfire smoke and ash

    Wildfire, smoke and ash

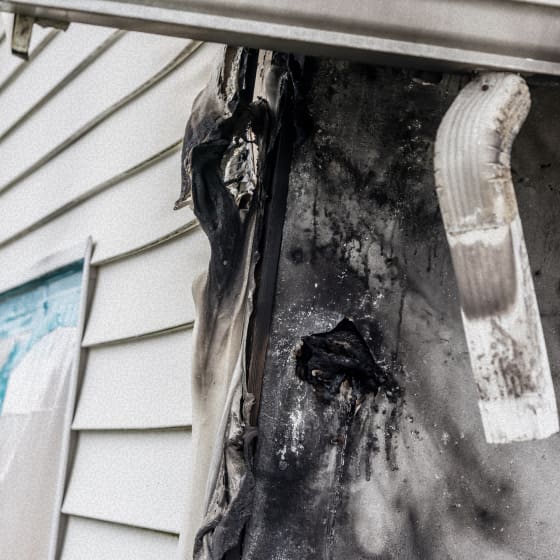
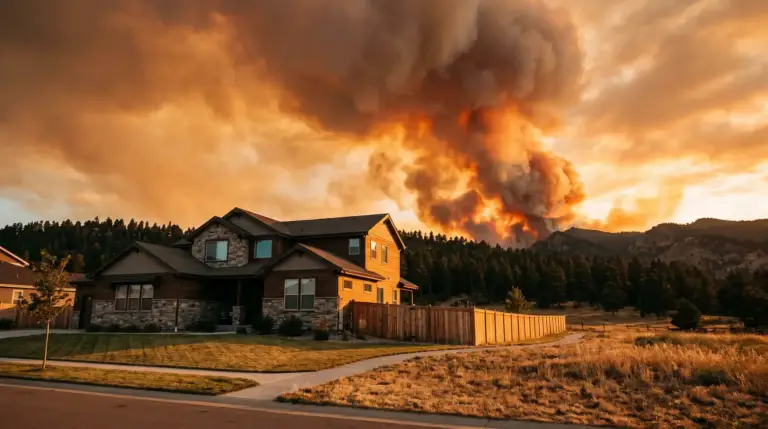
    Waldo Canyon in 2012 and Black Forest in 2013 are still the benchmark losses here. Smoke, ash and heat damage get underpaid because they are harder to see than a burned structure - contents, remediation and code upgrades all belong in the claim.

    Wind and Chinook events

    Downslope wind off the peak

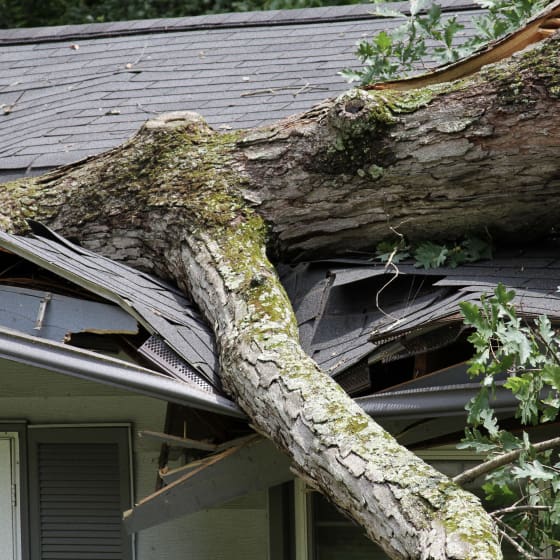
    Chinook and downslope events funnel off Pikes Peak with gusts that lift shingles, fascia and fencing. Wind loss usually arrives bundled with hail from the same storm, and separating the two correctly protects your deductible and your payout.

    How it works

    Three steps, and the first one is free.

    You do not need to know what your claim is worth before you call. Working that out is our job.

    contractors-howitworks-01
    Step 1

    Free policy and damage review

    Send us the policy and whatever else you have - photos, the carrier's estimate, an inspection report. We read the coverage and tell you straight whether you actually need a public adjuster.

    Start your free claim review →
    contractors-howitworks-02
    Step 2

    We document the whole loss

    We inspect, measure and price the damage at Colorado Springs replacement cost, including the code requirements and line items carrier estimates routinely leave out.

    Start your free claim review →
    contractors-howitworks-03
    Step 3

    We negotiate until it is right

    We handle the carrier, the re-inspections and the appraisal process if it comes to that. Nothing closes until you approve the settlement.

    Start your free claim review →

    Where Colorado Springs claims go wrong.

    Most people call us after the carrier has already made a decision. That is still the right time to call - a filed claim is not a finished claim.

    Your claim was denied

    A denial is a position, not a verdict. Most rest on a cosmetic-damage argument, a wear-and-tear call, or a deadline the carrier says you missed - and all three can be challenged with better evidence.

    Learn more →

    The offer will not cover the work

    Underpayment is the usual outcome here, not the exception. Partial roof approvals, ignored code requirements and depreciation that never gets released all quietly shrink what you collect.

    Learn more →

    Nobody will give you a straight answer

    Reassigned adjusters, unreturned calls and repeated requests for documents you already sent are how a claim slides past an entire season. Colorado requires carriers to move on a reasonable timeline.

    Learn more →

    We have expertise on all building types:

    • Office Buildings
    • Retail & Restaurants
    • Industrial & Warehouse
    • Hospitality & Lodging
    • Healthcare Facilities
    • Multi-Family
    • Religious & Community
    • REITs & Funds

    See what your Colorado Springs claim is really worth.

    Get a Free Claim Review

    Free review. Colorado-licensed adjusters. No upfront cost.

    Reality of Colorado Springs Claims

    The deck is not level.

    Your carrier assigns a field adjuster, a desk examiner, and often an engineer. Every one of them is paid by the company that writes the check.
    You are expected to read a hundred-page policy, price a roof, and argue building code on your own - usually while living in a damaged house.
    • Cosmetic-damage language used to deny functional hail damage
    • Partial roof approvals that leave mismatched slopes
    • Code and ordinance coverage left out of the estimate
    • Withheld depreciation that never gets recovered
    • Wind and hail deductibles applied incorrectly
    Colorado Springs insurance claim types

    Claims we handle across El Paso County.

    Hail drives most of the volume here, but it is rarely the only thing a storm leaves behind.

    Hail damage claims

    The signature Colorado Springs loss. Carriers lean on cosmetic-damage exclusions and approve a slope instead of a roof. We prove functional damage and price the full replacement.

    Learn more →

    Wind and storm damage

    Downslope gusts strip shingles, fascia, gutters and fencing. Wind and hail from one storm are often split across two deductibles, and that split has to be right.

    Learn more →

    Fire and wildfire claims

    Structure loss, smoke, ash and heat damage, plus contents and code upgrades. Southern Colorado wildfire claims are routinely settled well below what the policy covers.

    Learn more →

    Water and freeze losses

    Frozen and burst pipes, roof leaks after hail, and appliance failures. Hidden moisture and mould remediation are where these claims get thin.

    Learn more →

    Commercial property claims

    Retail, office, industrial and hospitality along the I-25 corridor. Business interruption and code compliance are usually the largest items nobody put in the estimate.

    Learn more →

    HOA and condo claims

    Shared roofs, common elements and the gap between the master policy and a unit owner's coverage. Multi-building hail claims need documenting building by building.

    Learn more →
    For Colorado Springs Contractors

    Stop losing jobs to a carrier's estimate.

    We are not competing with you. When the scope is short, we are the ones who get it corrected so the work you bid is the work that gets funded.

    Roofers

    Hail season fills your schedule and then the carrier approves two slopes and a repair. We take on the supplement fight, the re-inspection and the appraisal so the full replacement gets paid.

    Restoration

    Mitigation invoices get trimmed line by line. We document cause of loss, drying logs and code requirements so the file supports what you already did on site.

    General Contractors

    Larger rebuilds stall on scope disputes and overhead and profit. We handle the carrier negotiation so your crews are not waiting on an adjuster to call back.

    Colorado Insurance Law

    Your rights under Colorado law.

    Colorado gives policyholders more leverage than a carrier's first letter suggests. Here is the part that matters when you are disputing a Colorado Springs claim. This is general information, not legal advice.

    01

    Your adjuster must be licensed

    Anyone handling your claim as a public adjuster has to hold a licence from the Colorado Division of Insurance. That is a consumer protection you can use: verify the licence before you sign anything. JustClaims is a licensed Colorado public adjuster.

    02

    Appraisal can break a deadlock

    When the dispute is about the amount of the loss rather than whether it is covered, most Colorado property policies contain an appraisal clause either side can invoke. It is usually faster and cheaper than litigation. See how the appraisal process works.

    03

    Carriers owe you good faith

    Colorado requires insurers to investigate and pay claims fairly and within a reasonable time. Unreasonable delay or a lowball settlement is not simply bad service - it carries consequences the carrier would rather you did not know about.

    04

    The clock is already running

    A low offer is not something to sit on. How long you have to dispute a property claim is limited by state law and by the "suit against us" clause in your own policy. Acting early keeps every option open; waiting closes them one by one.

    JustClaims provides public adjusting services, not legal advice. For legal questions, consult a licensed Colorado attorney.

    Southern Colorado areas we serve

    Serving property owners across El Paso and Teller County.

    We cover Colorado Springs and the surrounding communities from our Colorado office. If your property took hail, wind, fire or water damage anywhere in the region, the review is free.

    Colorado Springs Insurance claim help
    Monument Insurance claim help
    Fountain Insurance claim help
    Falcon Insurance claim help
    Security-Widefield Insurance claim help
    Manitou Springs Insurance claim help
    Woodland Park Insurance claim help
    Black Forest Insurance claim help
    Cimarron Hills Insurance claim help
    Briargate Insurance claim help
    Broadmoor Insurance claim help
    Old Colorado City Insurance claim help
    Palmer Lake Insurance claim help
    Peyton Insurance claim help
    Green Mountain Falls Insurance claim help
    Calhan Insurance claim help
    City Lead

    Meet the adjuster covering Southern Colorado.

    Reviewed and Verified by

    Taylor Bezek

    Taylor runs claims operations for JustClaims out of Colorado, where he has spent eleven years and close to 1,500 property claims learning how carriers in this state actually behave after a hail season.
    He holds a Master's in International Security with a Certificate in Homeland Security from the University of Denver, and he has handled everything from single-family roofs to multi-building commercial losses. If you call about a Colorado Springs property, his team is the one that reads your policy.

    General Manager at JustClaims Licensed CO Public Adjuster #769172 Nearly 1,500 Colorado Claims 11 Years in Colorado University of Denver Alum

    Colorado Springs Claim QuestionsAnswered by licensed adjusters

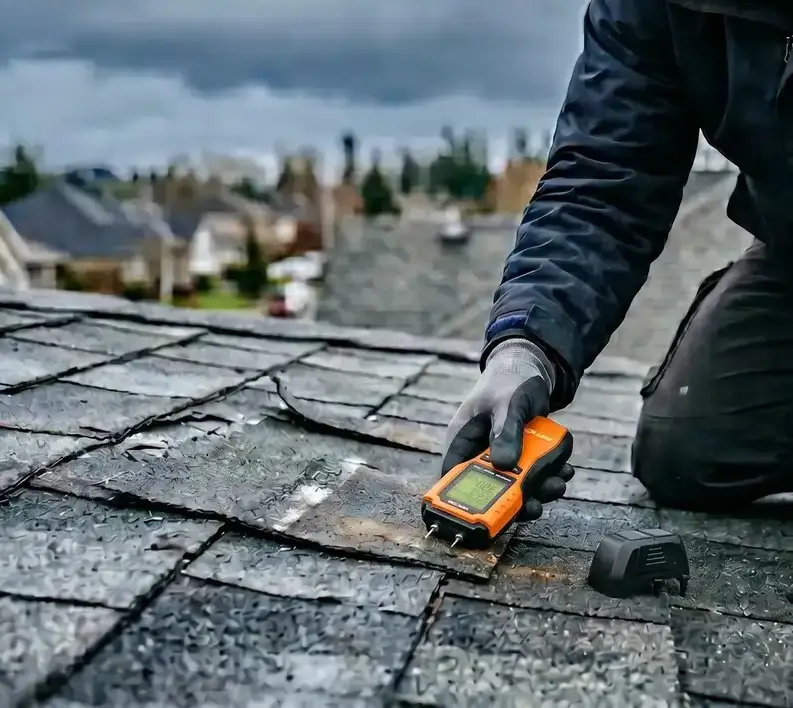
    They can take that position, and in Colorado they often do. Cosmetic-damage language is meant for dents that do not affect performance - not for shingles whose mat has been fractured or whose granule loss has started the clock on failure. The argument is won with evidence: test squares, moisture readings, manufacturer criteria and spatter patterns on soft metals that date the storm. We build that record and make the carrier respond to it rather than to a photo taken from the driveway.

    Colorado draws a specific line here, and it is narrower than most people assume. Under C.R.S. § 6-22-105(3) a roofing contractor cannot claim to be, or act as, a public insurance adjuster adjusting your claim - but the same subsection expressly allows a roofer who holds a valid contract with you to discuss the scope of repairs with your insurer on your behalf. So a scope conversation is legitimate; running the claim for you is not, and doing that requires a public adjuster licence under C.R.S. § 10-2-417. One more thing worth knowing in a hail market: the same statute makes it unlawful for a roofer to advertise or promise to pay, waive or rebate your deductible, and if one does, your insurer is not obliged to consider their estimate at all.

    The policies look similar; the exposure does not. El Paso County takes repeated hail seasons, so carriers here lean harder on wind-and-hail deductibles that are a percentage of your dwelling value rather than a flat amount, and on cosmetic-damage endorsements. Elevation and terrain also change the storm record - a hailstorm can flatten Falcon and barely touch Manitou Springs the same afternoon. Proving which storm hit your address, and on what date, matters more here than most people expect.

    That decision belongs to the carrier, and we will not pretend otherwise. Claim history is one of the things insurers weigh, and after several severe hail seasons the whole Colorado market has tightened. What we can tell you is whether the loss is large enough to be worth filing - that is part of the free review. Walking away from a covered claim that exceeds your deductible by a wide margin to protect a premium is usually the more expensive choice.

    It depends on your policy language and on what the damage actually is. Carriers frequently approve the two slopes that face the storm and leave the rest, which produces a roof that does not match and often is not watertight at the transitions. Where shingles are discontinued or repair cannot restore a uniform appearance, a full replacement is generally the correct scope. Whether you are paid replacement cost or actual cash value, and whether you get the withheld depreciation back, is a separate question we check at the same time.

    Often, yes - a closed claim is not automatically final. If the original scope missed covered items, or new damage evidence surfaces, the claim can usually be reopened and the shortfall pursued as a supplement, which is a routine part of the process. Two separate clocks limit you: the "suit against us" deadline in your own policy, which is often shorter than people expect, and Colorado's statutory limit for contract claims. Send us the policy and the claim correspondence and we will tell you honestly whether there is still room to act.

    Your declarations page and the full policy if you have it, any estimate or denial letter the carrier sent, the claim number, the date of loss if you know it, and photographs from before and after the damage if they exist. If you have none of that, call anyway - we can pull most of it. The single most useful thing is the storm date, because it anchors everything else in the file.

    Colorado HQ

    Our Colorado office covers the Springs.

    1776 S. Jackson St, Suite 520
    Denver, CO 80210

    Find out what your claim is actually worth.

    A free review costs you nothing and takes one conversation. If you do not need a public adjuster, we will tell you that.

    Licensed in Colorado · Contingency fee, no upfront cost · AI-assisted policy analysis · Serving Colorado Springs, El Paso County and Southern Colorado