


Florida Public Adjuster: Maximize Your Property Insurance Claim Statewide
Commercial, HOA & hurricane claims across Miami, Orlando, Tampa & Jacksonville.
From the Panhandle to the Keys, we help Florida property owners recover the full payout they're owed after hurricane, wind, water, or fire damage. When the carrier underpays, delays, or denies, we step in. No upfront cost. We only get paid when you do.
We specialize in commercial and HOA claims — the claims carriers most often underpay.
We serve all of Florida.
Choose your market for details. Our Florida team handles commercial, HOA, and hurricane claims across the major metros and the communities around them.
Types of claims we handle in Florida.
Our primary focus is commercial and HOA property, where carriers underpay most. We pair every property type to the damage and the dispute we see again and again.

Retail Strips & Offices
Roof damage written off as cosmetic; partial-replacement scopes after a named storm.

Warehouses & Industrial
Flat-roof claims classed as maintenance rather than hurricane-caused.

Medical & Dental Clinics
Specialized equipment and code-upgrade costs left out of the estimate.

Shopping Malls & Hospitality
Large-roof scope cuts; depreciation and overhead-and-profit games.

Self-Storage Facilities
Wind vs. flood causation; contents and business-interruption limits.

HOA & Multi-Family
Master-policy vs. unit coverage gaps; per-unit damage undercounted.
Not sure if your damage qualifies?
Get a Free Claim ReviewUnderpaid, delayed, or denied?
Florida carriers reach for the same three moves across every market. We fight all three.
Did they underpay you?
Lowball estimates, missed damage, and preferred-contractor scopes. We rebuild the number from the actual loss and document the full scope independently.
Is your claim stuck?
Silence, re-inspections, endless requests. We keep the file moving and hold the carrier to the Fla. Stat. §627.70131 prompt-payment timelines.
Were you denied?
A denial isn't the end. We review the policy, document what's covered, and re-submit with independent evidence. You can also file a complaint with Florida DFS.
The math carriers hope you don't do
Florida's rule set is a numeric minefield — percentage hurricane deductibles, tight notice windows, and statutory fee caps. Three numbers worth knowing before the next storm.
On a $1,000,000 insured building, a 2% hurricane deductible means you absorb $20,000 of a named-storm loss before the carrier pays a dollar. Coastal percentage deductibles run 5–10%.
Fla. Stat. §627.70132 gives you 1 year to notify the carrier of a hurricane claim and 18 months for a supplemental claim. Miss it and the claim is barred.
Fla. Stat. §626.854 caps public-adjuster fees at 10% on claims from a declared state of emergency, and 20% on reopened or supplemental claims. Our fee only comes out of the recovery.
Why Florida properties need a public adjuster.
Florida sees the nation's most frequent hurricane losses, and insurers lean on preferred-contractor scopes that come in below full replacement cost, especially on commercial and HOA property. A public adjuster is licensed by the Florida Department of Financial Services to represent only the policyholder, never the carrier.
Your Public Adjuster
Works only for you. We step in when the carrier underpays, delays, or denies. We review the policy, document the full loss independently, file or reopen the claim, and negotiate for the maximum recovery your policy supports.
The Insurer's Adjuster
Works for the insurance company. They assess your loss in the carrier's interest, often using preferred-contractor scopes. On commercial and HOA property in particular, that first number is rarely the full number.
How Florida owners work with JustClaims.

Free claim review
We assess your policy and your damage at no cost and tell you straight whether you need a public adjuster.

Independent Documentation
A DFS-licensed adjuster inspects and documents every covered loss, with AI-assisted tools, before any contractor estimate goes to the carrier.

Filing & negotiation
We file or reopen your claim and negotiate directly with the carrier on your behalf, holding them to the §627.70131 clock.

You recover
Once the claim settles, our fee comes out of the recovery. No recovery, no fee.
Contact us before your insurer's adjuster closes the file.
Get a Free Claim ReviewJustClaims vs. your insurer's adjuster.
Factual comparison of roles. Only a licensed public adjuster or attorney can negotiate your claim in Florida.
JustClaims serves all of Florida.
Our Florida team is led by a DFS-licensed public adjuster serving Miami, Orlando, Tampa, and Jacksonville — handling commercial, HOA, and hurricane claims from the Panhandle to the Keys.
A name Florida owners trust.

We work for you, never the insurance company.
We read your policy, document the full loss, and negotiate the maximum recovery.
Commercial and HOA-heavy specialty.
Complex master-policy, condo, and HOA claims — from Miami towers to Panhandle retail strips.
Regional presence with local claims experience.
Our adjusters live in the markets we serve — Miami, Orlando, Tampa, Jacksonville, and the communities around them.
No upfront cost.
No retainer, no hourly bills. We work on contingency — no recovery, no fee.
Want a team that works only for you?
Get a Free Claim ReviewFour major markets, one Florida team.
Miami
Hurricane, flood, and condo association claims across Miami-Dade and the Gold Coast.
Coming Soon
Orlando
Wind, water, and HOA claims across Central Florida, from tourism-corridor commercial to residential.
Coming Soon
Tampa
Hurricane, wind, and water claims across Tampa Bay, including coastal and condo losses.
Coming Soon
Jacksonville
Storm, wind, and commercial claims across Northeast Florida and the First Coast.
Coming Soon
Meet our Florida lead public adjuster
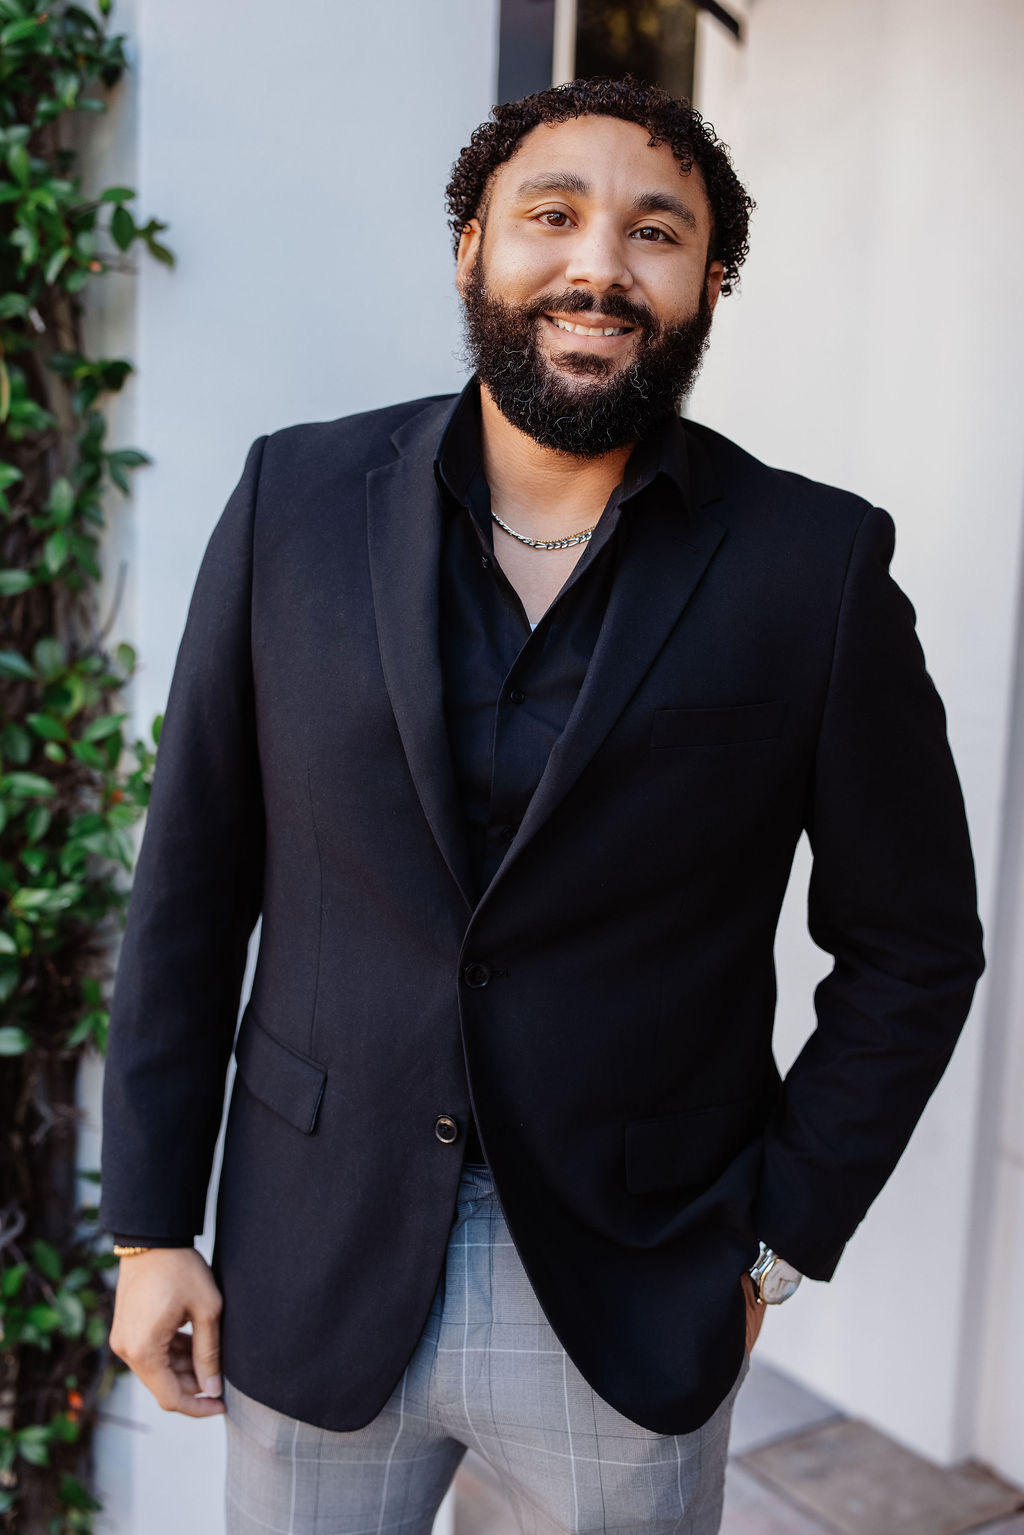
Stephane Elias
A seasoned insurance professional with nearly a decade of experience, Stephane Elias is currently serving as a Senior Claims Professional and Public Adjuster with JustClaims. Throughout his career, Stephane has represented policyholders through leading public adjusting firms and served as a loss consultant for law firms specializing in insurance litigation, giving him extensive expertise in complex property insurance claims. A licensed public adjuster in FL (#W564547), TX (#2645032), and six other states, he specializes in commercial and residential property claims, claims management, appraisals, mediation, and strategic partnerships. Stephane is passionate about helping policyholders overcome delayed, denied, and underpaid insurance claims, ensuring they receive the full recovery they're entitled to under their policy.
Frequently Asked Questions
No. Florida law reserves claim negotiation for licensed public adjusters and attorneys (Fla. Stat. §626.854), and a contractor who offers to "handle the insurance" risks unlicensed adjusting. We take the insurance side so the contractor can stay focused on the work.
Fla. Stat. §627.7152 sharply restricted assignment of benefits in 2023 — a contractor can no longer take over your claim rights the way they used to. More owners now keep control of the claim and hire their own public adjuster directly. If anyone asks you to sign an AOB, have it reviewed first.
You send us the owner and the claim details, we take the insurance side, and you stay focused on the work. We keep both of you informed from inspection through settlement.
Yes. We work directly with boards and property managers to review the offer, re-document the full scope across units and common elements, and negotiate the difference. Master-policy and per-unit gaps are exactly where carriers underpay most.
Wind damage goes to the property policy under its hurricane deductible; storm surge and rising water go to NFIP or private flood coverage. Each carrier points at the other — we document causation line by line so neither side can push your loss off their books.
Florida caps fees by statute: 20% of a reopened or supplemental claim, and 10% on claims arising from a declared state of emergency in its first year (Fla. Stat. §626.854). JustClaims works on contingency — no recovery, no fee.
Yes. For hurricane claims, Fla. Stat. §627.70132 allows supplemental notice within 18 months of the loss. We re-inspect, document what the first scope missed, and negotiate the supplement directly with the carrier.
Retail strips, warehouses and industrial, medical and dental offices, shopping malls and hospitality, self-storage, and HOA/multi-family — from Miami and Orlando to Tampa, Jacksonville, and the communities around them.
Florida has a matching statute (Fla. Stat. §626.9744): when repairs can't achieve a reasonably uniform appearance, the insurer must replace adjoining items to match. Whether it applies depends on your policy and the loss — we review both before the carrier's scope becomes the ceiling.
Under Fla. Stat. §627.70132 you have one year from the date of loss to give notice of a hurricane claim and 18 months for a supplemental claim. Don't wait — evidence and access get harder with every month.
That's the most common Florida denial after a named storm. We document the storm's path and timing, commission independent reports where needed, and rebut the pre-existing finding with evidence the carrier's first inspection missed.
Still have questions? We're happy to help.
Get a Free Claim ReviewFind out what your Florida property claim is really worth.
It only takes a few minutes. No upfront cost. We only get paid when you do.
Licensed by the Florida Department of Financial Services · Contingency fee, capped by law · Miami · Orlando · Tampa · Jacksonville