Introducing Justin: Built for property owners - analyze your insurance policy in under 10 minutes. Always free. Analyze your policy now →

San Antonio public adjuster for hail, wind & flash flood claims.

San Antonio sits in the heart of Texas hail alley, and Flash Flood Alley runs right through the city. When the carrier underpays, delays, or denies your hail, wind, or water claim, our public adjusters step in. We handle commercial, HOA, and homeowner property claims across the San Antonio metro and document the full loss independently — before any contractor estimate goes to the insurer.

  • No upfront cost. We only get paid when you recover.
  • Commercial, HOA & homeowner claims across greater San Antonio.
  • Licensed by the Texas Department of Insurance.

We only get paid when you do.

Get your free San Antonio claim review

Tell us about your property and the damage. A licensed Texas public adjuster reviews it at no cost.

    No upfront cost. We only get paid if you recover. Licensed Texas public adjusters.

    $50M+
    Recovered for property owners
    100+
    Combined years of experience
    3x
    Higher settlements than initial offer
    $0
    Zero upfront cost
    How it works

    How a public insurance adjuster wins your San Antonio claim.

    No upfront cost, no carrier runaround — a licensed Texas public insurance adjuster handles everything in three steps.

    contractors-howitworks-01
    Step 1

    Tell us what happened

    Share your property details and the damage. We review your policy and the loss at no cost, and tell you honestly whether a public adjuster adds value.

    Book your free claim review →
    contractors-howitworks-02
    Step 2

    We document the full loss

    A TDI-licensed public adjuster who knows San Antonio hail, wind, and water claims inspects, photographs, and scopes every line item — then prices the real cost of repair.

    Book your free claim review →
    contractors-howitworks-03
    Step 3

    We negotiate, you get paid

    We present the claim, handle every carrier call and deadline, and push for the full amount your policy owes. No recovery, no fee.

    Book your free claim review →
    San Antonio storm damage

    Hail, wind, and flash flood.
    San Antonio's three costliest storm losses.

    Storm damage in San Antonio comes in three forms — hail-alley hail, straight-line wind, and Flash Flood Alley water. These are the losses we see most across the metro, and the ones carriers most often underpay.

    Hail & roof damage

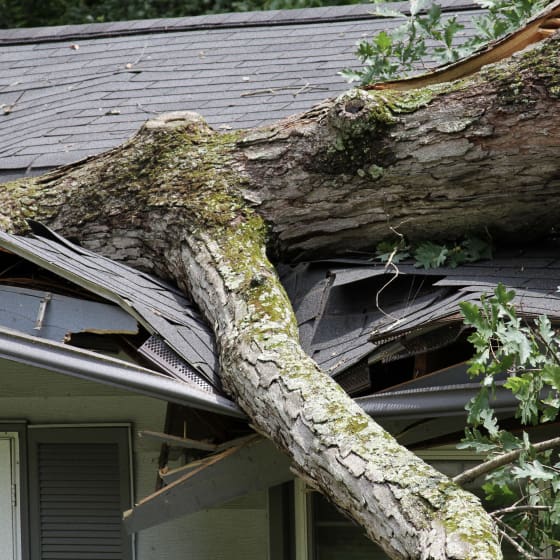
    Spring hail hammers San Antonio roofs, siding, and gutters every year — Bexar County sits squarely in Texas hail alley. Carriers love to call functional hail damage "cosmetic." We document impact patterns, storm dates, and bruised shingles to prove the covered loss.

    Wind & storm damage

    Straight-line winds and severe thunderstorms peel roofing, snap fences, and breach the building envelope — then the rain gets in. We scope the full wind loss, including the water intrusion that follows, not just the obvious roof damage.

    flood Damage

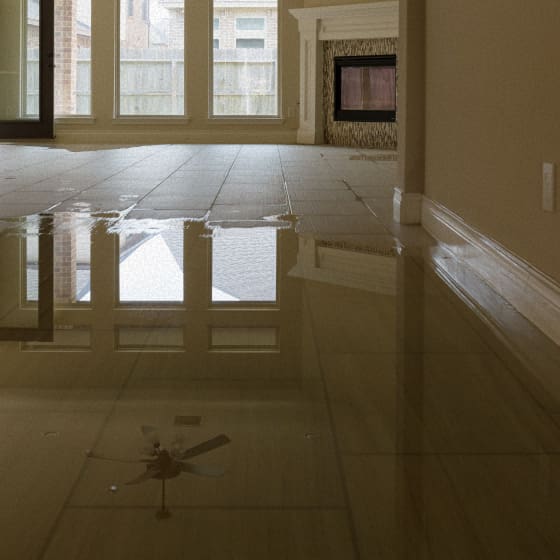
    Flash flood & water

    San Antonio is Flash Flood Alley — intense Hill Country rain sends water into homes and businesses in minutes. Standard policies exclude rising water, but wind-driven rain and sudden discharge are covered. We separate the covered water loss from the excluded flood and fight for every covered dollar.

    San Antonio claim reality

    Hail alley above, Flash Flood Alley below. In San Antonio, Texas, a public adjuster is how you get full value.

    San Antonio takes hail strikes nearly every spring, and the Balcones Escarpment makes the city one of the most flash-flood-prone metros in the country. Commercial roofs along the I-35 and Loop 1604 corridors, HOA communities, and Hill Country homes all take the hit.

    The insurance company's adjuster works for the carrier — often pricing preferred-contractor scopes that come in below full replacement cost. Texas has no matching statute, so whether the insurer owes full-area replacement depends entirely on your policy's "like kind and quality" language. Many San Antonio owners accept a partial payout without knowing their policy may support more.

    We cover the entire San Antonio metro, from Boerne and Helotes to Schertz and Converse, which means faster response and less friction on claims across South Central Texas.
    • Licensed by the Texas Department of Insurance
    • We document the full scope independently — before the insurer's preferred-contractor estimate
    • Commercial, HOA, and homeowner claims across Bexar County
    • We work exclusively for policyholders — never for insurance companies
    • Full San Antonio metro coverage, from Boerne to Schertz
    Property claims we handle in San Antonio

    Every type of San Antonio property damage claim, handled.

    From Stone Oak homes to downtown commercial towers and HOA communities across Bexar County — hail, wind, water, and fire — we cover the full range of San Antonio insurance claims.

    Hail damage claims

    Roof, siding, and gutter damage from San Antonio's spring hail cycles — the most common, and most underpaid, claim type in Bexar County.

    Hail claim help →

    Water & flood claims

    Flash flooding, burst pipes, and roof leaks. We separate covered sudden water losses from excluded flood and document the hidden moisture carriers skip.

    Water damage claim help →

    Wind & storm claims

    Straight-line winds tear roofing, siding, and signage across the metro — and let the rain in behind them. We scope the whole envelope.

    Wind damage claim help →

    Commercial property claims

    Offices, retail, warehouses, and industrial parks across San Antonio — structure, contents, and business-interruption components, managed start to finish.

    Commercial claim help →

    HOA & condo claims

    Master-policy vs. unit coverage and per-building hail damage across San Antonio communities. We document every building, not just the clubhouse.

    HOA claim help →

    Fire & smoke claims

    Structure fire, smoke and soot, and contents loss across San Antonio homes and commercial stock — scoped for full repair, not carrier minimums.

    Fire claim help →
    When the carrier shorts you

    How San Antonio claims get shorted — and how we fight back.

    The carrier's playbook on San Antonio claims is simple: pay less than you're owed, drag past the deadlines, or deny and hope you go away. We have decades of experience and fight all three.

    Settlement came in low?

    The check arrived, but it won't cover the repairs. We re-scope the loss independently — line by line — and negotiate the settlement up to what the policy actually owes.

    Get help with this →

    Claim stuck in limbo?

    Weeks turn into months while the carrier requests one more document, one more photo, one more inspection. Texas §542 sets hard deadlines — we hold them to every one.

    Get help with this →

    Claim denied outright?

    A denial letter is not the final word. We reopen the claim, re-document what the first inspection missed, and fight to overturn it — with TDI's complaint process as a backstop.

    Get help with this →

    We have expertise on all building types:

    • Office Buildings
    • Retail & Restaurants
    • Industrial & Warehouse
    • Hospitality & Lodging
    • Healthcare Facilities
    • HOA & Multi-Family
    • Self-Storage
    • REITs & Funds

    Find out what your San Antonio claim is really worth.

    Get a Free Claim Review

    Free review. San Antonio experts. No upfront cost.

    Texas Insurance Law

    Texas insurance law for San Antonio policyholders.

    Texas gives property owners real leverage — if you know the rules. Four things matter most on a San Antonio claim. This is general information, not legal advice.

    01

    Public adjusters are TDI-licensed

    Anyone who negotiates your San Antonio claim for a fee must be licensed by the Texas Department of Insurance. Verify before you sign — JustClaims' Texas public adjuster license is #2645032.

    02

    Prompt-payment deadlines (§542)

    Texas Insurance Code §542 puts the carrier on a clock: acknowledge your claim within 15 calendar days, then accept or reject it within 15 business days of receiving your documentation — extendable by 45 days only with written notice. Miss the clock and the carrier can owe interest.

    03

    Fee cap + 72-hour cancellation

    Texas caps public-adjuster fees at 10% of the settlement, and you can cancel a public-adjuster contract within 72 hours of signing, no questions asked. JustClaims works on contingency — no recovery, no fee.

    04

    Matching is a policy question

    Texas has no matching statute. Whether the insurer must replace undamaged materials to match depends on your policy's "like kind and quality" language — not state law. We read that language and document the full scope it supports.

    JustClaims provides public adjusting services, not legal advice. For legal questions, consult a licensed Texas attorney.

    San Antonio & South Texas areas we serve

    Serving property owners across the entire San Antonio metro.

    Our adjusters handle claims across San Antonio, New Braunfels, San Marcos, Boerne, Schertz, Cibolo, Converse, Universal City, Live Oak, Selma, Helotes, Alamo Heights, and Castle Hills — spanning Bexar, Comal, and Guadalupe counties.

    New Braunfels Insurance claim help
    San Marcos Insurance claim help
    Boerne Insurance claim help
    Schertz Insurance claim help
    Cibolo Insurance claim help
    Converse Insurance claim help
    Universal City Insurance claim help
    Live Oak Insurance claim help
    Selma Insurance claim help
    Helotes Insurance claim help
    Alamo Heights Insurance claim help
    Castle Hills Insurance claim help
    For San Antonio Contractors

    Partnering with San Antonio's roofers and restoration pros.

    We handle the insurance side so you can focus on the build. You keep the customer relationship; we keep the carrier honest. And since Texas law doesn't let contractors negotiate the claim, a licensed public adjuster is the compliant route to getting your full scope approved and paid.

    Roofers

    Commercial and residential roofers and storm-response crews across the San Antonio hail corridor.

    Restoration

    Water mitigation, fire and smoke restoration, and disaster recovery firms.

    General Contractors

    Commercial builders, multi-family renovation firms, and large-loss rebuild specialists.

    City lead

    Meet our San Antonio lead public adjuster

    Reviewed and Verified by

    Stephane Elias

    A seasoned insurance professional with nearly a decade of experience, Stephane Elias is currently serving as a Senior Claims Professional and Public Adjuster with JustClaims. Throughout his career, Stephane has represented policyholders through leading public adjusting firms and served as a loss consultant for law firms specializing in insurance litigation, giving him extensive expertise in complex property insurance claims.

    A licensed public adjuster in TX (#2645032), FL (#W564547), and six other states, he specializes in commercial and residential property claims, claims management, appraisals, mediation, and strategic partnerships. Stephane is passionate about helping policyholders overcome delayed, denied, and underpaid insurance claims, ensuring they receive the full recovery they're entitled to under their policy.

    Senior Claims Professional at JustClaims Licensed Public Adjuster in Texas #2645032 and Florida #W564547
    San Antonio claim FAQs

    San Antonio property claim questions, answered.

    A percentage deductible is calculated against your dwelling coverage limit, not the repair bill. On a San Antonio home insured for $400,000, a 2% wind/hail deductible means you pay the first $8,000 of a hail loss out of pocket. That math makes claim scope critical: if the carrier's estimate is $15,000 but the real damage is $30,000, the deductible effectively doubles against you. We make sure the full loss is documented so the deductible applies to the right number — and so damage the carrier missed doesn't come out of your pocket instead.

    Generally two separate claims — each storm is its own occurrence with its own deductible. That cuts both ways: you may owe two deductibles, but you're also entitled to full payment for each storm's damage. The fight is usually about attribution. Carriers sometimes lump everything into the older storm to apply one deductible and a worn-roof narrative, or write off newer damage as "prior damage." We date each storm against weather records and document which damage belongs to which event, so neither claim is shorted.

    Usually not — and it's the most painful surprise in Flash Flood Alley. Standard homeowners and commercial policies exclude rising surface water; that needs separate NFIP or private flood coverage. But not every water loss during a storm is "flood": rain driven in through a wind-damaged roof or opening is typically covered, and so is sudden discharge from plumbing or appliances. The battle is over where the water came from. We document entry points, water lines, and weather data to separate the covered water damage from the excluded flood — and we review your policies to tell you honestly what applies.

    Because your lender has a financial interest in the property, most Texas policies require claim checks to include the mortgage company. The lender typically endorses the funds into an escrow account and releases them in stages as repairs are completed and inspected. The process is paperwork-heavy and slow if you don't follow their exact requirements — and some owners leave final draws unclaimed. We help you package the documentation, supplements, and completion proof the lender needs so the money actually moves.

    No — they're two different policies entirely. Your car is covered under your auto policy's comprehensive coverage; your roof is under your homeowners or commercial property policy. Each has its own deductible and its own claim. File both — hail is exactly what comprehensive auto coverage is for. On the property side, we handle the building claim so the auto claim doesn't distract from fully paying the roof.

    Same storm doesn't mean same outcome. Different carriers, different policies, different adjusters — and often, different documentation. Denials usually hinge on how the damage was presented: one owner had dated photos and a full scope, the other got a five-minute inspection and a "wear and tear" letter. A denial is not the end. We re-inspect, document the impact pattern and storm date properly, and challenge the denial with the evidence the first inspection missed. Neighbor comparisons aren't proof — but they're a good reason to get a second opinion.

    Get every dollar your San Antonio property claim deserves.

    It takes a few minutes to find out. No upfront cost — we only get paid when you do.

    Licensed by the Texas Department of Insurance · Contingency fee, capped at 10% · Serving San Antonio & South Central Texas