Hail & roof damage
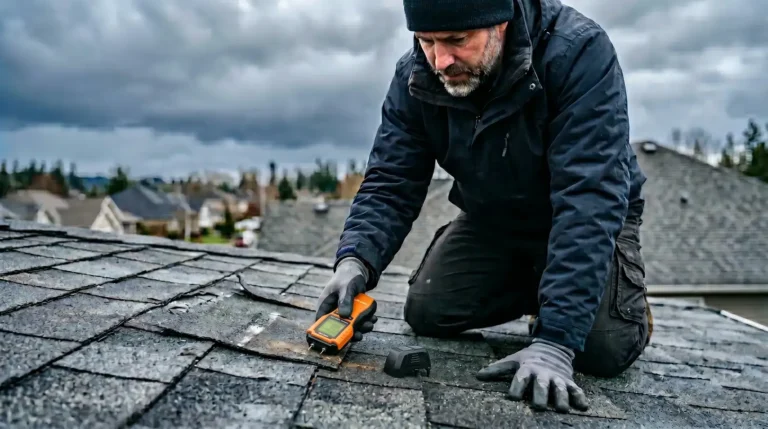
Hail bruises shingles, dents soft metals, and breaks the seals that keep water out. We document the full roof system and the interior damage that follows — not just the shingles a carrier's inspector circles.
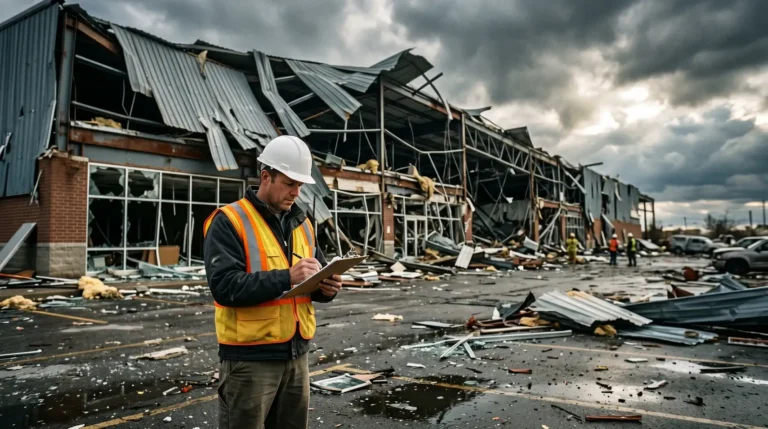
Atlanta's storm season does not stop at the roof. Hail, straight-line wind, tornadoes, and hurricane remnants drive water into walls, ceilings, and older intown homes. Carriers often price the visible damage instead of the full repair. Our Atlanta public adjusters document the entire loss, manage the carrier, and get paid only when you recover.
 Hail, wind, tornado & hurricane remnant claims
Water intrusion, burst pipes & hidden moisture
Fire, smoke & tree-fall damage
No recovery, no fee — zero upfront cost
We only get paid when you do.
Tell us about your property and the damage. We'll review it at no cost.
No upfront cost. We only get paid if you recover. Licensed Georgia public adjuster.
Results vary by claim. Figures reflect JustClaims claim experience.
Georgia sets specific timelines for claim handling and caps what a public adjuster can charge. Here is the framework — general information, not legal advice. If the insurer needs more time, it must tell you within five business days after the deadline, with reasons and an estimated date.
Your insurer must acknowledge your claim within 15 days of notice under Ga. Comp. R. & Regs. r. 120-2-52-.03(1).
For fire and extended-coverage policies, the insurer must affirm or deny coverage within 60 days of receiving a completed proof of loss. r. 120-2-52-.03(3).
Once coverage and the amount are confirmed and undisputed, payment is due within 10 days. r. 120-2-52-.03(4).
Georgia caps a public adjuster's total commission at 33.3% of the insurance settlement. A narrow 72-hour exception applies when the insurer pays or commits in writing to pay the policy limit. Contracts must use a Commissioner-approved form. Verify a Georgia license.
JustClaims provides public adjusting services, not legal advice. Policy terms and current Georgia law control. Consult a licensed Georgia attorney for legal questions.
Atlanta's mix of older housing stock, mature tree canopy, and frequent convective storms creates losses that are rarely limited to one trade. Hail starts on the roof; wind opens the envelope; water finishes the damage inside.
Hail bruises shingles, dents soft metals, and breaks the seals that keep water out. We document the full roof system and the interior damage that follows — not just the shingles a carrier's inspector circles.
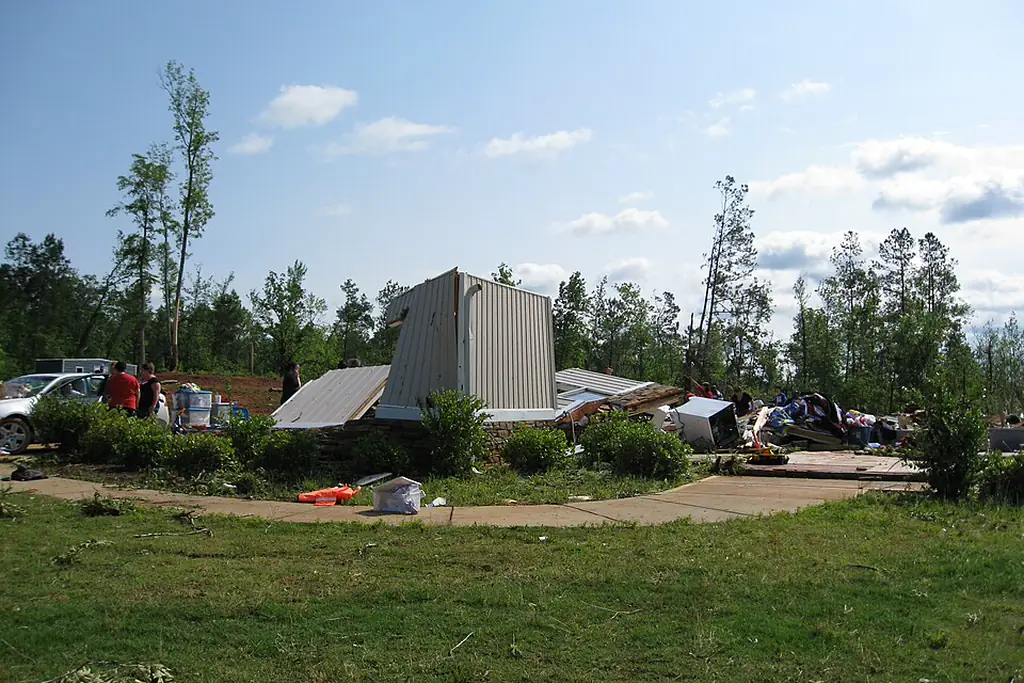
Straight-line wind and tornadoes lift roofing, break windows, and drop trees onto structures. We scope the building envelope, structural damage, and debris removal as one claim so the cause and the repair stay connected.
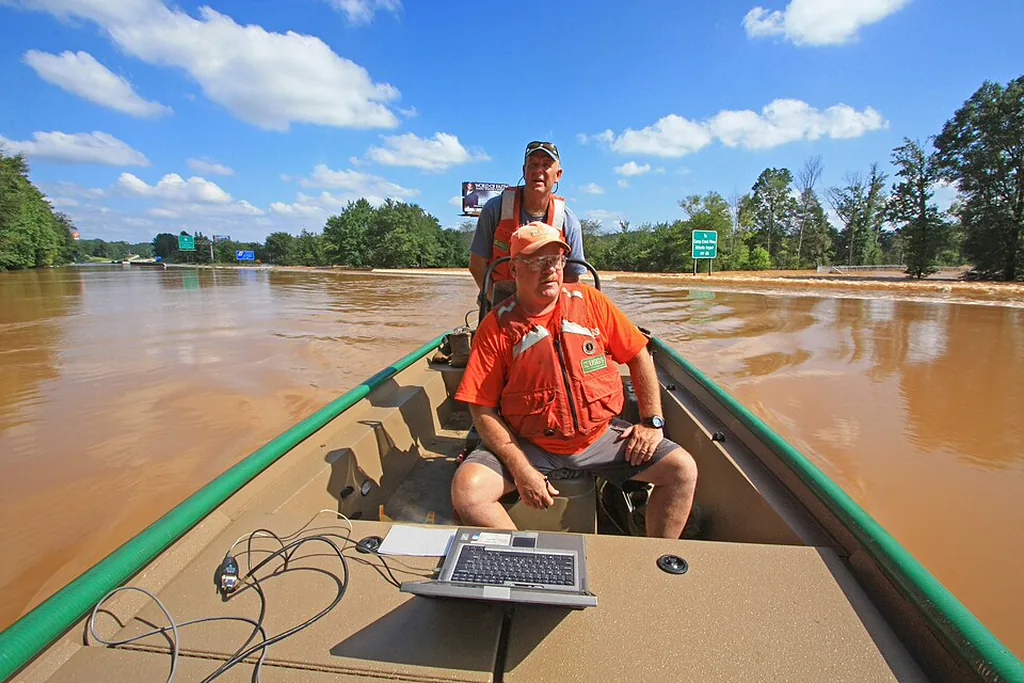
Hurricane remnants can push days of rain through roofs, windows, and foundations. Carriers may call the result "seepage" or "maintenance." We document the storm opening, the moisture path, and the full interior repair.
The carrier's estimate is below your contractor's bid
Damage is labeled "wear and tear," "maintenance," or "seepage"
Water or smoke damage is scoped as cleaning only
The adjuster missed hidden moisture, code upgrades, or matching
The settlement won't cover the full repair
Atlanta's mix of older homes, new construction, storms, water, fire, HOA, and commercial property creates claims that rarely fit a single template.
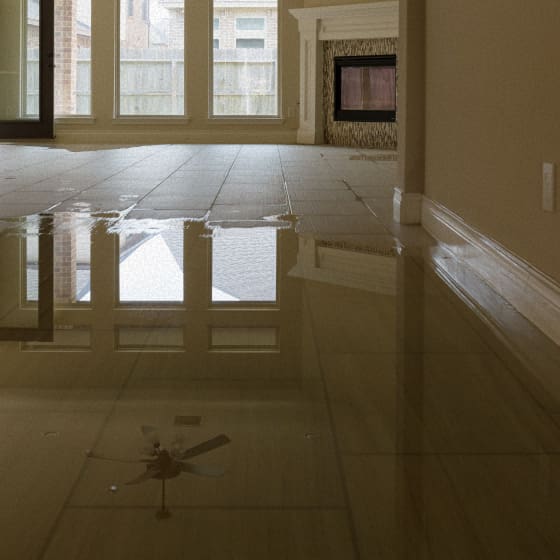
Burst pipes, supply-line failures, and storm-driven intrusion — documented before the carrier calls it maintenance.
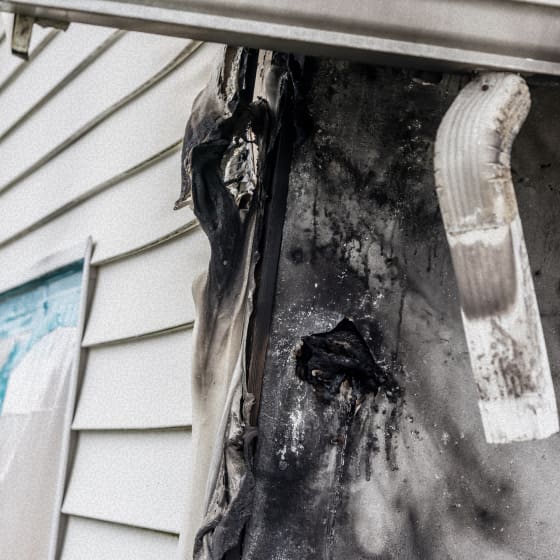
Structure fires, smoke travel, and ash damage scoped for full repair and cleaning, not a carrier minimum.
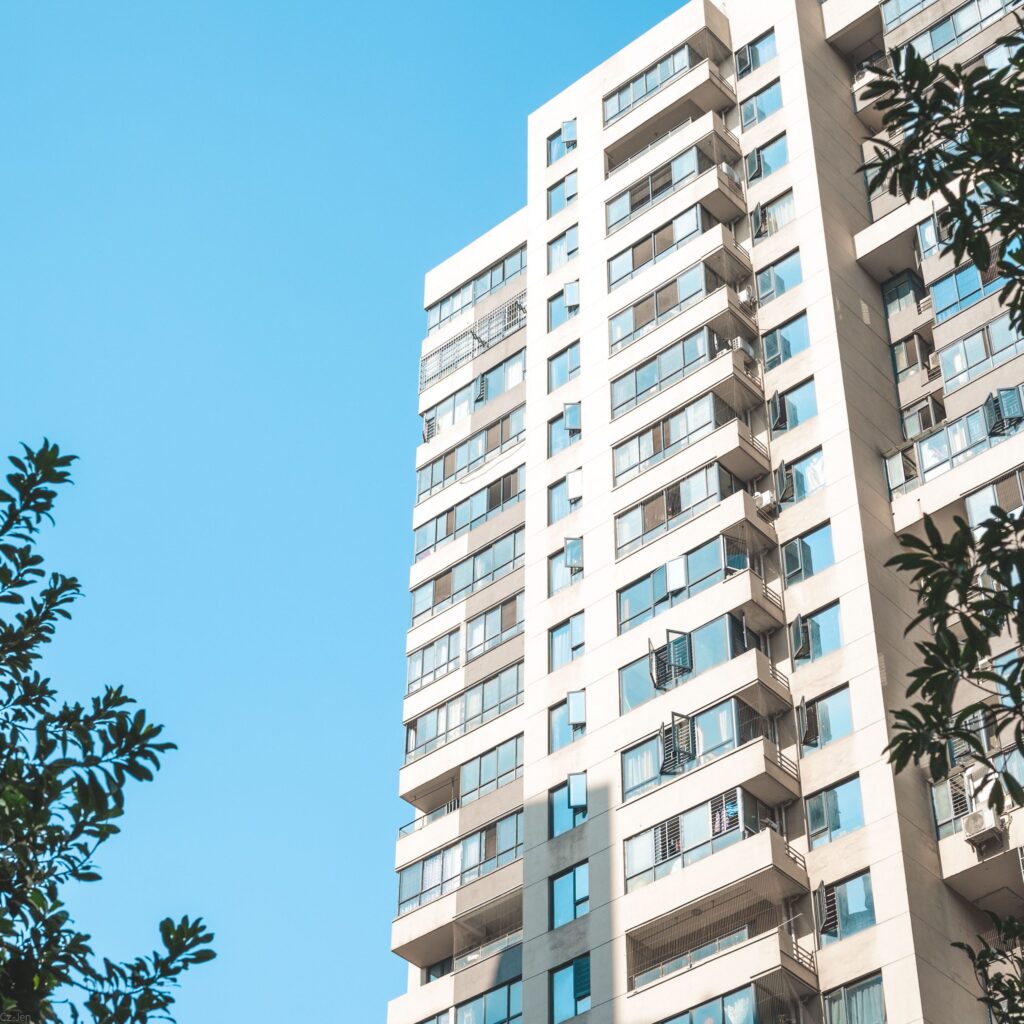
Master-policy gaps, loss assessments, and shared-structure damage in Atlanta condos and HOA communities.
Business property, lost income, and mixed-use building claims for Atlanta owners and operators.
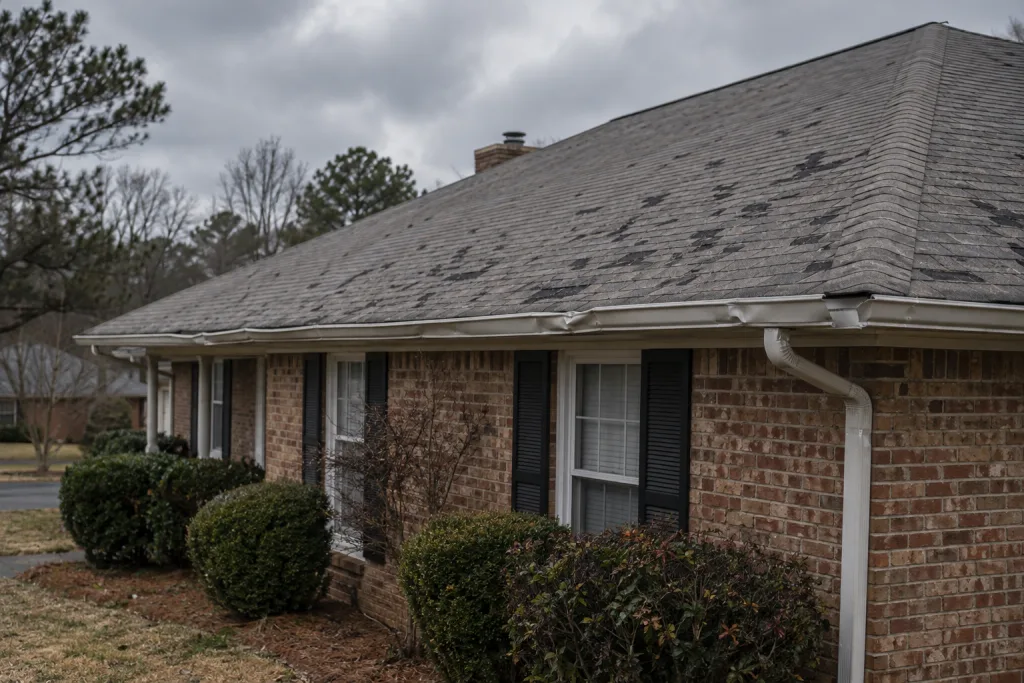
Code-sensitive repairs, matching, and plaster-and-lath construction in Atlanta's older intown homes.
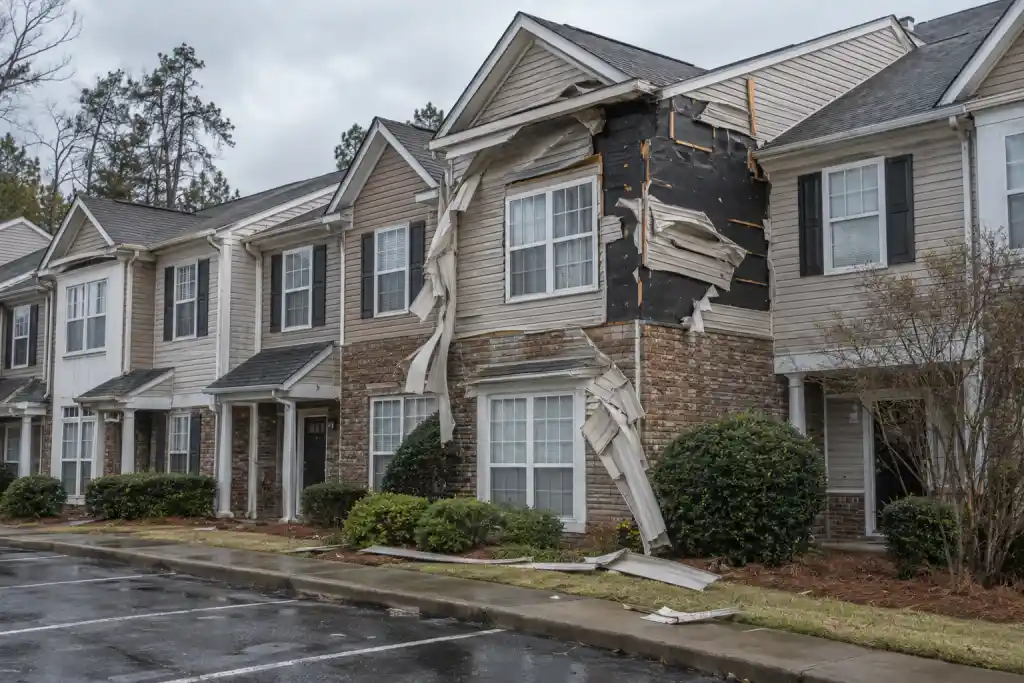
Shared walls, landlord and tenant coverage, and rental income losses in Atlanta townhomes and rentals.
We represent policyholders only. From the first inspection to the final settlement, we handle the carrier so you can focus on the property.
We reopen the estimate, document what the carrier missed, and negotiate the full scope of repair.
We manage the carrier's requests, deadlines, and follow-ups so the file keeps moving.
We challenge unsupported "wear and tear," "maintenance," or "cosmetic" findings with evidence.
Single-family homes
Historic & intown homes
Condos & townhomes
HOA communities
Rental properties
Multi-family buildings
Commercial & retail
New construction
No upfront cost. We only get paid when you recover.
Tell us what happened. We review your policy and damage at no cost and tell you honestly whether a public adjuster adds value.
Start your free claim review →
We inspect, photograph, and scope every line item, then present a complete, evidence-backed claim to your insurer.
We handle the back-and-forth and push for the full amount your policy owes. You only pay when you recover.

Taylor Bezek has spent over a decade representing policyholders on residential, commercial, and large-loss property claims. He leads JustClaims' Georgia claims practice and works directly with Atlanta owners on storm, hail, wind, hurricane, water, and fire losses. His approach is documentation-first: build the scope from the damage up, answer the carrier's likely objections before they are raised, and keep the policyholder in control of the claim. Taylor is a licensed Georgia public adjuster and works only for policyholders — never the insurance company.
Roofers, restoration companies, and general contractors trust us to document the loss and align the scope so their customers' claims get funded.
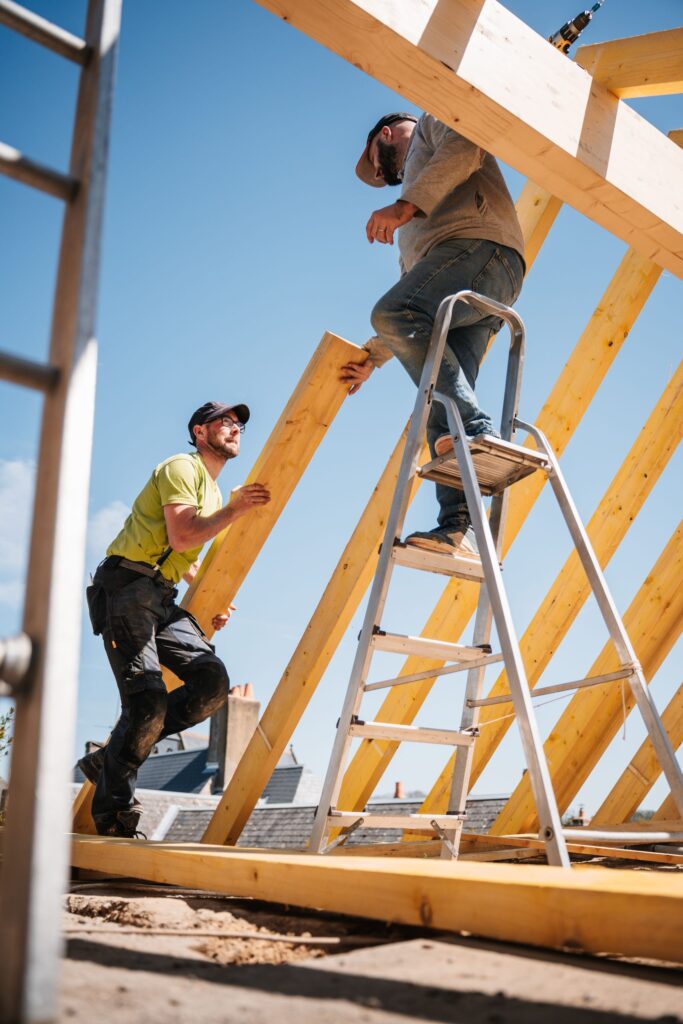
Hail, wind, and storm roofing claims documented to full replacement where the policy allows — with the interior damage included.
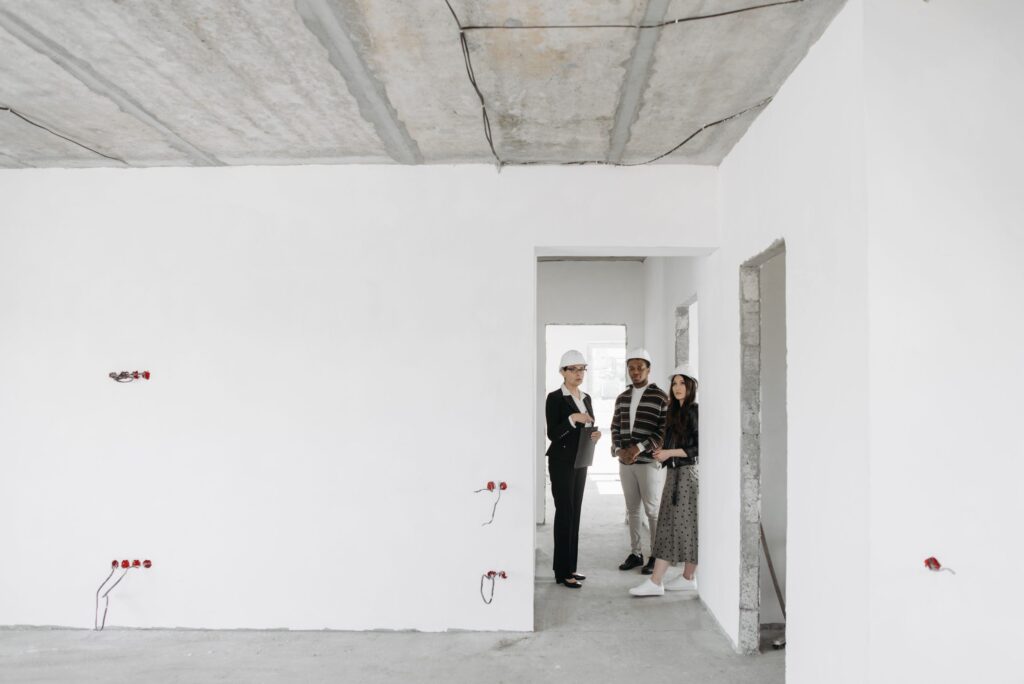
Water, fire, and smoke mitigation scoped correctly from day one, so the repair estimate and the claim tell the same story.

We handle the insurance paperwork and negotiation so your scope of work gets approved and funded.
We represent policyholders across Fulton, DeKalb, Cobb, and Gwinnett counties — from intown Atlanta to the northern suburbs.
Photograph every affected room and elevation before anything is moved or repaired. Capture wide shots, close-ups of damage, the roof from a safe angle, water lines, damaged contents, and any contractor estimates or notices. Keep a dated log of the damage and every receipt. Do not make permanent repairs before the insurer inspects unless you need to prevent further damage; document that work as well.
An assignment of benefits transfers your right to pursue the claim to the contractor. Georgia does not ban AOBs, but signing one can limit your control over the settlement and creates risks if the contractor performs poorly or the insurer disputes the work. Read the entire document, confirm the price and scope, and consider whether you can keep control of the claim instead. This is general information, not legal advice.
In most cases, your own homeowner policy responds to damage to your structure, even when the tree came from a neighbor's yard. The neighbor's liability coverage may apply if their negligence caused the tree to fall, but that is a separate claim and often harder to prove. Debris removal and repair coverage depend on your policy. Report the loss to your insurer promptly and document the tree, the damage, and the weather.
You still own the claim. A public adjuster prepares the estimate, documents the loss, and negotiates with the insurer on your behalf, but the policy remains yours and you approve the final settlement. A licensed Georgia public adjuster must use a Commissioner-approved contract and may not exceed the state's fee cap. Ask for the contract, the fee terms, and a clear explanation of what the adjuster will handle before you sign.
Your insurer may recommend a network contractor or a preferred vendor, but it cannot require you to use one for covered repairs. You can choose your own licensed contractor and get your own estimates. If the insurer insists on a specific vendor, ask for that requirement in writing and compare the scope and price. The policy controls the covered repair, not the contractor's identity.
Renters policies typically cover personal property for covered perils such as wind, hail, fire, and sudden water damage, subject to the policy's limits and deductible. The landlord's policy generally covers the building, not your belongings. Document damaged items with photos and receipts, report the loss promptly, and check whether your policy has replacement-cost or actual-cash-value coverage before you throw anything away.
It only takes a few minutes. No upfront cost. We only get paid when you do.
Georgia-licensed public adjuster · Contingency fee, no upfront cost · Serving Atlanta and metro Georgia