



Washington State Public Adjusters
Wildfire, windstorm & water damage claims from Seattle to Spokane — no recovery, no fee.
We help Washington State property owners recover the full payout they’re owed — and step in when the carrier underpays, delays, or denies. Licensed and bonded in Washington, including the $5,000 surety bond required by RCW 48.17.430.
We specialize in wildfire, windstorm, and water claims — the claims carriers most often underpay.
Types of claims we handle in Washington.
Wildfire east of the Cascades and smoke damage statewide, Puget Sound windstorms, atmospheric-river rain, ice dams in the colder zones — and the commercial claims carriers underpay most.

Cabins & Rural Homes
Smoke and ash damage written off as surface-only; contents, ductwork, and full remediation scope undervalued.

Single-Family Homes
Wind-driven rain blamed on flooding or wear; roof and siding scopes cut to patch repairs.

Condos & Townhomes
Atmospheric-river rain and water intrusion disputed as excluded flood; tear-out, drying, and mold remediation undercounted.

Older & Historic Homes
Smoke damage past the burn area ignored; code-upgrade and restoration costs left out of the estimate.

Mountain & Inland Homes
Ice-dam leaks and burst pipes blamed on maintenance; insulation, drywall, and flooring damage underpaid.

Retail, Office & Warehouse
Large-loss scopes cut; depreciation, overhead-and-profit, and business-interruption games.
Not sure your offer covers the real damage?
Get a Free Claim ReviewUnderpaid, disputed, or stuck?
Washington carriers reach for the same three moves from Seattle to Spokane. We fight all three.
Was your wildfire or smoke claim underpaid?
Smoke and ash damage minimized, contents undervalued. We rebuild the scope from the actual loss — and your insurer must finish its investigation within 30 calendar days (WAC 284-30-370).
Did they blame the wrong peril?
Wind-driven rain gets blamed on excluded flood, and covered damage walks. We document the storm, the entry points, and what the policy actually covers.
Is your claim stuck?
Insurers must acknowledge your claim within 10 business days (WAC 284-30-360), and Washington law bars them from discriminating against you for hiring a public adjuster (WAC 284-30-330(14)).
JustClaims vs. the insurance company’s adjuster.
Washington law lets you hire your own licensed adjuster to level the playing field. Here is how the three options stack up.
Washington law bars insurers from discriminating against you for hiring a public adjuster — and requires them to recognize your adjuster as your legal representative (WAC 284-30-330(14)).
Run the math on your Washington policy.
These are the numbers carriers hope you never run. Washington law puts each one in writing — and they are exactly what we hold insurers to.
Every Washington public adjuster must file and maintain a $5,000 surety bond with the Insurance Commissioner (RCW 48.17.430). Ask to see it.
Your insurer must acknowledge your claim — and reply to your messages — within 10 business days (WAC 284-30-360).
The insurer has 30 calendar days to complete the investigation after you report the claim. Longer requires a written explanation and updates every 30 days (WAC 284-30-370).
Once you sign settlement or release documents, payment is due within 15 business days (WAC 284-30-330(16)).
How Washington property owners work with JustClaims.

Free claim review
We review your policy and damage for free — and tell you straight if hiring us is worth it.

Documentation & independent estimate
A Washington-licensed adjuster documents the full loss with an independent estimate — before the carrier’s number sticks.

Negotiation with the carrier
We negotiate directly with your insurer — and hold them to Washington’s claim deadlines.

Settlement & payment
The carrier pays, and our fee comes out of the recovery. We only get paid when you do.
Talk to us before the carrier’s adjuster writes the first estimate.
Get a Free Claim ReviewWhy Washington owners call JustClaims.
We lead with credentials, not made-up dollar figures: a Washington-licensed, bonded public adjusting firm with a Spokane office live now, serving wildfire, smoke, water, and fire claims statewide.
A name Washington owners trust.
From Spokane to the Seattle metro, JustClaims represents Washington policyholders only — never insurance companies.

Licensed in Washington.
Taylor Bezek, Washington public adjuster license #1375243 (individual), with JustClaims agency license #1377355.
Verify us with the state.
Check our licenses free at the Washington OIC license lookup before you sign anything.
Bonded and local.
We carry the $5,000 surety bond Washington requires of every public adjuster (RCW 48.17.430). Our Spokane team serves Eastern Washington, with Seattle-metro coverage.
No recovery, no fee.
Your claim review is free, and there is no retainer or hourly billing. We are paid only when you recover.
Want a licensed Washington team that works only for you?
Get a Free Claim ReviewWhat Washington policyholders need to know.
→ Your public adjuster is your legal representative
Washington insurers may not discriminate against you for hiring a public adjuster — and they must recognize your adjuster as your legal representative (WAC 284-30-330(14)).
→ 30 days to accept or deny
The carrier must accept or deny your claim within 30 calendar days of notification, and any denial must state the specific policy basis in writing (WAC 284-30-380(1), effective Oct 18, 2026).
→ 5 days on emergency mitigation
Your insurer must approve — or itemize its rejection of — your emergency mitigation scope within 5 business days (WAC 284-30-330(20)-(21), effective Oct 18, 2026).
→ They must show their numbers
On your request, the insurer must disclose the date, source, and businesses behind any pricing database or estimating software used on your claim (WAC 284-30-380(8), effective Oct 18, 2026).
Washington law sets the deadlines. We make sure the carrier keeps them.
Get a Free Claim ReviewThis is general information, not legal advice. Statutes and fees change. Confirm the specifics for your situation.
We serve all of Washington.
Choose your market for details. Our Washington team serves homeowners and businesses from the Seattle metro to Spokane, Tacoma to the Columbia River — wildfire country to the coast.
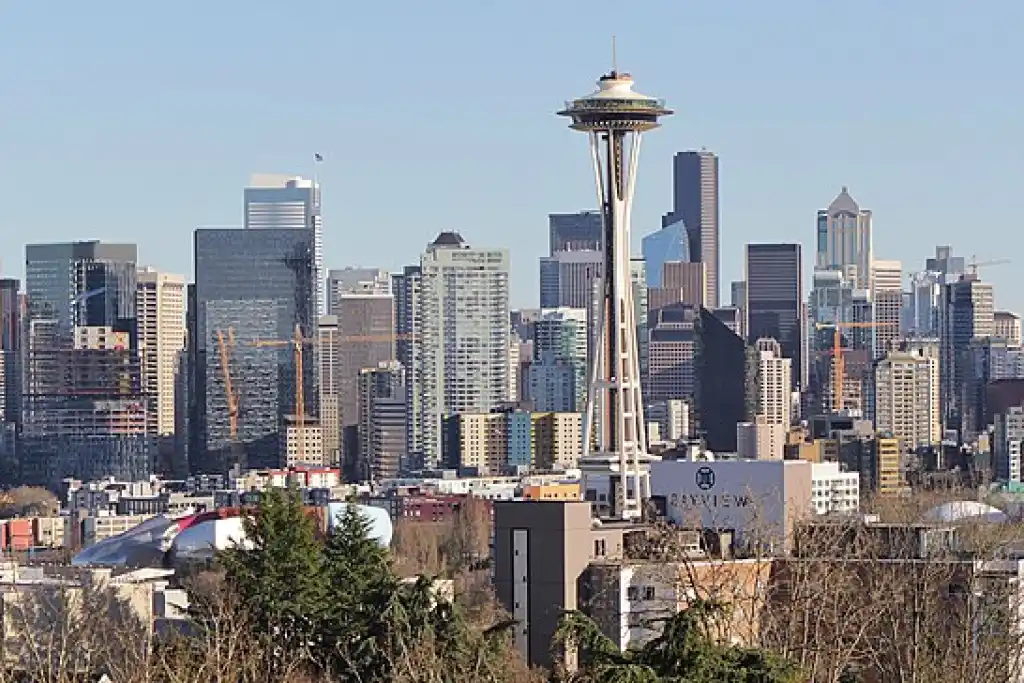
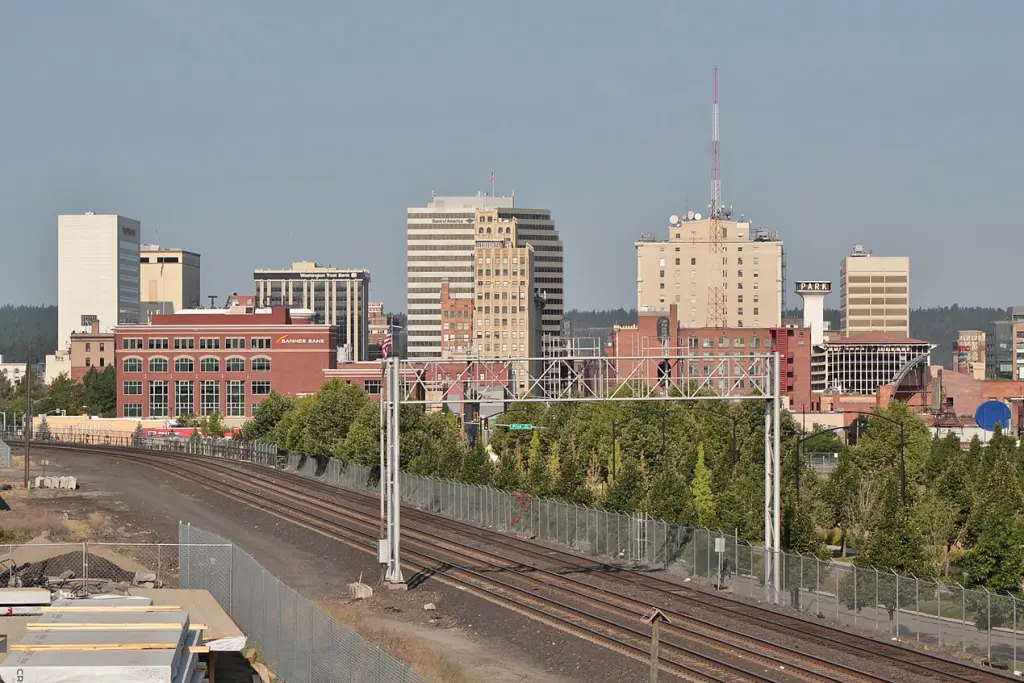
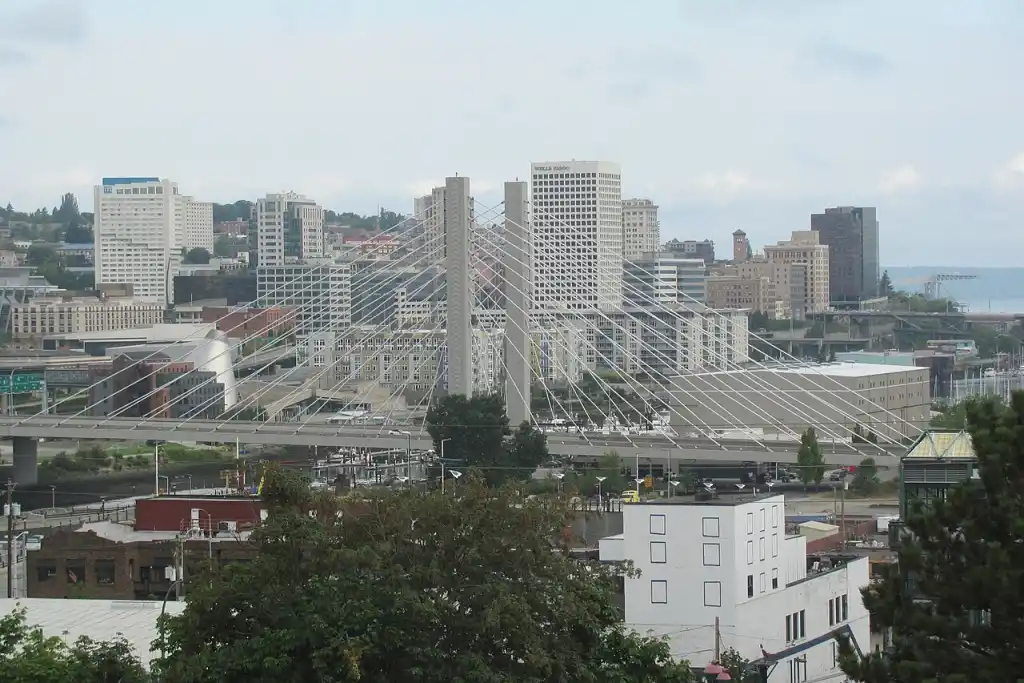
Three Washington markets. One team.
Spokane is live now, serving Eastern Washington — with Seattle and Tacoma coming soon under one licensed Washington team.
Spokane
Eastern Washington’s largest city — wildfire, wind and ice dam claims across the Inland Northwest.
Seattle
Puget Sound’s metro core — wind, water and fire claims from Ballard to West Seattle.
Tacoma
South Sound port city — wind, water and fire claims for homes and businesses.
Coming Soon
From our public adjusters across Washington
Meet our Washington lead public adjuster

Taylor Bezek
As General Manager at JustClaims, Taylor Bezek leads our Washington claims practice, with our Spokane office serving policyholders statewide. A licensed Washington public adjuster (#1375243), he has handled complex wildfire, smoke, wind, and water claims — from the Cascades to the Palouse — with deep experience in commercial and large-loss property. Taylor founded his own firm before joining JustClaims to scale a tech-forward approach for Washington policyholders, pairing local claims expertise with AI to drive faster, clearer, and fuller settlements. He works only for policyholders — never the insurance company — and holds public adjuster licenses in multiple states, each listed below.
Washington claim questions,
answered.
Overhead and profit is generally owed when a loss is complex enough to require a general contractor coordinating multiple trades — which describes most larger structural repairs. Carriers often strip it from the first estimate or call the job too simple for it. Whether it is owed depends on the real scope of work, not the carrier's first draft, which is why a line-item review matters.
Under WAC 284-30-330 as amended effective October 18, 2026, an insurer must approve a first-party mitigation scope — or itemize what it rejects — within 5 business days. That gives restoration contractors a clearer path to start dry-out and stabilization without weeks of silence. Keep the scope itemized and documented so the timeline and the paper trail both work in your favor.
Photograph everything before anything is disturbed — wide shots of each room, close-ups of the damage, and moisture readings when water is involved. Keep a log of what was removed, when, and why, and set damaged materials aside in case the carrier wants to inspect. Solid documentation is what turns a disputed scope into an agreed one.
Business interruption coverage is designed to replace lost income — and often extra expenses — while your property is repaired after a covered loss. The hard part is proving the number: the carrier will model downtime and revenue its own way, and that model is usually conservative. We build the financial documentation, tie it to the repair timeline, and negotiate from your records rather than theirs.
All three play a role, but they do different things. The board makes the decisions, the manager coordinates logistics, and a public adjuster builds and negotiates the claim itself — the scope, the valuation, and the settlement — on the association's behalf. On a large or disputed loss, that lets the board and the manager stay in their lanes while a licensed adjuster runs the claim.
Yes. Under WAC 284-30-380 as amended effective October 18, 2026, if the insurer used a database, survey, estimating software, or benchmarks for material pricing or labor rates, you can request the date and source of that data and which businesses supplied the cost information. On large losses, where outdated or out-of-area pricing is a common reason estimates come in low, that transparency matters.
Washington's fair-claims rules set firm deadlines for insurers. They must acknowledge your claim within 10 business days (WAC 284-30-360), complete their investigation within 30 calendar days (WAC 284-30-370), and accept or deny it within 30 calendar days of being notified (WAC 284-30-380, effective October 18, 2026). Payment is due within 15 business days after signed settlement documents (WAC 284-30-330(16)), and it is an unfair practice for an insurer to discriminate against you for hiring a public adjuster (WAC 284-30-330(14)).
A public adjuster works for you, not the insurance company. We inspect and document the full scope of damage, prepare the estimate, handle the correspondence, and negotiate the settlement under your policy. Washington public adjusters are licensed and must maintain a $5,000 surety bond with the Insurance Commissioner (RCW 48.17.430).
Most people bring one in when the damage is significant, the claim is complex, or the carrier's offer doesn't match the real cost of repairs. Earlier is usually better — recorded statements, signed releases, and quick settlements can limit your options before the full scope is known. A claim review is free, so there is no risk in asking first.
Be careful. Stick to facts you can verify — what happened, when, and what was damaged — and avoid guessing about causes or downplaying anything. Statements recorded early, before the full damage is documented, can be used later to limit or deny a claim. It is usually wise to get advice before you record one.
It may. Many Washington homeowners policies include additional living expense (ALE) coverage, which can pay for temporary housing and extra costs when a covered loss makes your home unlivable. Whether an evacuation triggers ALE depends on your policy language, so have the policy reviewed before you assume it is covered — or that it isn't.
Still have questions about your Washington claim? We're happy to help.
Get a Free Claim ReviewGet a Washington adjuster on your side.
It only takes a few minutes to request a free review of your Washington claim. No recovery, no fee.
Licensed Washington public adjusters · No recovery, no fee