


New York Public Adjusters
Get the full payout your policy owes, across the five boroughs and Long Island.
From pre-war co-ops in Manhattan to commercial buildings in Brooklyn and Queens to homes on Long Island, we help property owners, boards, and managing agents recover the full insurance payout after water, fire, wind, flood, or storm damage. When the carrier underpays, delays, or denies, we step in. No upfront cost. We only get paid when you do.
New York's commercial buildings and co-op/condo communities lose the most to lowball payouts. That's the fight we specialize in.
We serve the five boroughs and Long Island
Choose your market for details. Our New York team handles co-op and condo board claims, commercial property, and storm, water, and flood losses across the city and out onto Long Island.
Why New York properties need a public adjuster.
NYC's dense, aging building stock generates complex water, fire, and storm claims, and insurers lean on scopes that come in below full replacement cost, especially on co-op, condo, and commercial buildings. A public adjuster is licensed by the New York Department of Financial Services to represent only the policyholder, never the carrier.
Your Public Adjuster
Works only for you. We step in when the carrier underpays, delays, or denies. We review the policy, document the full loss independently, file or reopen the claim, and negotiate for the maximum recovery your policy supports.
The Insurer's Adjuster
Works for the insurance company. They assess your loss in the carrier's interest. On co-op, condo, and commercial property in particular, the first offer rarely reflects the full scope, especially with water damage that spreads between units.
JustClaims serves all of New York.
Our New York team is led by a DFS-licensed public adjuster handling co-op and condo board claims, commercial property, and storm, water, and flood losses across the five boroughs and Long Island.
Types of claims we handle in New York.
Our primary focus is co-op, condo, and commercial property, where carriers underpay most. We pair every property type to the damage and the dispute we see again and again across the boroughs.

Co-op & Condo Buildings
Master policy vs. unit coverage; water spreading between units undercounted
Pre-war & Multi-Family
Burst-pipe and ice-dam damage classed as maintenance, not sudden loss

Commercial & Mixed-Use
Business-interruption and code-upgrade costs left out of the estimate
Retail & Hospitality
Lost income and contents undervalued; scope cuts on build-back
Coastal & Flood-Zone Property
Wind vs. flood causation (Sandy, Ida); NFIP vs. policy coverage split
Homeowners & Brownstones
Depreciation games and undocumented hidden damage
Not sure if your damage qualifies?
Get a Free Claim ReviewUnderpaid, delayed, or denied?
New York carriers reach for the same three moves across every borough. We fight all three.
Did they underpay you?
Lowball estimates and missed damage, especially water that spreads between units. We rebuild the number from the actual loss and document the full scope independently.
Is your claim stuck?
Silence, re-inspections, endless requests. We keep the file moving and hold the carrier to the Regulation 64 claim-handling timelines.
Were you denied?
A denial isn't the end. We review the policy, document what's covered, and re-submit with independent evidence. New York requires carriers to explain a denial in writing.
How New York owners and boards work with JustClaims.

Free claim review
We assess your policy and your damage at no cost and tell you straight whether you need a public adjuster.

Independent Documentation
A DFS-licensed adjuster inspects and documents every covered loss, with AI-assisted tools, including water damage that spreads between units.

Filing & negotiation
We file or reopen your claim and negotiate directly with the carrier, holding them to New York's claim-handling timelines.

You recover
Once the claim settles, our fee comes out of the recovery. No recovery, no fee.
Boards and managing agents: we present the full scope on behalf of the building.
Get a Free Claim ReviewWhat New York policyholders need to know.
→ Public adjusters are licensed by DFS
New York public adjusters are licensed and regulated by the Department of Financial Services under NY Insurance Law §2108, which requires a $1,000 surety bond, prelicensing education, and an exam. You can verify any adjuster through the DFS license lookup.
→ Fees are capped and contingency-based
New York caps public adjuster fees at 12.5% of the recovery (11 NYCRR §25.7, Regulation 10). The fee must be in writing, and you may cancel the contract by midnight of the third business day after signing. No recovery, no fee.
→ Claim-handling timelines (Regulation 64)
Your insurer must acknowledge your claim within 15 business days, and accept or reject within 15 business days of receiving a properly executed proof of loss. Extensions require a written explanation, and an agreed settlement must be paid within 5 business days.
→ No conflict of interest, and good faith required
Under §2108, a public adjuster cannot have a financial interest in the repair or restoration of your claim. And under §2601, carriers must handle claims in good faith, unreasonable delay or underpayment can carry consequences.
Think your claim was handled in bad faith?
Get a Free Claim ReviewThis is general information, not legal advice. Statutes and fee rules change. Confirm the specifics for your situation.
The five boroughs and Long Island, one New York team.
Long Island
Nassau and Suffolk homes, co-ops, condos, and commercial property, with heavy coastal wind and flood exposure. Our largest single New York market by demand.
Coming Soon
Manhattan
Co-op and condo board claims, pre-war buildings, and commercial property from Downtown to Harlem.
Live
Brooklyn
Brownstones, multifamily, and mixed-use commercial, with coastal flood exposure across Canarsie, Mill Basin, Gravesend, and Coney Island, plus Bed-Stuy.
Coming Soon
Queens
Multifamily and commercial across the borough, including Corona, with flood and wind exposure (Ida, Sandy).
Coming Soon
Meet our New York lead public adjuster
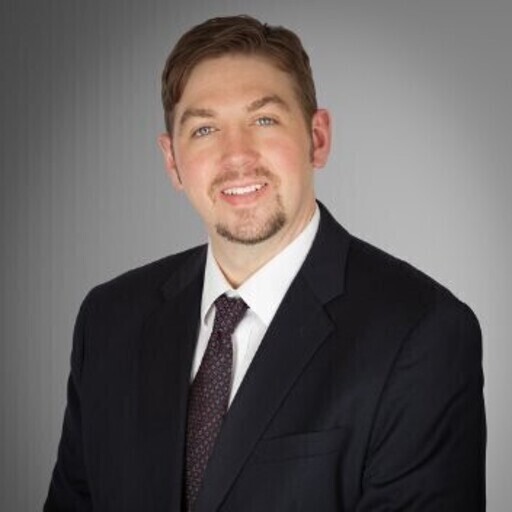
Collin Corcoran
Experienced Public Adjuster and Property Claims Specialist, Collin is licensed in New York (#1603393), New Jersey (#3003700204), and Connecticut (#19820270). With 20+ years of hands-on construction and property damage experience, he specializes in residential and commercial claims, complex loss inspections, policy review, detailed estimating, and strategic negotiation. Collin's background in construction, asset management, emergency response, and claims documentation allows him to accurately identify damage, understand repair requirements, and advocate effectively for policyholders. He works with homeowners, business owners, contractors, and insurance professionals to move claims forward with clarity, accuracy, and confidence. Collin is committed to transparency, technical precision, strong communication, and securing fair outcomes for policyholders.
Frequently Asked Questions
No. In New York, only a licensed public adjuster or attorney can negotiate your insurance claim. A public adjuster also cannot have a financial interest in the repairs, which is exactly why the role stays independent. If a contractor offers to "handle" your claim, that's a flag worth checking.
Yes. Scope cuts are exactly what we fight. We document the full extent of the damage, justify the line items the carrier removed, and negotiate to get the scope and pricing restored, so the approved scope matches what the job actually requires.
You send us the owner, board, or managing agent and the claim details, we take the insurance side, and you stay focused on the work. We keep you in the loop at every step. Because New York prohibits a public adjuster from having a financial interest in the repairs, we keep the arrangement clean and compliant.
JustClaims works with property owners, boards, and managing agents across New York to review the offer independently, document the full scope of the damage, and present a supported claim to the insurer. Large multi-unit and commercial losses are frequently underscoped on the first estimate. We handle the insurance side at no upfront cost.
A public adjuster is licensed by the New York Department of Financial Services to represent only the policyholder, never the insurance company. We review your policy, inspect and document all damage independently, prepare the claim, and negotiate the settlement on your behalf. Your insurer has its own adjuster working in its interest. We work for you.
New York caps public adjuster fees at 12.5% of the recovery (11 NYCRR §25.7, Regulation 10). The fee must be stated in writing, and you may cancel the contract by midnight of the third business day after signing. JustClaims works on contingency, no upfront cost, no fee unless we recover or increase your settlement.
Yes. We can step in at any stage: before filing, while the claim is open, or after a settlement you believe was inadequate. If additional damage has been identified since the original settlement, your policy may allow further submission, subject to its specific terms. The initial review is free.
Under New York's Regulation 64 (11 NYCRR 216), your insurer must acknowledge the claim within 15 business days, and accept or reject within 15 business days of receiving a properly executed proof of loss. If they need more time, they must explain why in writing. An agreed settlement must be paid within 5 business days.
That depends on the cause of the loss and on what your own policy covers versus the building's policy. Renters and unit owners are often surprised that damage to their contents and interior finishes falls to their own coverage. We identify which policy applies, document the full loss, and pursue it so nothing is missed.
Yes. Coastal New York and Long Island see heavy flood exposure (Sandy, Ida), and flood is typically covered separately from your homeowner or property policy, often through the federal National Flood Insurance Program (NFIP). Flood claims have their own proof-of-loss rules and tight deadlines. We document the full flood loss and help you pursue it correctly.
No. A denial is not final, and New York requires the insurer to explain it in writing. We review the basis for the denial, identify grounds for reconsideration, and re-submit with independent documentation. You can also contact the DFS Consumer Assistance Unit if you believe the denial was improper.
The trade-off is the fee: in New York it is capped at 12.5% of the recovery (11 NYCRR 25.7), so it comes out of what you collect. If your claim is small, clearly covered, and already paid in full, you may not need one. A public adjuster earns their place on disputed, underpaid, or complex losses where the scope is in question.
Confirm the adjuster holds a current New York public adjuster license from the Department of Financial Services, and get the agreement in writing with the fee stated (11 NYCRR 25.6). Ask who will actually handle your file, how they document scope, and for references on losses like yours. Avoid anyone promising a specific settlement figure.
Still have questions? We're happy to help.
Get a Free Claim ReviewFind out what your New York property claim is really worth.
It only takes a few minutes. No upfront cost. We only get paid when you do.
Licensed by the NY Department of Financial Services — JustClaims, LLC License #PA-1994667 · Contingency fee, capped at 12.5% · Manhattan · Brooklyn · Queens · The Bronx · Staten Island