The offer came in low?
Carrier estimates price the visible room and skip the party-wall spread and hidden moisture. We rebuild the number from the actual loss.
Damage in Brooklyn rarely stays inside one property line. We document the full loss — the party-wall spread, the flat roof, the storefront below the apartments — and negotiate directly with the carrier. No recovery, no fee.
 Licensed by the NY Dept. of Financial Services — #PA-1994667
Fee capped by NY law at 12.5% — in writing before work starts
Landlord, multi-family & mixed-use claims.
We only get paid when you do.
Tell us about your property and damage. We'll review at no cost.
No upfront cost. We only get paid if you recover. Licensed New York public adjusters.
Licensed public adjusters — Brooklyn attached-housing experts
Full-loss documentation — party walls to neighboring units
Landlord, tenant & mixed-use policy expertise
Flat-roof storm proof that beats the wear-and-tear excuse
Policyholders only — never the insurance company
From Park Slope brownstones to Canarsie two-families and the storefront-and-apartments buildings along Brooklyn's avenues — we handle the full range of Brooklyn property claims.
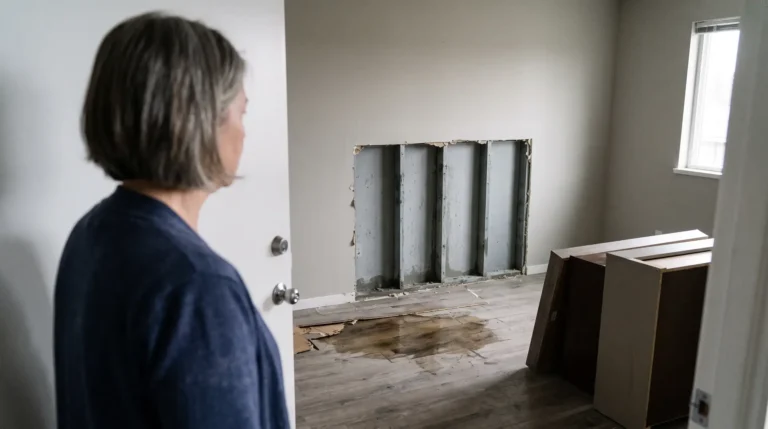
Supply-line failures, radiator leaks, and overflows that travel through party walls. Carriers price the visible room — we document the full spread.
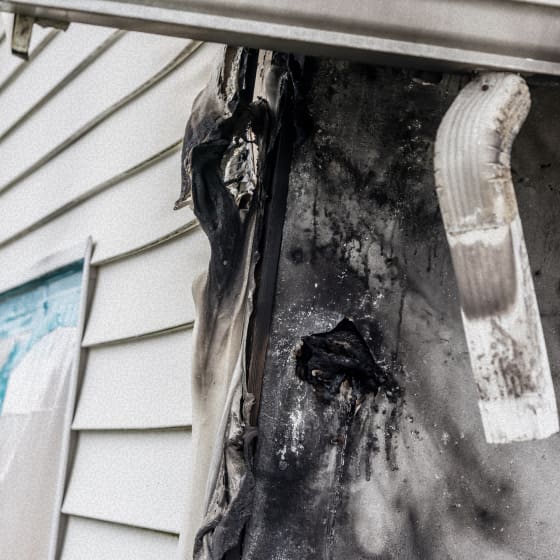
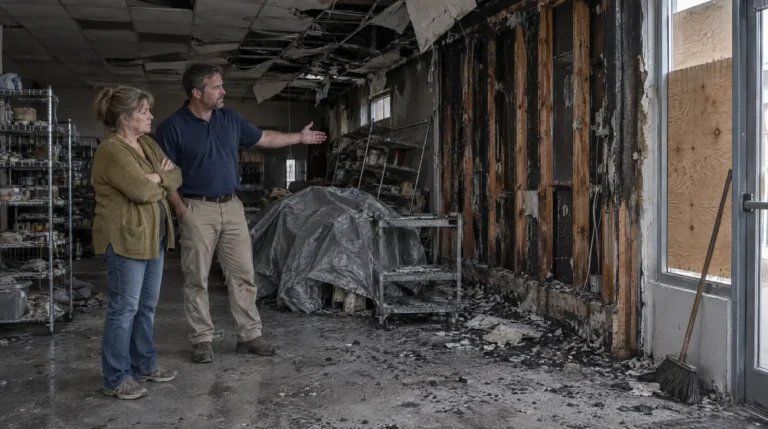
Kitchen fires, fires from the building next door, and smoke through shared walls. We scope the burn, the soot, and the water used to put it out.
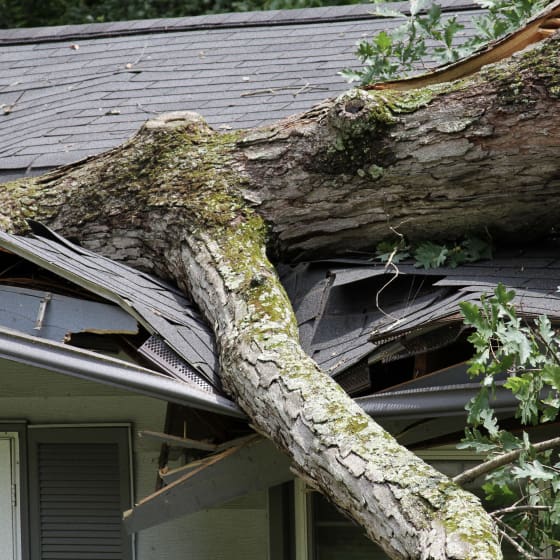
Wind peels parapet flashing and opens seams on Brooklyn's flat roofs — then the rain gets in. We prove the storm, not wear and tear.
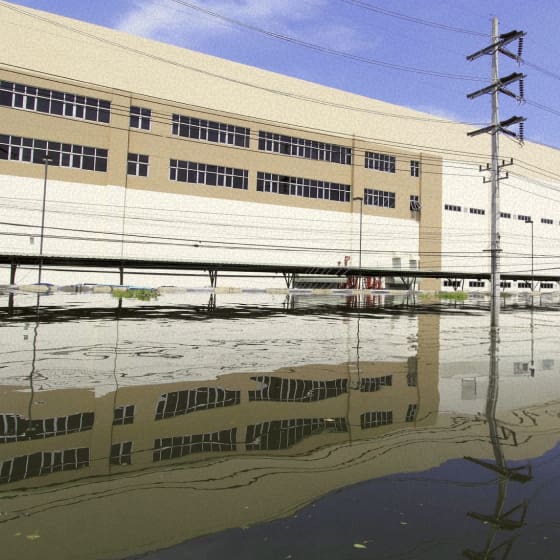
Backups through basement drains in Brooklyn's older combined-sewer blocks. We find the water-backup endorsement and document the loss.
The shop below, the apartments above — one loss, multiple coverages, plus business interruption. We run the property and income claims together.
Pre-existing damage, late reporting, maintenance reclassification — a denial letter is rarely the final word. We re-inspect and challenge it.
New York law gives property owners more leverage than most carriers volunteer. Four rules decide most Brooklyn claim fights — licensing, fee caps, deadlines, and good faith.
Anyone negotiating your claim for a fee must hold a New York public adjuster license — §2108: exam, education, and a $1,000 bond. Verify ours at the DFS license lookup.
Your fee is capped at 12.5% of the recovery (Regulation 10), in writing, with three business days to cancel. No recovery, no fee.
The carrier is on a clock: acknowledge in 15 business days, accept or reject 15 after your proof of loss, pay within 5.
§2108 bars any financial interest in your repairs — our advice stays independent. §2601 demands good faith: unreasonable delay or underpayment has consequences.
This is general information, not legal advice. Statutes and fee rules change. Confirm the specifics for your situation.
Carriers run three plays on Brooklyn claims: come in low, slow the file down, or deny and hope you go away. New York's claim-handling rules say otherwise.
Carrier estimates price the visible room and skip the party-wall spread and hidden moisture. We rebuild the number from the actual loss.
Weeks of silence, then one more photo request. Regulation 64 puts the carrier on a clock — we hold them to it.
Wear and tear, late notice, pre-existing damage — a denial is a position, not a verdict. We re-document and challenge it.
Brownstones
Row Houses
2–4 Family Rentals
Co-ops
Condos
Mixed-Use Storefronts
Walk-Up Apartments
Small Commercial Buildings
Free review. Brooklyn experts. No upfront cost.
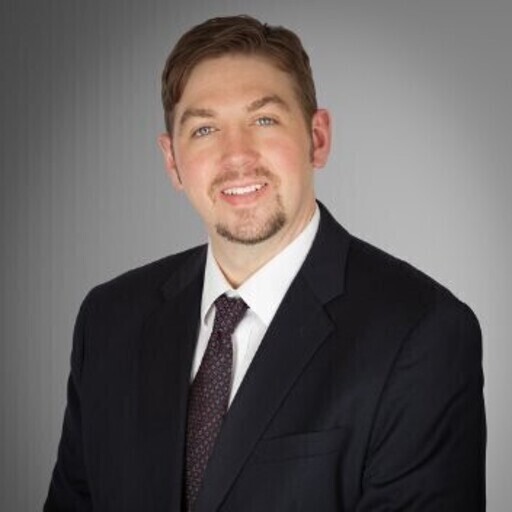
Collin Corcoran is a licensed public adjuster with 20+ years of construction and property damage experience, licensed in New York (#1603393), New Jersey (#3003700204), and Connecticut (#19820270).
In Brooklyn, his work centers on the attached housing stock — brownstones, row houses, and two-to-four-families where one burst pipe can affect owner and tenants alike. His construction background traces damage through party walls, flat roofs, and aging plumbing — and prices the plaster and millwork carriers price cheap. He works with homeowners, small landlords, and mixed-use owners: transparent communication, technical precision, no fee unless you recover.
Three steps, no upfront cost, and a licensed New York public insurance adjuster handles the carrier for you.
Send the form or call — what happened, when you found it, what the carrier said. Photos and their estimate are enough to start. Free review, honest answer.
Book your free claim review →
A DFS-licensed adjuster inspects everything — party walls, flat roof, the units above and below — and prices the real repair, not the carrier's version.
Book your free claim review →
We field every carrier request, hold them to Regulation 64 deadlines, and negotiate until the settlement matches the loss. No recovery, no fee.
Book your free claim review →Our team covers the whole borough — brownstone blocks, two-to-four-family streets, lofts and conversions, and the South Brooklyn flood zones. Same free claim review for every owner.
We quarterback the claim, keep you in the loop, and stay out of the repair work — New York bars any financial interest in the restoration, so the relationship stays clean. Your customer stays yours.
Water mitigation, fire cleanup, and board-up firms working Brooklyn's brownstones and small apartment buildings.

Plumbers, renovation GCs, and multi-family rebuild teams — radiator work to full brownstone gut renovations.
Flat-roof and facade crews — membrane and flashing repairs, parapet work, and the storm openings carriers call wear and tear.
Usually yes — a landlord (dwelling fire) policy covers fire damage to the building, including tenant-caused fires, plus lost rent while the unit is uninhabitable. The fights are scope: smoke spread into the second unit, code updates, and the rent-loss period. We document what the first estimate skipped.
Yes — it's one of the most common Brooklyn roof disputes. A storm that lifts flashing or opens a seam is a sudden, covered event even on an older membrane. We prove it with storm dates, membrane condition around the opening, and moisture mapping.
Almost always. Your own policy covers smoke damage to your brownstone even when the fire started next door — recovery against the neighbor is your carrier's problem, not yours. Smoke travels party-wall cavities and HVAC pathways; we document the full spread.
Often yes — through the water-backup endorsement on your commercial or landlord policy, which many Brooklyn owners carry without knowing it. Where the water entered decides everything; we document the entry point and tie the loss to the covered backup.
A denial is a position, not a final answer — New York requires the reasons in writing, and that letter is where the challenge starts. We re-document with weather data, moisture mapping, and a proper inspection tying the damage to a sudden event.
Yes — a core part of our Brooklyn work. One loss can touch the storefront, the apartments, and the shared systems under different coverage parts. We run the building, contents, and business-interruption pieces together so nothing falls between policies.
It takes a few minutes to find out. No upfront cost — we only get paid when you do.
Licensed by the New York Department of Financial Services · Contingency fee capped at 12.5% · No upfront cost