


Indiana Public Adjusters
Hail, tornado, Ohio River flood and mine subsidence claims — read the policy before you accept the number.
Indiana property claims are decided on policy language: which peril is named, which deductible applies, and whether the damage sits inside a sublimit. We read the declarations page and endorsements first, then document the loss against them. The review is free and the decision stays yours.
Three ways an Indiana claim stalls
Many files we see are not denied. They are unfinished — a scope that missed work, a number that never moved, or a letter that cited the wrong peril.
The number came in low
Missing line items, depreciation held back, and code-required work left off the estimate are the usual reasons. We compare their scope to the policy and to the damage on site.
The claim stopped moving
Re-inspection loops, unanswered emails, adjusters reassigned off the file. We take over the correspondence and put every open item in writing.
You were denied
A denial cites a specific exclusion. Sometimes it is right. Sometimes the wrong peril was applied — wind treated as flood, or mine subsidence treated as settling.
Indiana, from the Ohio River to the lakeshore
Ten base cities and statewide coverage between them. If your property is outside these, the same service applies.



Four numbers that decide an Indiana claim
Before anyone argues about the estimate, these set the floor.
A percentage deductible is a percentage of the dwelling limit, not a flat amount. It comes off the top before the claim pays a dollar, and the trigger — named storm or any wind — decides which one applies.
Standard policies exclude it. The endorsement has to be bought before the ground moves, it exists in 26 southwestern counties, and contents are not covered.
On a replacement-cost policy, the first check pays depreciated value. The balance is released after the work is done — and only if you claim it. That second check is not automatic.
Wind is the homeowners policy. Rising water is a separate flood policy with its own deductible. On the Ohio River, one storm can hit both — and each claim stands alone.
Licensed, contracted, and tied to your policy
Indiana regulates public adjusters under IC 27-1-27. The rules are specific, and they are worth knowing before you sign with anyone.

Licensed in Indiana
JustClaims holds Indiana public adjuster license #4227875. Verify any adjuster's certificate of authority through the IDOI licence lookup.
A written contract, every time
Indiana requires a written contract and a copy to your insurer (IC 27-1-27-13), plus a disclosure document before you sign (IC 27-1-27-14). You may rescind within three business days of submitting the claim.
Policy language first
Every item we put in front of an insurer is tied to a clause: the peril, the limit, the deductible, the endorsement. If it is not in the policy, we say so.
Built for Indiana perils
Hail and tornado claims statewide, Ohio River flooding in the southwest, mine subsidence across 26 counties. Different perils need different evidence.
Property claims, by building type
Six categories that cover most of what we see. Each one carries its own documentation problem.

Single-Family Homes
Roof, siding, gutters and interior water follow-through, documented line by line against the insurer's scope.

Older & Historic Homes
Plaster, millwork, and code-required upgrades that estimating software can leave out.

Rural & Farm Properties
Dwellings, barns, grain handling and equipment, with farm structures scheduled separately.

Multi-Family, HOA & Condo
Who insures what — association master policy, unit owner policy, and the boundary between them.

Retail, Office & Small Business
Building, contents, and the income lost while the space is unusable, kept as separate schedules.

Warehouses & Industrial Property
Large roofs, racking, inventory and machinery, where a small scope error becomes a large number.
A file built to be argued
Credentials instead of claim results. We publish what we are licensed to do, not what we once recovered.
Your adjuster works for you. Theirs works for the insurer.
Indiana requires the public adjuster's contract to be in writing and copied to your insurer. That single requirement tells you who the other adjuster answers to.
Your public adjuster
Paid by you, under a written contract, with a duty to document the loss against your policy. Can be checked in the state licence lookup before you sign.
The insurer's adjuster
Paid by the insurer, working inside the insurer's estimating standards and authority limits. Their scope is an opening position, not a finding.
Four steps, in this order

Free claim review
We read the policy, the declarations page and the insurer's estimate before anyone commits to anything.

Document the loss
Photos, measurements, code citations and a line-item scope, each tied to the clause that pays for it.

Negotiate and file
We put the position to the insurer in writing and answer their adjuster's questions with evidence, not opinion.

Recover
Settlement, then the replacement-cost release and any recoverable depreciation once the work is done.
Who runs the Indiana file

Taylor Bezek
Taylor leads JustClaims' property claims work, including the Indiana files. The Indiana licence is held by the JustClaims entity (#4227875), and every Indiana claim is worked under it. On a new file he starts with the declarations page and the endorsements, then the insurer's estimate — in that order, because the policy decides which peril, limit and deductible apply. From there the loss is rebuilt line by line, and every item in the position we send back is tied to a clause you can read.
Four regions, one licence
Indianapolis Metro
Marion County and the surrounding ring — hail, wind and the dense commercial core.
Live
Fort Wayne & Northeast
Allen County and the northern tier, the state's northeast corner.
Live
Evansville & Southwest
The Ohio River corridor, where wind and flood are separate policies on the same loss.
Live
Northwest Indiana
Lake and Porter counties, the lakeshore belt along Lake Michigan.
Live
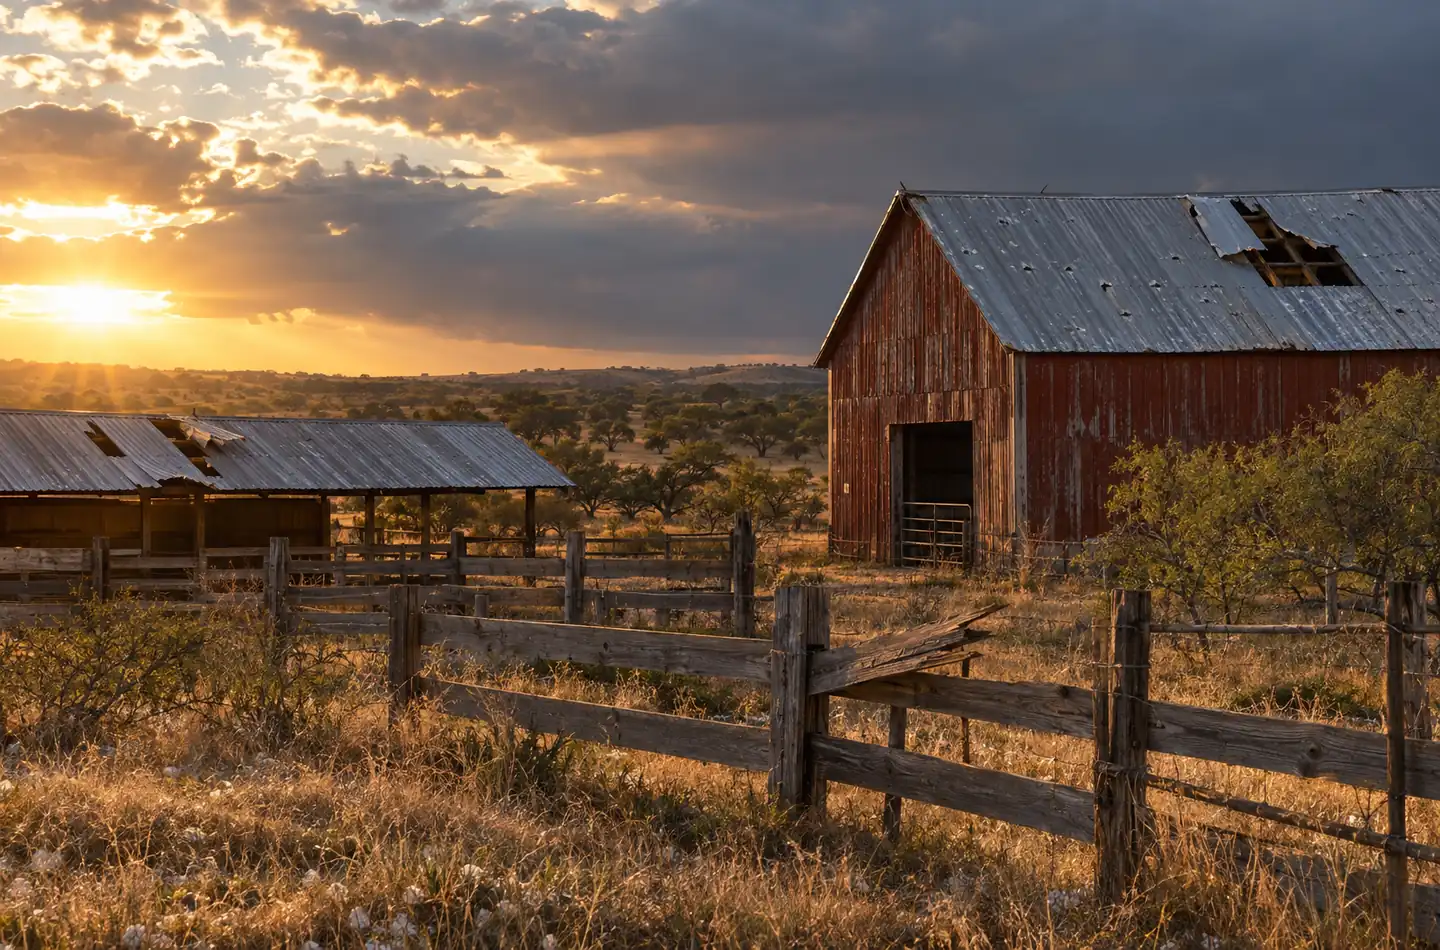
Barns, grain bins and the equipment that runs them
Farm losses often fail on the schedule, not the damage — the dwelling, the barn and the machinery sit on three different forms with three different limits.
-
Grain bins and drying
Structural damage, aeration equipment and the crop inside are three separate coverage questions.
-
Barns, outbuildings and equipment
Older structures are often under-scheduled, and tractors and implements usually sit on their own schedule. Repair cost is not replacement cost.
-
Agribusiness interruption
Lost income while a barn or drying system is down is documented on its own schedule.
Three guides that answer the obvious questions
Plain explanations of the process, written before you have to make a decision. What is a public adjuster? · Underpaid insurance claim: the steps · Wind damage on your roof
What Indiana requires of a public adjuster
A certificate of authority is required
Indiana licenses public adjusters under IC 27-1-27-2, and working without a certificate of authority is not allowed. Applicants must also file a $10,000 surety bond. Anyone negotiating your claim for compensation should be able to show the certificate, and you can verify it yourself.
Contract, disclosure, and three days to change your mind
The contract must be written and a copy sent to your insurer, with a disclosure document before you sign (IC 27-1-27-13 and -14). You may rescind within three business days after the claim is submitted, and anything of value must be returned within fifteen business days (IC 27-1-27-20).
No percentage commission on a fast policy-limit payment
If the insurer pays, or commits in writing to pay, the policy limit within five business days of the loss being reported, Indiana bars a percentage commission on that claim. The adjuster may charge only reasonable time and expenses (IC 27-1-27-18).
This page explains Indiana insurance rules in general terms and is not legal advice. Policy terms control each claim.
Last reviewed 30 October 2026.

Questions Indiana policyholders actually ask
Pricing repairs and adjusting a claim are different jobs. In Indiana a public adjuster must hold a certificate of authority from the Department of Insurance; a contractor does not. A contractor's estimate tells you what repairs cost. A public adjuster tests the insurer's scope, policy language and documentation, and can be checked in the IDOI licence lookup before you sign anything.
The fee is paid by you, not by your insurer, and it is set out in the written contract you sign before any work starts. Indiana requires that contract and a disclosure document in advance (IC 27-1-27-13 and -14). Ask for the fee in writing, ask what triggers it, and compare it with what the file actually needs.
Indiana requires a written public adjuster contract, a copy of it to your insurer, and a disclosure document before you sign (IC 27-1-27-13 and -14). Certain provisions are prohibited outright. You may rescind within three business days after the claim is submitted to your insurer, by certified mail, personal service or email (IC 27-1-27-20).
The chapter applies to a person or corporation acting as a public adjuster, so business and commercial property claims sit inside the same licensing rules. What changes is the evidence: business income, extra expense, contents and equipment breakdown are documented on their own schedules, alongside the building loss.
Yes. Indiana provides for non-resident public adjusters through a certificate of authority, and out-of-state firms can be licensed to work Indiana claims. The licence still has to exist and still has to be verifiable. Check the individual or business entity in the IDOI lookup before you hand over a signed contract or your claim file.
The scope usually changes first. Commercial estimates often miss code upgrades, mechanical damage, racking, or the cost of trading through a repair. We rebuild the scope from the policy and the site, document business income separately, and put the file back to the insurer in a form that answers the questions their adjuster will ask.
No. Standard policies exclude mine subsidence; it has to be added as an endorsement before damage occurs. It is available in 26 southwestern Indiana counties, covers up to $500,000 per structure, and carries a deductible of two percent of the policy with a $250 minimum and $500 maximum. Contents are not covered.
It is a deductible expressed as a percentage of your dwelling limit rather than a flat dollar amount. On a policy with a two percent wind deductible, two percent of the dwelling limit comes off the top before the claim pays. The percentage and the trigger — named storm or any wind event — are on your declarations page.
The Indiana Department of Insurance takes consumer complaints about insurers and can review how a claim was handled. Before you file, put your position in writing and give the insurer a clear deadline to respond. A complaint is not a substitute for the contract remedies in your policy, but it creates an outside record.
You can rescind within three business days after the day you submit the claim to your insurer (IC 27-1-27-20). Notice must be in writing — certified mail with return receipt, personal service, or email to the address on the contract. The adjuster must return anything of value within fifteen business days.
Start with the policy
Send us the declarations page and the insurer's estimate. We will tell you what the policy pays for and what it does not.
JustClaims · Indiana public adjuster license #4227875 · Indianapolis · Fort Wayne · Evansville · South Bend