Public Adjuster Fees 2026: State Caps & What You’ll Pay
November 11, 2026
Written by Collin Corcoran
Share


A public adjuster’s fee is usually a share of your claim settlement, and the share can be capped, negotiable, or barred outright depending on where the property sits. Texas caps the total commission at 10% of the settlement, Florida allows 20% on standard claims but only 10% in the year after a Governor-declared emergency, New York limits the fee to 12.5% of the recovery with a narrow supplemental-claim exception, and Louisiana voids percentage-based fees entirely. Which rule applies decides how much of the settlement stays with you.
Key Takeaways
- Texas cap: Total commission may not exceed 10% of the insurance settlement, whether the adjuster charges hourly, a flat rate, or a percentage.
- Florida cap: 20% of claim payments on standard claims, and 10% on claims made in the year after a Governor-declared state of emergency.
- New York cap: 12.5% of the recovery, with a limited 20% allowance on supplemental claims.
- Louisiana: A fee contingent on, or calculated as a percentage of, the claim is void.
- Typical range: United Policyholders puts contingency fees at 5% to 15% of what the insurer pays — capped in some states and negotiable in all.
- Who pays: You do. Maryland’s regulator says the fee is deducted from the insurer’s settlement payments.
How Contingency Fees Work and What the Percentage Applies To
A contingency fee means the adjuster is paid a share of what the claim recovers instead of billing you up front. United Policyholders describes public adjusters as getting paid a percentage of whatever they recover for you [1]. Florida requires a written contract with the named insured before an adjuster can collect a fee on claim payments [2]. If you are still learning the basics, start with our guide to what a public adjuster is. The more important question for your budget is which dollars the percentage touches.
Fee on the Total Amount the Insurer Pays
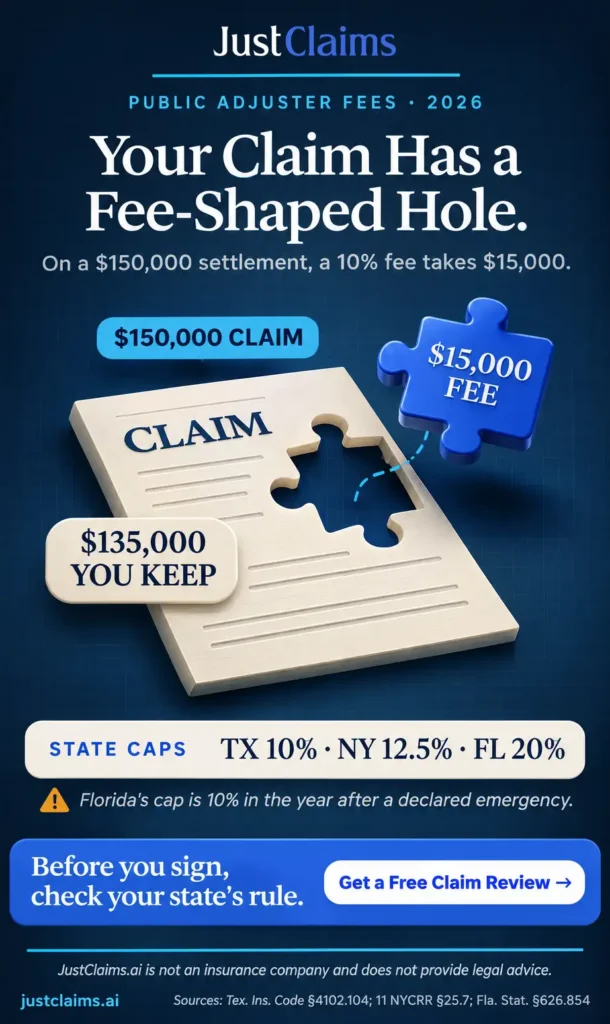
Texas lets the percentage run against the total the insurer will pay on the claim, not only the amount you dispute. The Texas Department of Insurance gives this example: if the insurer offers $100,000 and you dispute $20,000, the public adjuster could charge $10,000 [3]. The statute behind that example caps total commission at 10% of the insurance settlement and allows an hourly fee, a flat rate, or a percentage [4]. Under this approach, money the insurer had already offered still counts toward the fee base.
One exception matters if your insurer moves fast. When the insurer pays, or commits in writing to pay, the policy limit within 72 hours after the loss is reported, the adjuster may not take a percentage commission at all and is limited to reasonable compensation for time spent and expenses incurred [4].
Fee Only on Money Actually Received
Kentucky takes a narrower view. KRS 304.9-4333 requires a public adjuster’s fee to be based only on the insurance settlement proceeds the insured actually received, and the fee may be collected only after those proceeds are paid [5]. The same statute caps a reasonable fee at 10% of the settlement proceeds on which the fee may be based [5].
Fee Only on What the Adjuster Recovered After You Hired Them
New York ties the fee base to timing. Regulation 10 limits a public adjuster to 12.5% of the recovery and requires the fee to be computed on monies paid after the insured retained the adjuster [6]. Payments the insurer made before you hired the adjuster sit outside that base [6]. The same provision allows up to 20% on a supplemental claim, but only if the total fee stays at or below 12.5% of the full claim payment [6].
What the Contract Must State
Several states force the fee into writing in specific terms. Iowa requires the contract to state the exact percentage applied to the settlement if compensation is percentage-based, the exact flat amount if it is a flat fee, and the hourly rate plus how it is applied if billing is hourly [7]. North Carolina requires the exact percentage and requires initial reimbursable expenses to be itemized by type with dollar estimates [8]. Illinois requires the contract to state the full salary, fee, commission, or other compensation the adjuster is to receive, including any applicable cap [9].
Typical Fee Ranges: Percentage, Flat-Fee and Hourly Models
Because the fee comes out of your settlement, the pricing model matters as much as the headline percentage.
Percentage Fees and Typical Ranges
United Policyholders reports that most public adjusters work on contingency fees ranging from 5% to 15% of the monies the insurer pays on a claim, that those fees are capped in some states, and that they are negotiable in all states [1]. Treat that as a market benchmark, not a legal limit.
Statutes set the harder ceiling. Texas caps total commission at 10% [4]. Florida allows 20% on standard claims and 10% on claims made in the year after a declared state of emergency, and it separately caps compensation on a reopened or supplemental claim at 20% of that payment [2]. Florida also steps the fee down when the insurer pays fast: the cap is 1% where the insurer pays or commits in writing to the policy limit for a coverage part within 14 days after the date of loss or 10 days after signing, whichever is later, and zero where that payment or commitment happens before you sign [2]. New York’s ceiling is 12.5% [6].
Flat-Fee and Hourly Models
Some states let you choose among structures. Texas allows an hourly fee, a flat rate, or a percentage, subject to the same overall cap [4]. Missouri’s Department of Commerce and Insurance says public adjusters can charge a flat fee or a fee based on a percentage of the settlement [10].
Louisiana is different. Its statute allows a reasonable fee but voids any contract providing for a fee that is contingent on, or calculated as a percentage of, the amount paid on the claim [11]. In practice that means the fee has to be built on something other than a share of the recovery, so ask for the hourly rate or flat amount in writing before you sign.
State Public Adjuster Fee Caps Compared
The percentage an adjuster may take depends on where the property sits, so state rules set the ceiling on what you can be charged.
| State | Fee limit or rule | Notes |
|---|---|---|
| Texas | Total commission may not exceed 10% of the insurance settlement [4] | Hourly, flat-rate, or percentage compensation allowed; no percentage commission when the policy limit is paid or committed within 72 hours |
| Florida | 20% of claim payments on standard claims; 10% in the year after a declared emergency [2] | Reopened or supplemental claims capped at 20%; 1% where a coverage part’s limit is paid or agreed within 14 days of loss or 10 days of signing (whichever is later), 0% where it was paid or agreed before signing |
| New York | 12.5% of the recovery [6] | Up to 20% on a supplemental claim if the total stays within 12.5% of the full claim payment |
| North Carolina | No more than 10% of any settlement or proceeds [12] | The same 10% limit applies to catastrophic claims |
| Kentucky | Reasonable fee not above 10% of settlement proceeds [5] | Based only on proceeds the insured actually received |
| Hawaii | Above 15% presumed unreasonable; above 10% for catastrophic claims [13] | Applies to agreements executed on or after August 17, 2026 |
| Louisiana | No percentage fee; a reasonable fee is allowed [11] | Percentage-based contracts are null and void |
| Maryland | Percentage is negotiable and not set by law [14] | Paid by the policyholder and deducted from settlement payments |
This table covers states with fee limits verified for this update; it is not a complete list of all 50 states. Statutes change, so confirm the current limit with your state’s department of insurance before you sign anything.
Worked Fee Example on a $150,000 Settlement
Percentages feel abstract until you subtract them from a payout, so here is how the same settlement nets out at each rate above. Every figure is before other costs and assumes the whole settlement is the fee base.
| Fee rate | Fee on $150,000 | Net to policyholder | Where the rate appears |
|---|---|---|---|
| 10% | $15,000 | $135,000 | Texas cap [4] |
| 12.5% | $18,750 | $131,250 | New York maximum [6] |
| 15% | $22,500 | $127,500 | Hawaii threshold for non-catastrophic claims [13] |
| 20% | $30,000 | $120,000 | Florida standard-claim cap [2] |
The Maryland Insurance Administration says the policyholder, not the insurer, pays the fee, and it is deducted from the insurer’s settlement payments [14]. Missouri’s Department of Commerce and Insurance advises consumers to make sure they will still have enough money to repair or rebuild after paying it [10]. Run this math against your own repair estimate before you hire anyone.
When a Public Adjuster Is Worth the Fee
Because every fee dollar comes out of your payout, the real question is whether the work raises the settlement by more than the fee removes.
When the Fee May Pay Off
United Policyholders says not every policyholder with a property claim should hire a public adjuster. It depends on the policy, the size of the loss, and whether the policyholder has negotiated a major claim before[1]. It also notes that adjusters often work many hours to secure a settlement, and that consumers are generally better off paying a small percentage of what the adjuster recovers on their behalf [1]. On a large property damage claim, that trade can make sense.
When You May Do Fine on Your Own
The same guidance cuts the other way on smaller claims: the smaller the loss, the less it makes sense to hire someone on a percentage basis, and if the property is very underinsured, the fee consumes part of an already limited recovery [1]. Free routes can help before you spend on an adjuster. Many policies contain an appraisal clause for disputes over the amount of loss, explained in our comparison of appraisal and litigation, and a roofing or restoration contractor may provide written scopes and photo documentation you can submit yourself.
What an Adjuster Cannot Change
A public adjuster negotiates the claim; the insurer still decides whether to accept the damages claimed. New York’s Department of Financial Services notes that the insurer is not obligated to accept the damages claimed by a public adjuster and remains obligated to settle the claim under the terms of the policy it issued [15]. No fee arrangement changes the coverage you bought.
Contract Terms to Check Before You Sign
Since the contract is where the percentage becomes binding, a few clauses decide how much you actually pay.
Cancellation Rights
Florida gives an insured or claimant 10 days after signing to cancel a public adjuster contract without penalty, and if the contract was entered into because of a Governor-declared emergency, the window runs 30 days after the date of loss or 10 days after signing, whichever is longer [2]. New York allows cancellation without penalty until midnight of the third business day after signing and requires a signed compensation agreement that clearly states the amount [15].
Fee on Payments Already Agreed
Ask whether the percentage reaches money the insurer already agreed to pay before you hired anyone. New York’s regulation computes the fee only on monies paid after the insured retained the adjuster [6], and United Policyholders recommends settling that question — along with whether the adjuster will take a fee on additional living expense or other benefit categories — before you enter into a contract [16].
Expense Caps and Reimbursements
North Carolina requires initial expenses reimbursed from claim proceeds to be specified by type, with dollar estimates in the contract [8]. Iowa requires the exact percentage, flat amount, or hourly rate to be stated [7], and Illinois requires the full compensation to be disclosed, including any applicable cap [9]. Even where your state does not require that detail, ask for it. An open-ended expense clause can add cost on top of the percentage.
Frequently Asked Questions
What percentage do public adjusters charge?
Most work on contingency. United Policyholders reports a range of 5% to 15% of the monies the insurer pays, capped in some states and negotiable in all [1]. Your state cap can be lower than the market range — Texas is 10%[4] and New York is 12.5% [6] — so check the state table above.
Do public adjusters charge upfront fees?
Contingency arrangements pay the adjuster a share of what the insurer pays on the claim [1]. If an adjuster asks for a retainer or deposit, ask where state law allows it and put the payment timing in the contract.
Does the fee apply to my whole settlement or only the extra money recovered?
It depends on the state and the contract. Texas lets the fee run against the total amount the insurer will pay [3], Kentucky limits it to proceeds you actually received [5], New York computes it on monies paid after you retained the adjuster [6], and Louisiana bars percentage fees altogether [11]. Read the fee-base wording closely before signing.
Who pays the public adjuster, the insurer or me?
You do. Maryland’s Insurance Administration explains that the policyholder pays the fee and that it is subtracted from the insurer’s settlement payments [14], and New York’s Department of Financial Services states plainly that public adjusters are paid by you, not the insurance company [15]. That leaves less for repairs than the gross settlement.
Can I negotiate a public adjuster’s fee?
In most cases, yes. United Policyholders says these fees are negotiable in all states and capped in some [16], and Maryland describes its percentage as negotiable and not set by law [14]. Any agreed figure still has to stay under your state’s cap.
Are there states where percentage fees are not allowed?
Louisiana is one. Its statute voids any contract for a fee that is contingent on, or calculated as a percentage of, the amount paid on the claim, while still allowing a reasonable fee [11]. Confirm the current rule with the Louisiana Department of Insurance before signing anything.
Can I cancel after I sign?
Often, yes, within a set window. Florida gives 10 days, extended in declared emergencies [2], and New York gives three business days [15]. Ask what your state allows before you sign.
How to Weigh the Fee Before You Sign
Public adjuster fees are rarely a single number. The percentage, the amount it applies to, your state’s cap, and the contract’s expense terms together decide what you net. Compare the dollar outcome of each structure against your repair estimate, and keep copies of every offer and policy page.
Upload your policy and claim documents to JustClaims and get a free policy review that flags coverage language and estimate gaps before you weigh any adjuster’s fee proposal.
This content is for informational purposes only and does not constitute legal or insurance advice. Coverage decisions depend on the specific terms, conditions, and exclusions of each policy and the laws of the applicable jurisdiction; policyholders and contractors should consult with a qualified professional for advice on their particular situation.
Sources
[1] Public Adjusters: The Inside Scoop — United Policyholders
[2] Florida Statutes § 626.854: Public Adjusters (2026) — Florida Senate
[3] Public adjusters: What to know before you hire one to help with your claim — Texas Department of Insurance
[4] Texas Insurance Code Chapter 4102: Public Insurance Adjusters — Texas Constitution and Statutes
[5] Kentucky Revised Statutes § 304.9-4333: Public adjuster fees — Kentucky Legislative Research Commission
[6] 11 NYCRR § 25.7: Seventh Amendment to Insurance Regulation 10 — New York State Department of Financial Services
[7] Iowa Code § 522C.10: Public adjuster and insured — contract for services — Iowa Legislature
[8] North Carolina General Statutes § 58-33A-65: Contract requirements — North Carolina General Assembly
[9] 215 ILCS 5/1575: Contract between public adjuster and insured — Illinois General Assembly
[10] Missouri Department of Insurance warns consumers that not all insurance adjusters are the same — Missouri Department of Commerce and Insurance
[11] Louisiana Revised Statutes § 22:1703: Public adjuster compensation — Louisiana State Legislature
[12] North Carolina General Statutes § 58-33A-60: Fees and commissions — North Carolina General Assembly
[13] Commissioner’s Memorandum 2026-6A: Public Adjuster Compensation — Hawaii Department of Commerce and Consumer Affairs, Insurance Division
[14] Public Adjuster — Maryland Insurance Administration
[15] Adjusters, Appraisers & Umpires — New York State Department of Financial Services
[16] Questions to Ask Before Hiring a Public Adjuster — United Policyholders
Collin Corcoran

Experienced Public Adjuster and Property Claims Specialist, Collin is licensed in New York (#1603393), New Jersey (#3003700204), and Connecticut (#19820270). With 20+ years of hands-on construction and property damage experience, he specializes in residential and commercial claims, complex loss inspections, policy review, detailed estimating, and strategic negotiation. Collin’s background in construction, asset management, emergency response, and claims documentation allows him to accurately identify damage, understand repair requirements, and advocate effectively for policyholders. He works with homeowners, business owners, contractors, and insurance professionals to move claims forward with clarity, accuracy, and confidence. Collin is committed to transparency, technical precision, strong communication, and securing fair outcomes for policyholders.