Tenant Improvements & Betterments: Insurance Guide
October 14, 2026
Written by Stephane Elias
Share


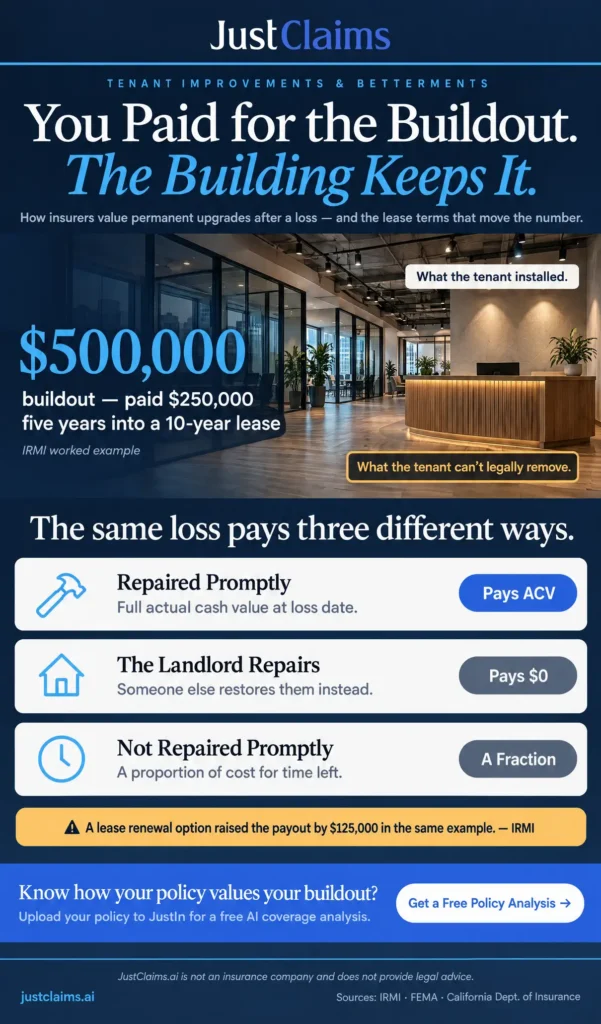
In one IRMI worked example, a tenant installs $500,000 of improvements at the start of a 10-year lease, suffers a covered loss exactly five years in and is paid $250,000 because the space is not promptly repaired. Tenant improvements and betterments coverage protects permanent upgrades a tenant pays for but cannot legally remove. How the policy values them depends on repair timing, lease length and the policy wording.
Key Takeaways
- What it is: Improvements and betterments (also written TIB) are fixtures, alterations, installations or additions a tenant makes a part of a building it occupies but does not own, at its own expense, and cannot legally remove.
- Tenant’s insurable interest: The tenant holds a “use interest” that lasts until the lease expires.
- Coinsurance: To meet coinsurance requirements, the tenant should include the value of its TIB in its property limit.
- Repair timing: Under the ISO valuation condition, prompt repair by the tenant pays actual cash value, repair or replacement paid by someone else pays nothing, and repairs not made promptly pay only a proportion of the original cost.
- Ordinance or law: Endorsement CP 04 26 09 17 can add Coverage A (undamaged portion), Coverage B (demolition) and Coverage C (increased cost of construction) for the tenant’s interest.
- Business personal property contrast: Under the ISO form, TIB sit inside the business personal property description but are valued differently from other business personal property such as furniture, equipment and inventory.
- Landlord side: TIB become part of the building, so leaving their value out of the building limit could trigger a coinsurance penalty on the owner’s policy.
What Improvements and Betterments Coverage Means
Improvements and betterments (I&B, also written TIB) are fixtures, alterations, installations or additions that become part of a building the tenant occupies but does not own. Under the ISO Building and Personal Property Coverage Form (CP 00 10 10 12, the edition IRMI discusses), the tenant acquired or made them at its own expense and cannot legally remove them [1].
FEMA’s National Flood Insurance Program glossary uses a similar definition: fixtures, alterations, installations or additions made or acquired solely at a tenant’s expense and comprising part of an insured building [2].
Because the tenant does not own the structure, its insurable interest is a “use interest” that lasts until the lease expires [1]. In most cases the building owner owns the improvements, though IRMI notes that ownership can differ depending on lease terms or real estate law in a particular jurisdiction [1]. To meet coinsurance requirements, the tenant should include the value of the TIB in its property limit [1].
Not every policy follows the ISO form. Non-ISO forms must be checked for their specific wording, so a tenant should not assume that standard definitions apply [1].
Improvements vs. Business Personal Property
Classification matters because the ISO form values TIB losses differently from losses to other business personal property, so the first task is separating permanent improvements from movable property and removable trade fixtures [1].
Permanent Upgrades Attached to the Space
Tenant improvements and betterments are permanent upgrades attached to the leased space. IRMI’s example buildout includes new flooring, new interior walls, electrical wiring, plumbing, a restroom and lighting fixtures. Under the ISO definition, the tenant paid for these items and cannot legally remove them [1].
Not everything a lease makes the tenant pay for is TIB. Building glass, HVAC equipment, improvements the landlord made before the tenant moved in and improvements a previous tenant left behind are not TIB, because the tenant did not acquire or make them at its own expense.
IRMI points to two ISO endorsements designed for that exposure: Scheduled Building Property Tenant’s Policy (CP 14 01 09 17) and Unscheduled Building Property Tenant’s Policy (CP 14 02 09 17) [1].
Movable Property and Removable Trade Fixtures
Other business personal property generally consists of furniture; fixtures, machinery and equipment that are not permanently installed; inventory; and other personal property the business owns and uses [3]. Trade fixtures that a tenant can legally remove are not the building owner’s property.
IRMI says they are covered as business personal property but valued differently from improvements: in the worked example below, they are paid at actual cash value, which produces a higher figure than the improvements receive in the same scenario [1].
A single buildout can contain both categories, so it helps to know which category each item falls into before a loss [1].
How Valuation Rules Shape the Payout
Classification is only one driver of the payout. The ISO valuation condition describes how TIB losses are valued, and it does so in three ways:[1]
- Prompt repair by the tenant: The policy pays actual cash value. Activating the optional replacement cost coverage can change that to replacement cost [1].
- Repair or replacement paid by someone else, such as the building owner: The policy pays nothing [1].
- Repairs not made promptly: Only a proportion of the original cost is paid [1].
A Worked Example of the Gap
IRMI illustrates the effect with a tenant that installs $500,000 of TIB at the start of a 10-year lease. Exactly five years in, a covered loss damages the TIB, and the tenant does not repair them because it closes the business.
The actual cash value is $400,000, but the tenant is paid only the unamortized portion of the original cost [1].
The policy’s method multiplies the original cost by the days from the loss to lease expiration, then divides by the days from installation to lease expiration: $500,000 x 1,825 days / 3,650 days = $250,000 [1].
| Scenario | Basis of payment | Payout |
|---|---|---|
| Improvements, no renewal option | Unamortized original cost | $250,000 |
| Improvements, 10-year renewal option | Lease period counts as 20 years | $375,000 |
| Removable trade fixtures | Actual cash value | $400,000 |
Source: IRMI worked example [1]. IRMI states the trade-fixture payment as $400,000 less the deductible.
The same loss produces three different payments depending on lease terms and classification. Lease renewal options and the repair decision therefore carry real financial weight in an I&B claim.
Coverage Gaps Beyond Valuation
Valuation and classification are not the only places where recovery can shrink. Gaps can also open when code requirements, lease termination or overlapping landlord coverage come into play.
Ordinance or Law Exposure
A tenant can also face an ordinance or law exposure. In IRMI’s example, a fire causes $100,000 of damage to a tenant’s $500,000 buildout, but the town orders the entire building demolished, including undamaged improvements, and current building codes add $50,000 to the rebuild [1].
The ISO endorsement CP 04 26 09 17 (Ordinance or Law Coverage for Tenant’s Interest in Improvements and Betterments) can include three coverages, plus a post-loss ordinance or law option [1]:
- Coverage A: loss to the undamaged portion of the TIB.
- Coverage B: demolition cost.
- Coverage C: increased cost of construction.
California’s Department of Insurance describes the same three-part structure for building ordinance or law coverage and notes that replacement cost must be in effect for Coverage C to apply [3].
The CP 15 31 09 17 endorsement (Ordinance or Law-Increased Period of Restoration) adds to the business income period of restoration the extra time needed to comply with ordinances or laws [1]. IRMI notes that enforcing those laws lengthens the tenant’s suspension of operations, so the business income coverage needs a modification to match [1].
Lease Termination After Building Damage
If the building is damaged but the TIB are not, the tenant can still lose them. In IRMI’s example, the landlord uses its lease rights to cancel the lease after fire damage, and the tenant, who cannot legally remove the TIB, loses use of them for the rest of the lease period [1].
IRMI cites commonly used lease language that lets a landlord terminate on 30 days’ notice after damage that is not covered by the landlord’s insurance or that would cost more than 25% of replacement cost to repair [1].
The law can create the same problem: California Civil Code §1933 provides that the hiring of a thing terminates “by the destruction of the thing hired” [4]. Other states’ laws may differ.
The ISO Leasehold Interest Coverage Form (CP 00 60 06 95) addresses this exposure by paying the unamortized portion of the payments the tenant made for improvements and betterments when a covered loss leads to cancellation of the lease. It excludes value recoverable under other insurance [1].
Landlord and Tenant Policy Overlap
The landlord’s policy can be affected too. IRMI describes a common misunderstanding that the owner need not consider TIB value because the lease makes the tenant responsible for insuring them.
TIB become part of the building and fit the building description in the Building and Personal Property Coverage Form, and the coinsurance condition does not depend on who owns the property or who the lease says must insure it, so leaving TIB value out of the building limit could trigger a coinsurance penalty [1].
California’s Department of Insurance likewise explains that building coverage includes completed additions and permanently installed fixtures, and that a building not insured to value can face a coinsurance penalty at the time of loss [3].
If an owner does not want to cover the TIB, IRMI says the owner’s policy should be endorsed to reflect that, commonly with the Additional Property Not Covered endorsement (CP 14 20 11 91) [1]. A property owner who leases space should confirm how tenant upgrades are reflected in the building valuation, and a tenant should confirm its own limit includes them.
What to Document and Review Before a Loss
The payout formula turns on original cost, lease period and classification, so those are the records worth organizing before a loss. The facts above point to several practical steps for tenants and property owners:
- Record the original cost of each improvement. The unamortized-cost calculation starts from the original cost [1].
- Keep the lease, including renewal options. In IRMI’s example, a renewal option changed the payout by $125,000 because it lengthened the lease period used in the calculation [1].
- Check what the lease requires. If the lease requires the tenant to insure TIB for the benefit of both the tenant and the building owner, a limit that covers only the tenant’s use interest may not be enough, because unrepaired TIB can be paid at less than actual cash value [1].
- Separate permanent upgrades from movable and removable items. Flooring, interior walls, electrical wiring, plumbing and lighting fixtures are examples of TIB. Furniture, equipment, inventory and legally removable trade fixtures fall in other categories [1][3].
- Include TIB value in the property limit. This supports meeting coinsurance requirements [1].
- Ask whether optional replacement cost coverage is active. Without it, ACV is the default measure for prompt repairs [1].
- Read the actual policy form. Non-ISO wording can differ from the ISO definitions [1].
Frequently Asked Questions
What does improvements and betterments coverage insure?
It insures a tenant’s use interest in permanent additions it paid for in a building it does not own, such as alterations, installations and fixtures. The tenant cannot legally remove these items, and the building owner usually owns them, so the tenant’s interest lasts for the length of the lease.[1]
What are examples of tenant improvements and betterments?
IRMI’s example buildout includes new flooring, new interior walls, electrical wiring, plumbing, a restroom and lighting fixtures. Items the tenant can legally remove, such as trade fixtures, are treated differently.[1]
How is I&B different from business personal property?
Under the ISO form, the tenant’s use interest in improvements and betterments is listed within the business personal property description, but TIB losses are valued differently from losses to other business personal property.[1]
Other business personal property generally consists of furniture; fixtures, machinery and equipment that are not permanently installed; inventory; and other personal property the business owns and uses.[3]
Improvements and betterments are permanent upgrades attached to the space, such as flooring, interior walls, electrical wiring, plumbing and lighting fixtures.[1]
Why might an insurer pay less than the actual cash value of tenant improvements?
When repairs are not made promptly, the ISO condition pays only a proportion of the original cost, based on the unamortized portion. In IRMI’s example, the tenant was paid the unamortized portion rather than the full actual cash value.[1] In that example, counting a renewal option lengthened the lease period and raised the payment.[1]
What happens to tenant improvements if the landlord cancels the lease after a loss?
The tenant can lose use of improvements that were not themselves damaged, because it generally cannot legally remove them. The ISO Leasehold Interest Coverage Form addresses this by paying the unamortized portion of the tenant’s payments for the improvements when a covered loss leads to cancellation of the lease.[1]
Should a landlord’s policy account for tenant improvements?
Usually, yes. Tenant improvements become part of the building, so leaving their value out of the building limit could trigger a coinsurance penalty unless the owner deliberately removes them from covered property by endorsement.[1]
How to Protect Your Improvements and Betterments Value
Tenant improvements that are not promptly repaired are valued by a formula based on the original cost and the remaining lease term, and classification, repair timing, lease length and endorsements each move the payout. IRMI’s example shows a single loss producing payments that differ by six figures.[1]
Before a loss, find out what your own policy says about your buildout. Upload your policy to JustIn for a free AI coverage analysis for commercial property from the licensed public adjusters at JustClaims. JustIn reads your policy page by page and surfaces the specific language, endorsements, sub-limits and exclusions that apply, so you can compare them with your lease and review them with your broker. What it surfaces is information, not a verdict.
This content is for informational purposes only and does not constitute legal or insurance advice. Coverage decisions depend on the specific terms, conditions, and exclusions of each policy and the laws of the applicable jurisdiction; policyholders and contractors should consult with a qualified professional for advice on their particular situation.
Sources
[2] Improvements and Betterments (NFIP Glossary) — FEMA
[3] Commercial Insurance Guide — California Department of Insurance
[4] California Civil Code § 1933 — California Legislative Information

Stephane Elias
A seasoned insurance professional with nearly a decade of experience, Stephane Elias is currently serving as a Senior Claims Professional and Public Adjuster with JustClaims. Throughout his career, Stephane has represented policyholders through leading public adjusting firms and served as a loss consultant for law firms specializing in insurance litigation, giving him extensive expertise in complex property insurance claims. A licensed public adjuster in TX (#2645032), FL (#W564547), and six other states, he specializes in commercial and residential property claims, claims management, appraisals, mediation, and strategic partnerships. Stephane is passionate about helping policyholders overcome delayed, denied, and underpaid insurance claims, ensuring they receive the full recovery they’re entitled to under their policy.