


Commercial Restoration Claims: Documentation Guide 2026

August 24, 2026
Written by Taylor Bezek
Share


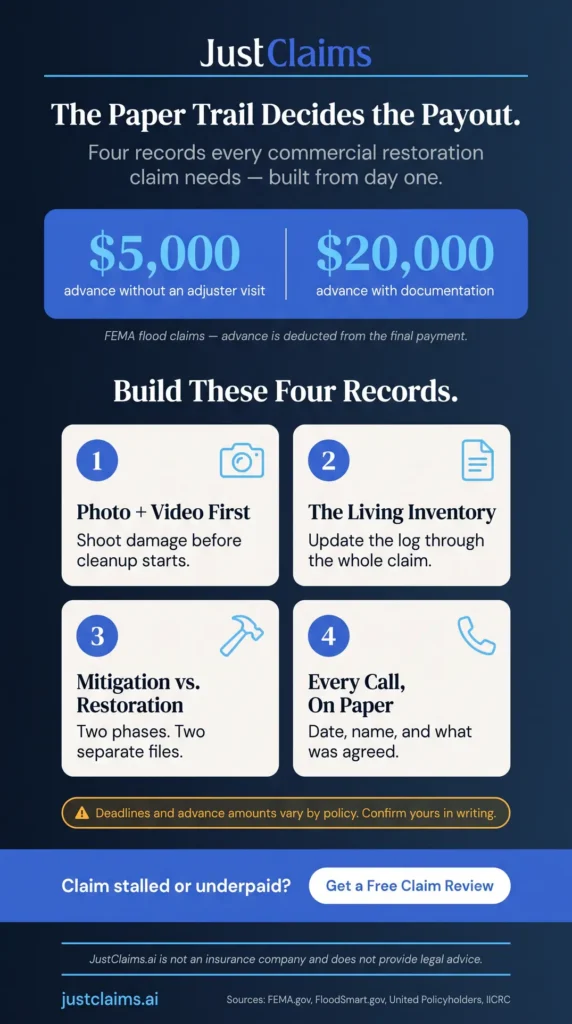
Commercial property owners and contractors filing restoration claims carry the full weight of the burden of proof — and that burden is measured in dollars and days. During major flood events, FEMA allows advance payments of up to $5,000 without an adjuster’s visit, or up to $20,000 with authorization and documentation. Every dollar beyond that depends on the paper trail you build from day one. A missing photo, an incomplete inventory log, or a late Proof of Loss can turn a covered loss into a disputed one.
Key Takeaways
- Immediate evidence standard: FEMA’s NFIP advises documenting structural damage, floodwater levels, and appliance serial numbers with photos and video before any cleanup begins.
- Physical sample retention: FloodSmart.gov recommends keeping swatches of damaged materials, such as carpet, flooring, and curtains, before disposal.
- Proof of Loss requirement: NFIP policyholders must submit a signed and sworn Proof of Loss with supporting documentation within the applicable claim deadline.
- Advance payment thresholds: During major flood events, FEMA allows advance payments of up to $5,000 without an adjuster’s visit, or up to $20,000 with authorization and documentation.
The Four Documentation Requirements That Protect Your Claim
Large-scale commercial losses put the burden of proof squarely on the property owner and the restoration contractor, and that proof has to hold up to adjuster scrutiny long after the damage is dried, demoed, or discarded. The four documentation categories below reflect what insurers and federal programs consistently look for when evaluating whether a claim was mitigated, restored, and priced appropriately.
1. Immediate Photo and Video Documentation
Before any cleanup or content removal starts, FEMA’s National Flood Insurance Program guidance calls for photographs and video that capture structural damage, standing floodwater levels both inside and outside the building, and damage to appliances, furniture, and other contents — including make, model, and serial numbers for major equipment and electronics.[1] This evidence gives the adjuster what they need to prepare an accurate repair estimate, and timestamped files establish exactly when the damage was recorded relative to the loss date.
Property managers and contractors should also hold onto physical samples of damaged materials, such as carpet, flooring, and window treatments, and photograph them before disposal [2]. FloodSmart.gov notes that the final payout a policyholder receives depends heavily on the documentation provided to the adjuster, which means discarding damaged materials too early can weaken a claim that would otherwise be fully supported [2].
2. Inventory Logs and Business Interruption Records
A detailed, itemized inventory log connects the physical damage documented on day one to the financial loss claimed later. For commercial properties, this typically means cross-referencing damaged contents against purchase records, depreciation schedules, and business interruption figures such as lost revenue, extra expense, and continuing operating costs during the closure period. Those figures are exactly what the Xactimate estimate has to reconcile against when the scope is priced, so keeping the log current keeps the estimate defensible.
Because so much of the final settlement depends on the completeness of this record [2], property managers should treat the inventory log as a living document updated throughout the claim, not a one-time exercise. Commercial policyholders must also submit a signed and sworn Proof of Loss with supporting documentation within the applicable claim deadline; missing that deadline can put full or partial payment at risk [3].
3. Mitigation vs. Restoration Documentation
Mitigation and restoration are legally and financially distinct phases of a commercial loss, and insurers expect separate documentation for each. Mitigation covers the emergency work — water extraction, drying, and stabilization — while restoration covers the rebuild scope that follows once the structure is dry and safe.
Contractors who maintain this log in real time give the adjuster a clear, dated record that supports the position that mitigation was performed to standard and that the restoration scope that followed was necessary, not discretionary.
4. Communication Logs With Adjusters
Every call, email, and site visit with an adjuster should be logged with a date, a name, and a summary of what was discussed or agreed. This record matters most when a claim stalls or when advance payments are involved: FEMA permits advance payments up to $5,000 without an adjuster visit, or up to $20,000 with authorization and documentation, with the advance later deducted from the final claim payment [2]. A documented communication trail helps property owners and contractors show when documentation was submitted, when a response was due, and when a commitment was made — details that often decide how quickly a claim moves from review to payment. Knowing how a claims adjuster works that trail makes the next conversation with the carrier far easier to prepare for.
Frequently Asked Questions
Because so many claim disputes trace back to gaps in the documentation trail rather than the underlying damage itself, contractors and property managers raise similar questions when preparing a commercial restoration claim.
What are the most important documents in a commercial restoration claim?
There isn’t one document that carries the whole claim — adjusters weigh the combination of initial photo and video evidence, itemized inventory logs, and daily mitigation records together. Missing any one of these categories can weaken an otherwise well-documented loss, so contractors should treat the four documentation areas as interdependent rather than optional add-ons.
How soon should photo and video documentation begin after a loss?
Documentation should begin before any cleanup, demolition, or content removal starts, since FEMA guidance specifically calls for capturing structural damage, floodwater levels, and appliance details prior to moving or discarding anything.[1] Once materials are removed or discarded without photos, that evidence generally cannot be recreated.
What happens if a Proof of Loss is submitted late?
Under NFIP rules, a signed and sworn Proof of Loss with supporting documentation must be submitted within the applicable claim deadline, and missing that window can result in losing rights to full or partial payment [3]. Property managers should confirm the exact deadline with their carrier or adjuster as early as possible in the claim process rather than assuming a standard timeframe applies.
Why does the IICRC S500 Standard matter for insurance claims, not just restoration quality?
The ANSI/IICRC S500 is the consensus standard describing the procedures and precautions for water damage restoration in residential, commercial, and institutional buildings — and its scope explicitly includes administrative procedures, project documentation, and risk management alongside psychrometry and drying technology [4]. When a contractor’s mitigation file is built around the same categories the standard covers, the adjuster is looking at a record organized the way the industry’s own reference point expects it to be organized. Without that kind of structured log, an insurer has less basis to distinguish necessary mitigation from work it may consider excessive.
Can a commercial property owner receive claim funds before the full documentation package is complete?
Yes, in certain flood claim situations FEMA allows advance payments up to $5,000 without an adjuster’s visit, or up to $20,000 with authorization and documentation, with the advance deducted from the final claim payment [2]. This mechanism illustrates how faster, more complete documentation can translate directly into faster access to funds.
How You Can Protect Your Claim Payout
The burden of proof in a commercial restoration claim rests on the documentation built in the first hours and days after a loss, not on arguments made months later during a dispute. Photo and video evidence, inventory and business interruption logs, mitigation-versus-restoration records, and a written communication history with the adjuster together form the case file that determines how fast — and how completely — a claim gets paid. On fire losses especially, bringing in a commercial fire public adjuster early keeps that case file pointed at the full scope of the damage instead of the carrier’s first number. If your insurance claim was denied or underpaid, JustClaims’ expert team — accelerated by our bespoke AI — reviews the policy language, compares it against your documentation, and flags likely underpayments so you can go back to the carrier with confidence.
This content is for informational purposes only and does not constitute legal or insurance advice. Coverage decisions depend on the specific terms, conditions, and exclusions of each policy and the laws of the applicable jurisdiction; policyholders and contractors should consult with a qualified professional for advice on their particular situation.
Sources
[1] How Do I Start My Flood Claim? — FEMA.gov
[2] How to Start a Flood Insurance Claim — FloodSmart.gov (NFIP)
[3] Flood Insurance Claim Deadlines — United Policyholders
[4] ANSI/IICRC S500 Standard for Professional Water Damage Restoration — IICRC
Taylor Bezek

As the General Manager at JustClaims, Taylor Bezek brings over a decade of experience managing complex residential, commercial, and large-loss claims. A licensed Public Adjuster in TX (#2125659), FL (#W455048), CO (#769172), and 10 additional states, Taylor founded his own firm before joining JustClaims to scale a tech-forward solution for the insured. He is committed to combining industry expertise with AI to enhance speed, clarity, and outcomes for every policyholder. Taylor's mission is to modernize the public adjusting profession and ensure owners get exactly what they are entitled to.


